



Worldwide Battery Leak Detection Sensor Market: Why 15.52% CAGR Reshapes EV Safety & Regional Dynamics

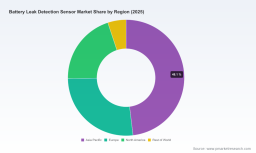
Strategic Trends and Commercial Opportunities in the Worldwide Battery Leak Detection Sensor Market
Market Overview: Scale, Growth Trajectory, and Structural Realities
The global battery leak detection sensor market has entered a phase of accelerated expansion, driven by the rapid proliferation of lithium-ion energy storage and electric mobility applications. Valued at approximately 165.4 million USD in 2020, the market reached 388.5 million USD by 2025, reflecting a compounded annual growth rate of 15.52 percent over the historical period. This momentum is projected to continue through the forecast horizon, with revenues expected to surpass the 1 billion USD threshold by 2032. The growth trajectory underscores a fundamental shift: leak detection has transitioned from a peripheral quality assurance step to an integrated, mission-critical component of battery system architecture.
Automatic Leak Detection Equipment Market
Behind the headline figures lies a market structure characterized by moderate concentration and accelerating technological diversification. The top three players capture roughly 42 percent of overall revenue, while the top five account for just under 60 percent. This leaves substantial room for specialized innovators, regional players, and emerging entrants to carve out defensible positions. At the same time, the rapid escalation in demand has exposed structural friction points that will shape competitive dynamics over the next several years.
Three critical challenges define the current inflection point. First, the industry is grappling with a fragmentation of detection requirements across the battery value chain. Manufacturing-stage inspection demands sub-micron sensitivity for electrolyte solvent vapors, whereas field-deployed battery management systems require robust, real-time gas monitoring capable of triggering early warnings for thermal events. Bridging these distinct performance envelopes within a single product family remains a persistent engineering and commercial hurdle.
Second, standardization and functional safety compliance are evolving faster than many suppliers can adapt. Automotive and energy storage developers increasingly mandate safety-oriented design frameworks that integrate leak detection into broader risk mitigation architectures. Sensors must demonstrate not only chemical selectivity and response speed, but also compliance with automotive-grade functional safety expectations and manufacturing quality protocols. Companies that treat detection as a commodity component are finding themselves excluded from qualification processes that prioritize traceable, validated performance.
Third, the supply chain for specialized detection media and calibration infrastructure introduces cost and continuity risks. High-precision leak testing in production environments often relies on trace gases that require recovery and recycling systems to maintain economic viability. Simultaneously, raw material volatility and geopolitical shifts in sensor component sourcing are pressuring margin structures. Navigating these constraints without compromising detection fidelity requires deliberate engineering choices and long-term supplier partnerships.
These dynamics create a clear strategic imperative: success in this market will increasingly depend on the ability to align detection technology with application-specific risk profiles, regulatory expectations, and total cost of ownership considerations. Companies that can translate sensitivity specifications into actionable system-level value will capture disproportionate share as the market matures.
Key Drivers Shaping Market Expansion
The acceleration of battery leak detection sensor adoption is not the result of a single catalyst. Rather, it reflects a convergence of technological breakthroughs, regulatory pressure, shifting demand behaviors, and structural changes in how battery systems are designed and manufactured. Understanding these drivers is essential for anticipating where value will be created and which capabilities will separate winners from followers.
Technological innovation remains the most visible driver, particularly in sensor architectures that enable earlier, more selective detection of failure precursors. Traditional pressure-based leak methods are increasingly being supplemented or replaced by gas-phase detection techniques capable of identifying electrolyte solvent vapors at concentrations far below the thresholds of conventional approaches. Advanced quadrupole mass spectrometry configurations, for example, allow manufacturing lines to detect leaks that are orders of magnitude smaller than what pressure decay systems can reliably identify. This level of sensitivity is especially relevant during cell filling and sealing operations, where even trace electrolyte loss can compromise long-term performance and safety margins.
At the system integration level, detection technologies are being engineered directly into battery management ecosystems rather than treated as standalone inspection tools. Sensors designed for in-field deployment now incorporate communication protocols compatible with vehicle and energy storage control architectures, water- and dust-resistant enclosures, and compensation mechanisms that account for humidity and pressure fluctuations. These capabilities enable continuous monitoring rather than periodic spot checks, transforming leak detection from a production-line gate into an operational safety layer.
Policy and regulatory environments are reinforcing this technological shift. Safety-oriented standards and functional safety frameworks are gaining traction across both automotive and stationary storage sectors. The expectation that battery systems must demonstrate robust risk mitigation has pushed detection sensors into qualification pipelines that previously focused primarily on cells and packs. Manufacturers are increasingly required to show that electrolyte leakage and early-stage thermal runaway indicators can be detected and managed within defined safety tolerances. Compliance with quality management frameworks is also driving adoption, as direct solvent detection after cell filling provides auditable evidence of production integrity.
Demand-side behavior is evolving in parallel. The rapid scaling of electric vehicle platforms has elevated battery safety from a technical specification to a brand and liability concern. Fleet operators, automotive OEMs, and energy storage developers are investing in detection layers that reduce the probability of field failures, simplify warranty management, and support downstream serviceability. Consumer electronics manufacturers, while operating at smaller revenue scales, are also seeking detection solutions that can be embedded in compact devices to address the same underlying failure modes in high-volume production environments.
Supply chain and cost structures are reshaping how these technologies reach the market. As detection requirements become more application-specific, suppliers are differentiating not only on sensor chemistry and signal processing, but also on integration ease, calibration stability, and lifecycle support. Helium-based high-precision testing, for instance, has matured to include recovery and reuse systems that soften the impact of trace gas costs, making advanced inspection more viable at scale. At the same time, functional safety compliance and robust environmental packaging add engineering overhead that smaller or less specialized players may struggle to absorb. The result is a market in which value is increasingly tied to the completeness of the solution rather than the sensor alone.
The interaction of these drivers is producing a coherent trend: leak detection is being embedded earlier in product development and more deeply into operational architectures. Companies that can align sensor performance, system integration, and compliance readiness are best positioned to convert this demand into durable revenue streams.
Competitive Landscape and Leading Strategies
The competitive environment in battery leak detection sensors is defined by a mix of established sensor manufacturers, specialized leak testing equipment providers, and emerging innovators targeting specific failure signatures. Rather than competing solely on price, leading players are differentiating through detection methodology, system compatibility, and the ability to address both production-line and field-monitoring use cases.
The Swiss-based and European sensor specialists illustrate a strategy centered on high-precision detection and functional safety alignment. Companies in this group have focused on gas-phase detection platforms that directly identify electrolyte solvent vapors and hydrogen signatures, often pairing these capabilities with communication and packaging features suited for battery management integration. Their value proposition leans on selectivity, certified safety orientation, and the ability to detect failures earlier than conventional pressure methods allow. By embedding detection logic into architectures that can interface with control systems, these players position their sensors as part of a broader safety and quality framework rather than as isolated test instruments.
Chinese manufacturers have pursued a complementary but distinct path, emphasizing modular gas detection solutions that address multiple leak and thermal runaway indicators across electric vehicle battery enclosures and energy storage installations. Their offerings frequently span hydrogen, carbon monoxide, and volatile electrolyte component detection, giving system integrators a broader set of inputs for early-warning logic. This approach reflects the scale and speed of regional battery manufacturing ecosystems, where multi-gas monitoring and cost-sensitive integration are prioritized alongside performance. The emphasis on application-targeted modules enables faster deployment in high-volume settings while maintaining flexibility across different pack designs.
Japanese firms have concentrated on precision leak testing infrastructure for battery cases and components, particularly in manufacturing environments where helium and hydrogen-based inspection methods deliver high-speed, high-accuracy results. Their relevance lies in upstream quality assurance, where detecting micro-leaks before cells are sealed can materially reduce downstream failure risk. These players often support recovery systems and process-oriented testing configurations that make high-precision inspection economically sustainable at scale. Their strategic advantage is rooted in process expertise, repeatability, and the ability to serve both prototype and mass production workflows.
PW Consulting
Meanwhile, established test equipment and automation providers from Europe, North America, and Asia are expanding their roles from component-level inspection to integrated testing solutions that span cells, modules, and packs. These organizations bring production-line integration experience, automation capabilities, and cross-application familiarity that are valuable to battery manufacturers seeking to standardize quality checks across diverse product lines. By offering customizable leak testing systems and participating actively in industry exhibitions and standards discussions, they reinforce their positioning as partners in manufacturing scale-up rather than mere sensor vendors.
Emerging specialists are entering the market with a sharper focus on early-warning signatures specific to lithium-ion electrolyte behavior. By targeting the gas patterns associated with early failure modes, these entrants aim to differentiate in a segment where incremental improvements in detection speed and selectivity can translate into meaningful safety benefits. Their presence indicates that the market is not consolidating into a single winner-takes-all structure; instead, it is fragmenting into capability-driven niches. This fragmentation creates opportunities for companies that can demonstrate clear, application-specific advantages, but it also raises the bar for proving reliability and integration compatibility.
Looking ahead, the competitive landscape is likely to evolve through a combination of consolidation among broader sensor and test equipment players and continued entry by specialists addressing unresolved detection challenges. Integration readiness, functional safety alignment, and total cost of ownership will increasingly determine which suppliers are selected for qualification. Companies that can connect detection performance to downstream operational and warranty outcomes will be better positioned to defend pricing and expand share as the market matures.
Forward Outlook: Three Trends Shaping the Next Three to Five Years
The market trajectory points toward a more integrated, safety-driven, and application-specific future for battery leak detection sensors. Several trends are likely to dominate the coming years, each carrying distinct commercial implications.
First, detection will continue shifting from discrete inspection events to continuous, system-level monitoring. As battery management architectures become more sophisticated, sensors that can communicate directly with control units and deliver early warnings for hydrogen, electrolyte vapor, or other failure indicators will become standard in high-value applications. This shift expands the addressable use case beyond manufacturing quality control into operational safety, creating opportunities for suppliers that can deliver stable long-term performance, low false-alarm rates, and integration simplicity.
Worldwide Battery Voltage Sensors Market
Second, regulatory and functional safety expectations will tighten the link between detection performance and product qualification. Battery developers will increasingly require documented detection sensitivity, compensation for environmental variables, and alignment with safety-oriented design principles. Suppliers that can provide traceable validation and demonstrate compatibility with automotive and storage safety frameworks will face fewer barriers to adoption. Those relying on generic specifications will encounter growing friction as qualification processes become more rigorous.
Third, the market will likely see increased emphasis on total cost of ownership rather than unit sensor pricing. High-precision manufacturing inspection will continue to demand recovery systems, calibration stability, and process integration, while field-deployed monitoring will prioritize durability, communication reliability, and maintenance burden. Companies that can reduce lifecycle costs through robust design, straightforward integration, and predictable performance will be better positioned to scale across multiple regions and applications.
These trends create opportunities for players that can combine technical performance with system-level value. However, uncertainty remains. The pace of battery chemistry evolution may alter failure signatures and shift detection requirements. Economic cycles can affect capital expenditure timing for new production lines and fleet deployments. Supply constraints for specialized components or trace gases may pressure margins if recovery and recycling infrastructure does not keep pace. Navigating these uncertainties will require a clear understanding of where detection adds the most risk-mitigation value across the battery lifecycle.
Strategic Priorities for Decision-Makers
For battery manufacturers and system integrators, the immediate priority is to align leak detection strategy with both production quality and field safety objectives. Selecting sensors or testing systems solely on sensitivity metrics can overlook integration complexity, calibration stability, and lifecycle support requirements. A more effective approach is to define detection requirements around the specific failure signatures most relevant to each battery architecture, then evaluate suppliers on their ability to deliver validated performance within the intended operating environment. Early engagement during pack or module design can reduce retrofit costs and improve qualification outcomes.
For investors, the market rewards companies that combine differentiated detection technology with credible integration pathways and compliance readiness. Capital allocation should favor players that can demonstrate application-specific advantages, stable manufacturing scale-up, and a clear route to system-level adoption rather than those competing purely on component pricing. Monitoring which suppliers are gaining traction in functional safety-aligned qualification processes and which are expanding into continuous monitoring use cases can provide early signals of durable competitive positioning.
For procurement and supply chain leaders, total cost of ownership should guide evaluation. Factors such as calibration frequency, environmental compensation, communication compatibility, and recovery or recycling requirements can materially affect operational expense over the life of the program. Establishing qualification criteria that reflect these longer-term considerations, rather than focusing exclusively on upfront unit cost, will help reduce hidden risks and improve supply continuity.
Given the pace of technological change, regulatory evolution, and application diversification, detailed segmentation data, competitive benchmarking, and scenario-based forecasting are essential for informed decision-making. A comprehensive market research report can provide the granular breakdowns and customized analysis needed to translate these strategic themes into concrete investment, sourcing, and product development choices.
For detailed analysis of this topic, please visit the official page: Worldwide Battery Leak Detection Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


