



Worldwide Bio-engineered Stent Market: Why 8.12% CAGR Changes Everything

Global Bio-engineered Stent Market: Strategic Trends and Commercial Opportunities
The global bio-engineered stent market has entered a phase of mature expansion, characterized by steady revenue growth and evolving clinical standards. In 2025, the market reached an estimated revenue baseline of approximately $1,420 million, building on a consistent upward trajectory from 2020 through 2025. Projections for the 2026-2032 period indicate a compound annual growth rate of 8.12%, which would lift total market value to roughly $2,452 million by the end of the forecast window. This growth reflects both the expanding adoption of advanced coronary and peripheral interventions and the steady replacement of legacy bare-metal and first-generation drug-eluting platforms with next-generation bio-engineered designs.
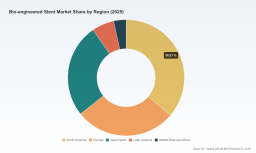
Behind these headline figures lies a market structure defined by notable concentration and rapid technological iteration. A small group of dominant players accounts for a majority of global revenue, while regional performance remains uneven. North America and Europe continue to anchor substantial portions of total demand, supported by established reimbursement frameworks and high procedural volumes. Asia Pacific represents a rapidly scaling region, driven by expanding healthcare infrastructure and growing procedural capacity. Latin America and the Middle East and Africa contribute smaller but increasingly strategic shares, often serving as early adoption zones for cost-optimized and regionally tailored solutions. The application landscape remains heavily weighted toward coronary artery disease, though peripheral artery disease interventions are gaining incremental momentum as operator experience with bio-engineered platforms extends beyond coronary territories.
Despite the favorable growth trajectory, the industry faces several structural challenges that will shape competitive outcomes over the next decade. The first is the tension between clinical performance expectations and the economic realities of device procurement. Health systems are increasingly scrutinizing cost-per-procedure metrics, pushing manufacturers to demonstrate not only superior restenosis and thrombosis profiles but also measurable reductions in repeat interventions and downstream care costs. The second challenge is regulatory and post-market complexity. As bio-engineered stents are classified as high-risk devices, manufacturers must navigate rigorous premarket approval pathways and sustain long-term post-market surveillance commitments, which raises the barrier to entry and compresses the window for rapid product cycles. The third challenge stems from raw material and manufacturing constraints. Medical-grade bioabsorbable polymers and specialized coating technologies remain costly, and supply chain volatility can disproportionately affect margins for smaller manufacturers or novel entrants attempting to scale production. These pressures are not merely operational; they are reshaping who can compete, where value is captured, and how quickly innovation reaches the bedside.
Key Drivers of Market Change
Technology innovation remains the central engine of market evolution. The shift from permanent metallic scaffolds to bioabsorbable polymer platforms and biologically active surface modifications has redefined performance benchmarks. Modern bio-engineered stents increasingly rely on controlled drug-release kinetics, biodegradable polymer matrices, and endothelial-friendly surface engineering to reduce late inflammation and support vessel healing. These design improvements are not cosmetic; they directly address the clinical vulnerabilities that have historically limited long-term stent outcomes. Recent product milestones illustrate the direction of travel. Regulatory clearances and approvals for advanced everolimus-eluting platforms, bioabsorbable polymer systems, and complementary drug-coated balloon technologies have expanded the procedural toolkit for interventional cardiologists. At the same time, published long-term clinical data from flagship platforms have reinforced confidence in sustained vessel patency and reduced target lesion revascularization, strengthening the value proposition for bio-engineered designs over legacy alternatives.
Regulatory and reimbursement environments are equally influential in shaping adoption patterns. Because bio-engineered stents are regulated as Class III devices, market access depends on robust evidence packages that demonstrate safety and efficacy in reducing restenosis. This requirement favors companies with mature clinical research infrastructure and the ability to generate multi-year outcomes data. Reimbursement policy further determines how quickly hospitals can adopt new platforms. Payment structures for percutaneous coronary interventions establish per-procedure reimbursement ranges that influence budget allocation and procurement decisions. When reimbursement frameworks align with the cost profile of advanced stents, adoption accelerates; when they lag, hospitals may delay transitions or negotiate aggressively on pricing. The interaction between regulatory evidentiary demands and reimbursement economics creates a dual filter: innovation must be clinically credible and financially integrable to achieve scale.
Stent Grafts Market
Demand-side behavior is also shifting, driven by changing patient profiles and provider priorities. Aging populations and rising prevalence of coronary and peripheral vascular disease are expanding the addressable procedural base. At the same time, clinicians are placing greater emphasis on long-term outcomes rather than short-term procedural success alone. The decline of late thrombotic events and the desire for faster endothelialization have made bio-engineered platforms increasingly attractive in complex lesion subsets. Hospital procurement teams, meanwhile, are moving from volume-driven purchasing toward value-based evaluation, weighing total cost of care, complication rates, and inventory predictability. This shift rewards manufacturers that can offer consistent performance across diverse anatomies and provide data that supports downstream cost avoidance.
Supply chain and cost structure dynamics add another layer of strategic importance. The cost of medical-grade bioabsorbable polymers and specialized coating materials remains elevated due to stringent biocompatibility requirements and manufacturing precision. These input costs can create pricing rigidity, especially for premium platforms. At the same time, geopolitical and logistics pressures have reinforced the need for resilient sourcing and regional manufacturing redundancy. Companies that secure stable polymer supply, invest in scalable production, and optimize component sourcing can protect margins while offering more predictable pricing to health systems. For new entrants, the cost barrier is significant, but it also creates an opportunity for differentiated designs that achieve clinical parity with lower material complexity or more efficient manufacturing footprints.
Competitive Landscape and Leading Strategies
The competitive environment is defined by a concentrated group of established manufacturers, each pursuing differentiated clinical and commercial positioning. Medtronic has emphasized controlled drug-release technology through bioengineered platforms that combine durable delivery with polymer systems designed to support predictable healing. Its strategic emphasis on long-term clinical evidence, including sustained outcome data from global trials, reinforces confidence in durability and restenosis reduction. Boston Scientific has focused on bioabsorbable polymer engineering that aims to promote endothelialization while reducing long-term inflammation, complementing this approach with adjacent technologies such as drug-coated balloons that broaden the intervention portfolio. Abbott Laboratories has built a strong position around everolimus-eluting platforms designed for biocompatible healing and low thrombotic risk, with newer iterations aimed at improving deliverability and lesion coverage. Terumo Corporation has advanced bioengineered drug-eluting stents that pair sirolimus-based therapy with biodegradable polymer design, targeting a balance of efficacy and vascular compatibility.
These companies are not competing solely on device performance; they are competing on evidence ecosystems, procedural integration, and market access readiness. A clear differentiator among leaders is the ability to present a complete clinical narrative that spans premarket approval, post-market surveillance, and real-world adoption support. Regulatory milestones such as premarket approvals and international certifications serve as gating events that validate clinical claims and unlock procurement pathways. Equally important are commercial strategies that reduce friction for hospitals, including streamlined logistics, training support, and data-sharing models that help operators demonstrate outcomes within their own institutions. In a concentrated market, these operational capabilities can be as decisive as product specifications.
The broader market structure appears to be evolving along two parallel paths. On one hand, consolidation is likely to continue as larger manufacturers seek to expand portfolios, broaden geographic reach, and capture more of the total procedure value chain. On the other hand, there is room for targeted differentiation by companies that can address specific clinical niches or regional cost constraints without attempting to match premium platforms across every dimension. New entrants face steep barriers because of regulatory burden, reimbursement complexity, and the dominance of incumbents with established relationships and long-term data. However, specialized innovations in polymer design, surface engineering, or delivery systems can still create entry points if they solve a clearly defined clinical or economic problem. The market is therefore unlikely to become commoditized quickly; instead, it will reward platforms that can demonstrate credible long-term outcomes, cost predictability, and procedural versatility.
Future Trends and Commercial Implications
Over the next three to five years, one of the most significant trends will be the increasing emphasis on long-term vessel healing and late-event reduction as primary value metrics. As clinical data mature, purchasers and clinicians will likely evaluate bio-engineered stents less on immediate procedural success and more on durability, endothelial recovery, and the reduction of repeat interventions. Platforms that can document sustained outcomes across diverse patient populations and lesion types will gain preferential positioning in formulary decisions and procurement negotiations.
Cardiac Stent Market
A second trend will be the gradual expansion of bio-engineered stent use into broader peripheral vascular applications and more complex coronary anatomies. As operator confidence grows and delivery systems improve, the addressable market will extend beyond straightforward lesions into segments that historically relied on alternative interventions. This expansion creates opportunities for manufacturers that can adapt platform designs to greater flexibility, radial strength, and deliverability without compromising biocompatibility. It also opens the door for combination strategies, where stents and complementary devices are used in coordinated treatment pathways rather than as isolated product choices.
A third trend involves growing pressure to align innovation with healthcare cost containment. Hospitals will continue to demand transparent evidence of economic value, not just clinical superiority. This may drive more structured outcome reporting, health economics analyses, and risk-sharing procurement models. At the same time, reimbursement environments and regulatory expectations may evolve, creating uncertainty around timing and adoption pacing. Manufacturers that proactively integrate economic evidence with clinical data will be better positioned to navigate price negotiations and formulary inclusion. The principal risk is that cost pressure could slow the adoption of premium platforms if the perceived incremental benefit does not justify the price differential in specific market segments.
Strategic Actions for Decision-Makers
Manufacturers should prioritize evidence generation and market-access readiness as core strategic assets. Building multi-year clinical data, strengthening post-market surveillance capabilities, and aligning product roadmaps with reimbursement realities will be essential to preserving pricing power and competitive differentiation. Innovation should be focused on measurable clinical benefits and cost predictability, rather than incremental feature upgrades that do not translate into adoption advantage.
Investors should evaluate companies based on their ability to sustain long-term outcome credibility, manage material and supply chain costs, and expand into adjacent procedural categories without diluting execution focus. Platforms with strong regulatory momentum, clear reimbursement alignment, and supportive real-world evidence are better positioned to capture share through the forecast period. Portfolio breadth and procedural integration can also serve as indicators of resilience in a concentrated market.
Procurement leaders and hospital decision-makers should treat bio-engineered stent selection as a total-cost-of-care decision rather than a unit-price comparison. Evaluating platforms on long-term complication risk, inventory predictability, and operator support can yield better outcomes and reduce downstream spend. Ongoing access to detailed segmentation data, regional pricing dynamics, and competitive benchmarking can improve negotiation leverage and demand planning. For organizations seeking deeper visibility into submarket dynamics, detailed regional breakdowns, type- and application-level demand patterns, and customized strategic scenarios are available in the full PW Consulting market study.
PW Consulting
For detailed analysis of this topic, please visit the official page: Worldwide Bio-engineered Stent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


