



Global 9% Nickel Steel Plate Market to Hit $3.6B by 2032: Why LNG Storage Shift Drives 7.5% CAGR

Strategic Trends and Commercial Opportunities in the Worldwide 9% Nickel Steel Plate Market
Market Context and Core Challenges
The global market for 9% nickel steel plate has evolved into a structurally critical segment within the broader cryogenic and energy infrastructure supply chain. Over the historical period from 2020 to 2025, the market expanded from approximately $1.51 billion to $2.15 billion, reflecting sustained investment in liquefied natural gas (LNG) infrastructure and industrial cold-chain applications. Projections extending through 2032 indicate a continuation of this trajectory, with revenue expected to surpass $3.5 billion by the end of the forecast window. This growth path corresponds to a compound annual growth rate of roughly 7.5%, signaling a market that is out pacing broader steel segments and embedding itself deeper into long-cycle energy and industrial projects.
Despite the clear upward trajectory, the sector faces several structural friction points that decision-makers must navigate carefully. First, the reliance on nickel as the primary alloying element ties plate pricing and availability directly to a volatile commodity market. Nickel supply cycles, geopolitical trade dynamics, and competing demand from battery and stainless steel industries create periodic cost uncertainty for mill operators and downstream engineers. Second, the market exhibits pronounced regional concentration, with a handful of established heavy-plate producers in Europe and Asia controlling a significant share of high-quality cryogenic-grade output. This concentration restricts supply flexibility during peak project execution phases and raises the stakes for qualification timelines in new build programs. Third, regulatory and trade policy shifts are reshaping cross-border procurement strategies. Recent tariff reintroductions in key import markets have altered cost calculations for engineering, procurement, and construction firms, forcing earlier sourcing decisions and regional supply chain redesign.
These challenges do not diminish the market's long-term relevance; rather, they define the operational rules for competitive positioning. Organizations that treat 9% nickel plate procurement as a strategic variable rather than a simple materials purchase will be better positioned to manage cost volatility, secure mill capacity during bottleneck periods, and align sourcing with evolving code requirements and project phasing.
Key Drivers of Market Change
Technological Innovation and Metallurgical Substitution
Metallurgical advancement continues to reshape how engineers specify and deploy cryogenic-grade materials. Extended solidification control, controlled rolling and accelerated cooling, and vacuum treatment have improved the consistency of 9% nickel plates across wider thickness ranges and larger panel dimensions. At the same time, a notable innovation thread involves lower-nickel alternatives that aim to deliver equivalent fracture toughness at reduced alloy cost. Recent technical disclosures from leading producers emphasize TMCP-based steel plates with adjusted nickel content that approach the cryogenic performance of traditional 9% nickel grades while lowering raw material exposure. This direction matters because it expands the design space for tank and vessel engineers, potentially altering procurement specifications for new LNG storage projects and pressure vessel programs. For procurement teams, the practical implication is that material selection is no longer a binary choice between standard 9% nickel and cost-saving substitutes; it is becoming a spectrum where mechanical property guarantees, weldability, and total delivered cost must be evaluated together.
Policy and Regulatory Environment
Regulatory frameworks governing LNG containment and cryogenic service provide the baseline justification for 9% nickel plate demand. International code recognition of austenitic microstructures that retain fracture toughness at cryogenic temperatures has cemented the material's role in tank walls, fuel containment systems, and processing infrastructure. At the same time, trade policy is becoming an equally important driver of market behavior. The reinstatement of broad steel import duties in major markets has introduced a new layer of cost and sourcing complexity. Import-dependent projects now face higher landed costs and longer lead-time risk if mill capacity must be rerouted to alternative regions or if quotas and derivative provisions constrain eligible supply. For developers and EPC contractors, this regulatory shift elevates the importance of early mill engagement, localized qualification packages, and contingency planning for feedstock availability.
PW Consulting
Demand-Side Shifts Across LNG and Industrial Cryogenics
Demand for 9% nickel plate is anchored by LNG storage and transport infrastructure, but the application mix is diversifying. Large onshore LNG storage tanks remain a dominant consumption pathway, driven by terminal expansions, peak-shaving facilities, and regional energy security programs. Beyond storage, carrier vessels, fuel tank systems, and cryogenic pipelines and processing equipment contribute a growing share of requirements as LNG is integrated into power generation, industrial fuel switching, and maritime bunkering networks. On the industrial side, applications that require reliable performance at extremely low temperatures continue to pull specialty plate into pressure vessels and processing modules. The common thread across these demand streams is a preference for materials with documented impact toughness, predictable weld behavior, and certification documentation that satisfies classification societies and engineering standards bodies. This demand profile favors suppliers that can offer not only the plate itself but also traceability, inspection support, and application-specific technical guidance.
Supply Chain and Cost Structure Dynamics
Nickel feedstock dynamics sit at the center of the cost structure for 9% nickel plate production. Global nickel output is projected to reach approximately 2.5 million metric tons in 2026, and while this level suggests adequate baseline supply, the distribution of refined product, ore availability, and competing downstream demand create localized scarcity risks. Mills that operate integrated refining routes or secure long-term alloy supply arrangements hold a structural advantage in stabilizing plate pricing and delivery reliability. At the same time, logistics and regional tariffs affect total cost of ownership. A plate that appears competitive on a per-ton basis may become less attractive once freight, qualification lead times, and tariff exposure are factored into the project budget. The result is a market where cost competitiveness is increasingly defined by supply chain resilience, not just raw unit price.
Competitive Landscape and Leading Strategies
The 9% nickel steel plate market is characterized by a concentrated group of established heavy-plate manufacturers alongside a growing cohort of regional producers focused on LNG and cryogenic applications. European and Asian incumbents have built their positions on metallurgical expertise, large-format production capability, and documented performance in major LNG projects. Several of these firms produce plates across the thickness ranges and widths required for large tank fabrication, and they reinforce their market position with technical documentation that guarantees cryogenic impact properties and supports code compliance. This combination of material capability and application support creates a defensible advantage, especially for projects where structural integrity at extreme temperatures is non-negotiable.
Asian producers have expanded their relevance by aligning plate production with domestic and regional LNG build-outs, securing project-specific supply roles, and demonstrating quality systems that satisfy stringent cryogenic requirements. Chinese mills, in particular, have become embedded in project supply networks for major storage and vessel programs, leveraging scale, localized cost structures, and accreditation pathways recognized by classification societies. For some of these producers, the strategy is less about global brand visibility and more about reliable execution in project-critical supply slots. This model can be successful when paired with consistent metallurgical quality and responsive technical service.
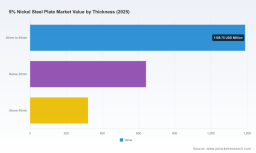
Differentiation within the competitive set increasingly rests on three dimensions. The first is grade and property assurance. Producers that publish guaranteed transverse impact performance, provide weldability guidance, and offer plate varieties tailored to specific fabrication requirements reduce uncertainty for engineers and fabricators. The second is format flexibility. The ability to supply plates in thicknesses up to and beyond 40 millimeters, with controlled width envelopes and specialized thin-gauge options for large-scale tanks, opens access to more demanding design configurations. The third is supply stability. In a market where qualification cycles and project execution timelines are long, mills that maintain documentation continuity, support material traceability, and avoid disruptive quality issues earn repeat participation in follow-on phases and sister projects.
The competitive landscape is also evolving through incremental substitution and selective entry. Lower-nickel, TMCP-based alternatives are creating pressure on traditional 9% nickel specifications in certain applications, prompting incumbents to defend their positions with enhanced property documentation and cost-optimized processing routes. At the same time, specialized mills that focus on cryogenic accreditation and narrow application niches are finding room to serve regional demand and project-specific requirements. The market is therefore not converging into a single dominant model; it is fragmenting by application expertise, service depth, and regional supply strategy. Organizations evaluating supplier relationships should assess not only production capacity but also the supplier's ability to navigate code expectations, deliver consistent property guarantees, and provide the technical partnership that complex cryogenic projects require.
Ship Plate Market
Forward Outlook: Trends That Will Shape the Next Three to Five Years
The most consequential trend over the next several years will be the continued negotiation between material performance and cost efficiency. As LNG infrastructure expands and industrial cryogenic applications grow, designers and procurement teams will increasingly weigh guaranteed toughness against alloy cost. This will accelerate the adoption of lower-nickel and thermomechanically processed alternatives in select applications, while sustained demand for proven 9% nickel grades will keep the core segment robust. The net effect is a more nuanced specification environment where material selection is project-specific and value-engineered rather than standardized across all cryogenic uses.
Ferronickel Market
A second trend is the reinforcement of regional supply strategies in response to trade policy and project timing risk. As import duties and logistical constraints alter cross-border cost equations, developers and fabricators are likely to place greater emphasis on regional mill partnerships, localized qualification packages, and staged procurement that aligns with project phasing. This shift benefits suppliers with credible regional capacity and documentation readiness, while challenging those that depend heavily on long-distance shipment without sufficient cost and timeline buffers.
A third trend concerns the growing importance of technical service and certification support as a competitive differentiator. In cryogenic applications, the plate is only one element of a broader system that must satisfy design codes, inspection protocols, and classification requirements. Suppliers that bundle material supply with engineering support, impact property guarantees, and project-specific documentation will capture more influence over specification decisions. The commercial opportunity here is clear: value in this market is increasingly created through reduced execution risk and faster qualification cycles, not merely through tonnage pricing.
These trends carry inherent uncertainty. Nickel price volatility, changes in trade policy scope, and the pace of lower-nickel substitution can all shift the balance of advantage in either direction. Organizations that monitor these variables continuously and maintain flexible specification and sourcing strategies will be better equipped to convert market change into competitive leverage rather than cost exposure.
Strategic Considerations for Decision-Makers
For mill operators and material producers, the priority is to strengthen differentiation through documented property assurance and format flexibility. Investing in technical documentation that supports code compliance, providing weldability and fabrication guidance, and maintaining consistent quality across thick and thin gauges will reinforce repeat participation in large LNG and cryogenic programs. Producers should also evaluate how lower-nickel or TMCP-based options fit into their portfolios, positioning them as targeted alternatives rather than blanket replacements, so that engineering teams can select the right grade for each application.
For investors and strategic planners, the value lies in assessing exposure to nickel cost cycles, regional supply concentration, and policy-driven sourcing shifts. Portfolio decisions should account for the growing importance of application-specific technical capability and the risk that trade policy can alter the economics of cross-border plate supply. Companies with credible cryogenic documentation, established project supply relationships, and regional footprint resilience offer a more stable path through the market's structural volatility.
For procurement and engineering teams, early engagement with qualified suppliers is essential. Specification decisions should integrate total cost of ownership, including tariff exposure, logistics, qualification lead time, and inspection support, rather than relying on base plate pricing alone. Building contingency plans for mill capacity constraints and maintaining awareness of evolving code expectations will reduce schedule risk in large storage and carrier projects. For organizations seeking detailed segmentation data, regional and thickness-level breakdowns, and tailored sourcing or investment recommendations, the full PW Consulting industry study provides the structured detail needed to support those decisions.
For detailed analysis of this topic, please visit the official page: Worldwide 9% Nickel Steel Plate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


