



Worldwide Formaldehyde Testing Instrument Market: The 5.85% CAGR Reality

Strategic Horizons: Navigating the Global Formaldehyde Testing Instrument Market
Market Landscape and Critical Challenges
The global market for formaldehyde testing instruments has entered a phase of steady, structurally supported expansion. Valued at approximately USD 387.8 million in 2020, the market has consistently climbed, crossing the USD 500 million threshold by 2025 and positioning itself to reach roughly USD 767.0 million by 2032. This trajectory reflects a compound annual growth rate of 5.85% across the forecast horizon. The growth is not merely cyclical; it is anchored in tightening regulatory expectations, widespread industrial adoption of indoor air quality monitoring, and the gradual replacement of legacy detection methods with faster, more integrated analytical systems.
PW Consulting
Despite the favorable momentum, the industry faces several structural tensions. The first is the calibration-compliance paradox. As regulatory bodies across multiple jurisdictions update emission and exposure standards, testing protocols are becoming more prescriptive. Instruments that once met general workplace monitoring requirements now need to demonstrate alignment with specific chamber methods, micro-chamber protocols, and third-party certification frameworks. Manufacturers and end users alike must navigate a landscape where compliance is no longer a one-time validation but an ongoing operational requirement.
The second challenge lies in the convergence of detection sensitivity and deployment practicality. Many high-precision analytical systems deliver the accuracy required for laboratory and regulatory-grade testing, yet their size, cost, and operational complexity limit field adoption. Conversely, portable handheld devices offer flexibility and speed, but users in industrial and healthcare settings increasingly demand quantifiable assurance that low-level readings remain reliable over extended monitoring periods. Bridging this gap without sacrificing accuracy or ease of use remains a persistent engineering and commercial hurdle.
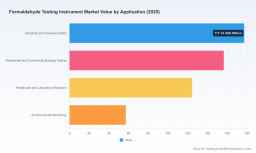
A third inflection point is the fragmentation of application requirements. Testing needs differ sharply between continuous emissions monitoring at manufacturing sites, spot-checking for indoor air quality in buildings, and controlled laboratory emissions testing for composite materials. Each segment carries distinct performance expectations, calibration rhythms, and reporting obligations. Companies that attempt to serve all segments with a single product architecture often find themselves stretched across competing engineering priorities and compliance demands.
Key Challenges at a Glance
- Aligning instrument performance with evolving, region-specific regulatory test methods
- Balancing laboratory-grade accuracy with the portability and cost constraints of field deployment
- Designing product strategies that address divergent requirements across industrial, building, healthcare, and environmental use cases
Key Drivers Shaping Market Evolution
Several interconnected forces are accelerating demand for formaldehyde testing instruments and reshaping how they are positioned in the market. Understanding these dynamics is essential for any organization evaluating product roadmaps, procurement strategies, or investment exposure.
Paraformaldehyde Market
Technology Innovation and Analytical Precision
The most visible driver is the continued refinement of detection technologies that reduce measurement latency while preserving analytical rigor. Traditional methods often relied on chemical sampling, extended chamber exposure, or laboratory transfer steps that delayed results and increased operational burden. Newer approaches are compressing that timeline. For example, infrared laser spectroscopy has enabled rapid micro-chamber testing that can deliver formaldehyde readings in roughly 15 minutes without chemical reagents, creating an attractive option for laboratories seeking faster throughput and lower consumable costs. At the same time, advancements in sensor modularity and multi-gas platform design are making it easier for safety teams to add formaldehyde monitoring to existing field instruments rather than managing entirely separate devices.
This technological shift matters because it expands the addressable use cases for testing instruments. Faster results support more frequent quality control cycles in materials manufacturing. Modular sensors simplify exposure monitoring in facilities where multiple gases must be tracked simultaneously. And improved low-level detection capabilities give building and environmental professionals greater confidence in indoor air assessments. The practical effect is a market in which performance is no longer measured solely by accuracy, but also by turnaround time, workflow integration, and total cost of ownership.
Regulatory and Standards Environment
Regulatory activity continues to be one of the strongest structural drivers. Updates to emission standards and testing protocols for composite wood products, along with broader occupational exposure requirements, are compelling manufacturers, testing laboratories, and compliance teams to revisit their measurement methods. Recent proposals illustrate this direction. In February 2026, a regulatory proposal sought to update voluntary consensus standards for formaldehyde emission standards in composite wood products, incorporating new test methods including an updated international standard as an alternative quality control test method. Alongside that, broader updates to formaldehyde standards for composite wood products referenced the incorporation of revised ASTM and ISO test methods and introduced a new small-scale quality control chamber test method.
These developments create demand on multiple fronts. Manufacturers of wood-based and composite materials must ensure their testing workflows align with the latest recognized methods. Independent testing laboratories need instruments and chambers that can satisfy updated protocols and third-party certification requirements. And workplace safety teams must continue to meet occupational exposure monitoring expectations, including established accuracy thresholds for time-weighted average sampling. As standards evolve, the instruments that can most easily adapt to new methods gain a meaningful commercial advantage.
Demand-Side Shifts in Indoor Air Quality and Industrial Safety
Beyond formal regulatory mandates, demand is being shaped by changing expectations around air quality, worker safety, and consumer awareness. Public and professional attention to indoor environmental conditions has increased across both residential and commercial settings. Building operators, facility managers, and property developers are placing greater emphasis on documented air quality performance as part of broader sustainability, health, and occupant wellbeing goals. That emphasis is translating into more routine formaldehyde monitoring, especially in spaces where composite materials, adhesives, furnishings, or finishes may contribute to volatile organic compound levels.
In parallel, industrial and chemical safety programs are becoming more proactive. Rather than treating gas detection as a reactive compliance exercise, many organizations are integrating formaldehyde monitoring into broader exposure management systems. Portable multi-gas monitors with interchangeable formaldehyde sensors have gained relevance in this context because they allow safety teams to maintain a common operational platform while still addressing substance-specific risks. The result is a growing preference for instruments that can support both immediate hazard detection and longer-term exposure documentation.
Supply Chain and Cost Structure Considerations
The cost and availability of materials, sensors, and calibration support are also influencing market behavior. While formaldehyde testing instruments do not require the same scale of raw material inputs as heavy industrial equipment, they do depend on precision components, specialized sensor elements, and reliable consumables or calibration services. Organizations that can stabilize supply, localize support, and reduce recurring operational costs are better positioned to compete, particularly when buyers are comparing instruments on lifecycle economics rather than initial purchase price alone.
This dynamic is especially relevant for buyers who operate across multiple sites or regions. An instrument that offers strong specification performance may still lose out if calibration turnaround, replacement part availability, or technical support introduces unacceptable downtime. As a result, suppliers that build dependable service networks and transparent cost structures around their instruments are increasingly differentiating themselves in a market where functional specifications alone no longer guarantee adoption.
Competitive Landscape and Leading Strategies
The competitive environment in the formaldehyde testing instrument market is defined by a mix of established industrial manufacturers, specialized instrument developers, and companies with strong compliance-aligned product portfolios. The market remains moderately concentrated, with the top three players accounting for roughly 32.4% of total revenue and the top five reaching approximately 46.85%. That level of concentration suggests enough fragmentation to allow differentiated entrants, but also enough leadership presence to shape buyer expectations around reliability, compliance, and service.
Distinct Strategic Positions
Participation in the market is not uniform; leading companies have adopted different positioning strategies based on their technical strengths and target applications.
- 3M has built a recognizable presence in passive diffusive formaldehyde monitoring for personal and area sampling. Its monitor designs are aligned with established workplace accuracy expectations, making them relevant for healthcare, laboratory, and industrial exposure monitoring where standardized sampling and compliance documentation matter.
- Aero-Laser GmbH focuses on high-precision continuous measurement, offering analyzers suited to emissions monitoring, indoor air quality assessment, and laboratory or research applications. This positions the company closer to users who prioritize measurement continuity and analytical control over field portability.
- Fagus-GreCon has emphasized laboratory and inline formaldehyde emission testing from wood-based and other materials, with systems that align to widely recognized emission standards. Its product updates illustrate a push toward faster, chemical-free testing methods, reinforcing a strategy centered on throughput, protocol alignment, and materials testing compatibility.
- GrayWolf Sensing Solutions targets indoor air quality and environmental monitoring with advanced meters and probes designed for low-level formaldehyde detection and data logging. This places the company in a segment where usability, portability, and long-duration monitoring are particularly important.
- Honeywell, through its RAE Systems brand , offers portable multi-gas monitors that support interchangeable formaldehyde sensors. Its strength lies in integrating formaldehyde detection into broader multi-substance safety platforms, appealing to industrial users who value operational consistency across different hazard scenarios.
- Markes International develops sampling equipment such as microchamber samplers for dynamic headspace collection, often used with thermal desorption workflows. Its relevance stems from materials and automotive-related emissions testing, where method compliance and sample integrity are central.
- PPM Technology Ltd produces both portable and fixed formaldehyde monitors, targeting indoor air quality and toxic gas detection across varied environments. Its product breadth supports customers who need flexible deployment options rather than a single instrument class.
- RKI Instruments, Inc. provides gas detection instruments that include formaldehyde-capable models for safety monitoring in industrial and laboratory settings, reinforcing a practical, safety-oriented value proposition.
How the Landscape Is Evolving
Several patterns are shaping the future shape of competition. One is differentiation by measurement format. Some companies are strengthening their position in continuous, high-precision analytical systems, while others are expanding portable, field-ready portfolios. This division is likely to persist because the underlying customer needs differ: laboratory and compliance testing demand repeatability and protocol alignment, whereas field safety and building assessments value mobility, speed, and ease of use.
Another trend is the growing importance of method compatibility as a competitive asset. Instruments that can accommodate recognized chamber methods, micro-chamber testing, and updated standards without requiring extensive workflow changes are better placed to retain and expand their customer base. In a regulatory environment where test methods are being revisited and refined, flexibility is becoming as valuable as raw performance.
Market convergence is also emerging in the multi-gas safety segment, where formaldehyde capability is increasingly treated as one function within a broader exposure monitoring strategy. At the same time, divergence remains strong among organizations that specialize in materials emission testing or indoor air quality diagnostics. New entrants are most likely to succeed if they address a clearly defined gap, such as faster laboratory screening, more robust low-level field detection, or better integration between portable measurement and compliance documentation.
Smart Formaldehyde Detector Market
Forward Outlook: Strategic Trends for the Next Three to Five Years
Looking ahead, the market is likely to be shaped by a combination of regulatory refinement, technology adoption, and shifting procurement priorities. Three trends stand out.
1. Faster, More Integrated Testing Workflows Will Become a Baseline Expectation
The move toward rapid micro-chamber methods and chemical-free analysis is not a passing upgrade cycle; it reflects a broader expectation that testing should support faster decision-making. Laboratories and quality control teams increasingly want instruments that reduce waiting time without compromising method recognition or data quality. Over the next few years, products that combine rapid screening with established compliance alignment will have a stronger competitive position, particularly in materials manufacturing and third-party testing environments.
2. Compliance Adaptability Will Separate Mature Suppliers from Narrow Product Players
As test methods are revised and new alternative protocols are incorporated into updated standards, instruments and workflows that can adapt with minimal disruption will gain advantage. Buyers are likely to favor solutions that can support both current requirements and anticipated method changes, rather than tools locked into a single legacy approach. This favors suppliers that invest in method flexibility, documentation support, and service capabilities alongside hardware performance.
3. Indoor Air Quality and Exposure Management Will Expand the Commercial Base
Formaldehyde testing is increasingly embedded in broader indoor environmental quality programs and industrial exposure management systems. That broader context creates opportunities for instruments that can support routine monitoring, recordkeeping, and multi-substance safety workflows. It also increases the importance of usability and data handling, since the business value of testing often depends on how easily results can be interpreted, shared, and acted upon across facilities or projects.
Risks and Uncertainties
These opportunities are accompanied by real uncertainties. Regulatory timing can shift as standards undergo review, and method updates may require revalidation of existing workflows. Economic pressure on facility budgets could slow discretionary testing purchases, especially in segments where compliance is not the primary driver. In addition, the market may see variability in how quickly new rapid-testing approaches are accepted across different regions and application areas. Organizations should therefore plan for a landscape where demand growth is strong but not uniform, and where method alignment remains more important than any single hardware feature.
Actionable Guidance for Decision Makers
For organizations operating in or adjacent to this market, the strategic question is less about whether demand will grow and more about where to position capabilities and resources. A few practical priorities emerge.
For Manufacturers and Product Developers
- Prioritize method flexibility in product design so instruments can adapt to updated chamber, micro-chamber, and consensus standards without forcing customers to redesign their workflows.
- Invest in recurring value elements such as calibration support, consumables availability, and service responsiveness; in a moderately concentrated market, these often determine repeat purchases and long-term loyalty.
- Decide clearly whether to compete in high-precision continuous analysis, portable safety monitoring, or materials emission testing, rather than diluting resources across all three without a distinct positioning advantage.
For Investors
- Focus on companies whose revenue logic is tied to compliance adoption, faster testing throughput, or multi-gas integration, since these themes are more likely to support sustained demand than single-feature differentiation alone.
- Watch for consolidation signals among specialized testing suppliers and laboratories, especially where method compatibility and service networks create barriers for smaller players.
- Assess geographic exposure carefully; demand drivers differ by region, and product competitiveness often depends on local standards, support infrastructure, and procurement practices.
For Procurement and Operations Leaders
- Evaluate instruments on lifecycle performance, including method alignment, calibration turnaround, and documentation support, rather than initial specification sheets alone.
- Align purchasing decisions with upcoming compliance updates to avoid premature deployment of tools that may need replacement or revalidation as standards evolve.
- Where multi-site monitoring is required, favor platforms that can standardize workflows across locations while still meeting the specific detection needs of each environment.
The formaldehyde testing instrument market is moving from a compliance-driven niche toward a more diversified, performance-sensitive commercial space. That shift rewards organizations that can connect technical capability with regulatory adaptability, operational practicality, and clear application focus. For decision makers who need detailed segmentation data, company-level benchmarking, or tailored scenario planning, the full research report provides a deeper set of figures and structured analysis to support those decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Formaldehyde Testing Instrument Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


