



Honeycomb Optical Breadboards Market: Why the 6.25% CAGR Reshapes Optics

Strategic Shifts and Commercial Opportunities in the Global Honeycomb Optical Breadboard Market
Market Overview and Critical Challenges
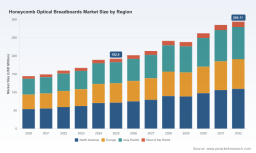
The global market for honeycomb optical breadboards has transitioned from a niche instrumentation sector to a strategically important component within precision photonics and laser systems. With a market valuation exceeding USD 190 million in 2025 and a projected compound annual growth rate of 6.25% through 2032, the segment reflects steady expansion driven by the proliferation of advanced optical assemblies. Historical revenue trajectories from 2020 through 2025 demonstrate consistent upward momentum, with particularly sharp acceleration observed in the 2023–2024 window. Forward projections indicate that the market will breach the 300 million threshold by the end of the forecast period, underscoring the growing integration of honeycomb structural components into high-value optical architectures.
Despite this encouraging trajectory, the industry faces several structural inflection points that demand strategic attention. First, the standardization-versus-customization tension continues to complicate product roadmaps. As optical setups grow more complex, end users increasingly request tailored damping profiles, mounting geometries, and surface finishes, yet manufacturers must balance these demands against the cost efficiencies of standardized production lines. Second, raw material volatility and supply chain fragmentation present persistent margin pressures. The structural performance of optical breadboards depends heavily on the quality and consistency of honeycomb cores and top-skin materials, making procurement strategies highly sensitive to global commodity fluctuations and regional manufacturing capacity constraints. Third, the competitive field is characterized by significant consolidation, with the top three players commanding over 58% of total revenue and the top five accounting for more than 72%. This concentration creates both advantages for established players with deep engineering resources and barriers for mid-sized manufacturers seeking to scale without differentiated capabilities.
These challenges are not insurmountable, but they reframe how executives should evaluate growth. The market is no longer expanding uniformly across all customer segments; instead, value creation is shifting toward firms that can align structural engineering expertise with application-specific performance requirements while navigating supply chain and pricing dynamics efficiently.
Key Demand Drivers Shaping Market Evolution
Several interconnected forces are accelerating demand and reshaping procurement priorities across the honeycomb optical breadboard ecosystem. Understanding these drivers provides a clearer lens for assessing where commercial value will concentrate over the next several years.
Honeycomb Sandwich Material Market
Technical performance requirements in precision optics remain the most direct catalyst. Modern photonics, laser interferometry, and quantum measurement systems demand exceptionally low vibration transmission, high flatness tolerances, and consistent modal damping across operational environments. Honeycomb architectures inherently deliver a favorable stiffness-to-weight ratio combined with structural damping characteristics that solid-plate alternatives struggle to match without substantial mass penalties. This engineering reality has made honeycomb breadboards the default structural foundation for optical tables, beam delivery assemblies, and calibration platforms where micro-vibration isolation directly impacts signal integrity. As laser wavelengths shorten and optical configurations become more densely packed, the tolerance for mechanical instability narrows, reinforcing the structural necessity of high-performance honeycomb cores.
Policy and research funding environments are indirectly but powerfully shaping procurement cycles. Government-backed initiatives in semiconductor equipment development, advanced manufacturing, and life sciences instrumentation continue to channel capital into laboratory infrastructure and pilot production lines. Public research institutions and private R&D centers depend on stable, vibration-isolated platforms for repeatable experimental outcomes, which sustains baseline demand from academic and scientific organizations. At the same time, regulatory emphasis on measurement traceability and environmental stability in testing laboratories encourages procurement of components with documented damping performance and dimensional consistency, elevating quality assurance from a compliance checkbox to a competitive differentiator.
Demand-side behavior in enterprise and industrial settings is shifting toward modular, reconfigurable optical infrastructure. Rather than committing to fixed installations, engineering teams increasingly favor breadboards and table extensions that can be rearranged, upgraded, or integrated into larger setups as project requirements evolve. This modular preference is particularly pronounced in aerospace testbeds and research facilities, where experimental configurations change frequently and downtime for reconfiguration must be minimized. The result is a preference for breadboard designs that support standardized mounting patterns, consistent skin thicknesses, and compatible interface hardware, reducing integration friction across multiple procurement cycles.
Worldwide Honeycomb Board Market
Supply chain and cost structure dynamics are exerting dual pressure on manufacturers and buyers. On the material side, core composition choices influence both performance and total cost of ownership. Aluminum honeycomb structures have secured a substantial share of broader honeycomb core material consumption due to their balance of weight efficiency, machinability, and cost, while certain polymer-based cores are gaining traction in adjacent applications where moisture resistance and recyclability offer lifecycle advantages. For optical breadboard producers, this means material strategy is no longer purely about structural specification; it also involves forecasting commodity availability, qualifying alternative suppliers, and designing product families that can absorb material substitution without compromising flatness or damping targets. On the manufacturing side, regional production footprints and lead-time variability are becoming more prominent in sourcing decisions, especially for customers running time-sensitive development programs or operating in locations where logistics delays could stall project milestones.
PW Consulting
Together, these drivers indicate that growth will be earned through application alignment, material strategy discipline, and the ability to deliver modular performance without sacrificing structural integrity.
Competitive Landscape and Strategic Positioning
The competitive environment for honeycomb optical breadboards is defined by a handful of established manufacturers with deep optical engineering heritage, alongside a broader set of regional and specialty producers that compete on cost, customization, or specific material configurations. The market's revenue concentration underscores the advantage held by firms that can combine consistent quality, recognized brand trust, and comprehensive application support.
Leading players are pursuing differentiation through several complementary strategies. Some emphasize monolithic or hybrid honeycomb construction paired with advanced damping features, positioning their breadboards as high-stiffness platforms for demanding photonics and laser applications. Others focus on series breadth, offering multiple core materials, skin finishes, and mounting hole patterns to cover a wide range of laboratory and industrial configurations. A third strategic vector involves ferromagnetic or magnetic top-skin options that simplify component alignment and extension, particularly for optical table ecosystems where breadboards serve as modular add-ons rather than standalone workstations. These approaches reflect a broader realization that winning in this market depends less on selling a commodity plate and more on delivering a predictable mechanical environment for sensitive optical assemblies.
Recent product and commercial activity reinforces the importance of portfolio discipline and market visibility. One manufacturer retired an industrial-grade breadboard model and directed customers toward a scientific-grade replacement, signaling a deliberate shift toward higher-performance, application-aligned offerings rather than maintaining broad but undifferentiated catalog depth. Another major participant used a premier photonics conference to showcase hybrid honeycomb breadboards alongside clean-top optical tables, reinforcing the message that breadboard selection should be evaluated within the context of complete optical infrastructure rather than as isolated hardware. These moves illustrate a maturing competitive dynamic in which product rationalization and ecosystem positioning are becoming as important as raw specification leadership.
The landscape is also showing signs of both consolidation and targeted expansion. Larger incumbents with global distribution and technical support networks are well placed to defend share in price-sensitive segments while competing on performance in high-margin applications. Smaller and regional manufacturers, meanwhile, are creating space by specializing in specific core material variants, offering faster custom quoting, or serving local markets where logistics and relationship-based selling matter more than global brand recognition. At the same time, new entrants face a steep credibility curve because optical engineers prioritize documented flatness, vibration behavior, and long-term supplier reliability. As a result, the most plausible contour of market evolution is continued leadership by established names, with incremental pressure from specialists that can demonstrate clear performance or service differentiation in defined application niches.
Forward Outlook: Trends and Commercial Implications
Looking ahead to the 2026–2031 period, three trends are likely to shape how value is created and captured in this market.
- Performance-tiered portfolio segmentation will deepen. Buyers will increasingly separate procurement into two streams: standardized solutions for routine laboratory and educational setups, and engineered solutions for semiconductor equipment, advanced life sciences instrumentation, and aerospace testing. Manufacturers that can articulate distinct value propositions across these tiers, rather than stretching a single product line across all use cases, will be better positioned to protect margins and serve application-specific expectations.
- Modular and customized integration will become a baseline expectation. Demand for breadboards that interoperate cleanly with optical tables, damping legs, and mounting accessories will keep rising, especially where research infrastructure and aerospace prototyping require frequent reconfiguration. Suppliers that invest in compatible interface standards, clear extension roadmaps, and predictable lead times will reduce friction for buyers and build repeat procurement relationships.
- Material and sourcing strategy will move from background concern to strategic priority. As core material choices influence both cost and structural behavior, manufacturers and buyers will pay closer attention to supply continuity, substitution pathways, and qualification cycles. Firms that can demonstrate reliable material availability and consistent performance across core and skin combinations will gain negotiation leverage, while those exposed to single-source dependencies or abrupt material transitions may face margin and delivery risk.
These trends create opportunities for suppliers that can align product architecture with real-world integration needs, and for buyers that can structure sourcing around performance tiers rather than uniform specification comparisons. At the same time, uncertainty remains. Shifts in research funding cycles, changes in semiconductor equipment investment pacing, and potential disruptions in specialty material availability could alter demand velocity in specific regions or application verticals. Competitive intensity may also rise if larger players aggressively rationalize portfolios or if regional manufacturers successfully scale differentiated offerings. The market is therefore likely to reward organizations that monitor these signals continuously and adjust product, sourcing, and partnership decisions before shifts become obvious in aggregate revenue data.
Actionable Recommendations for Decision-Makers
For optical component manufacturers: Prioritize product portfolio clarity. Map offerings explicitly to performance tiers and application contexts, and retire or reposition catalog items that create confusion without contributing to differentiation. Invest in documentation that communicates damping behavior, flatness consistency, and compatibility with common mounting and extension hardware, since these attributes increasingly influence repeat procurement more than headline specifications alone.
For investors and strategic buyers: Evaluate targets and partners based on engineering credibility, material sourcing resilience, and the ability to serve high-value application segments rather than sheer catalog breadth. In a concentrated market, durable advantage tends to come from application adjacency, technical support quality, and integration-oriented product design. Scrutinize whether a company's roadmap emphasizes modular interoperability and performance-tiered segmentation, as these characteristics are more likely to support sustained relevance than undifferentiated volume plays.
For procurement and engineering leaders: Move evaluation beyond unit price and base specification sheets. Establish internal criteria for vibration isolation requirements, mounting compatibility, and expected reconfiguration frequency, then align supplier selection with those operational realities. Where project timelines are tight or application environments are demanding, prioritize suppliers with transparent performance documentation and consistent lead-time performance over those competing solely on initial cost. For organizations seeking detailed segmentation data and supplier-level comparisons to support these decisions, a comprehensive market study can provide the structured detail needed to refine sourcing strategy and investment prioritization.
For detailed analysis of this topic, please visit the official page: Worldwide Honeycomb Optical Breadboards Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


