



Worldwide Wafer Geometry System Market: 8.5% CAGR Ignites a New Competitive Playbook

Navigating the Global Wafer Geometry System Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
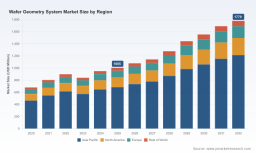
The worldwide wafer geometry system market has demonstrated sustained expansion over the past half-decade, evolving from a niche metrology segment into a critical enabler of advanced semiconductor manufacturing. Valued at approximately 680.45 million USD in 2020, the market climbed to 949.23 million USD by 2024 and reached an estimated 1005.0 million USD in 2025. Forward projections indicate the sector will expand to 1779.0 million USD by 2032, reflecting a compound annual growth rate of 8.5 percent across the 2026 to 2032 forecast period. This trajectory underscores a structural shift where precision geometry measurement is no longer a secondary quality check but a foundational requirement for device performance, yield optimization, and process control.
The Asia Pacific region continues to represent the dominant share of global market activity, driven by dense manufacturing clusters, aggressive capacity expansion, and rapid adoption of advanced node technologies. North America and Europe maintain substantial but comparatively smaller footprints, often concentrated in high-value metrology innovations, specialized substrate markets, and integrated equipment ecosystems. The market remains highly consolidated, with the top three participants capturing roughly 82.4 percent of total revenue and the top five holding approximately 91.15 percent. Such concentration reflects the capital-intensive nature of metrology hardware, the importance of customer qualification cycles, and the technical barriers associated with sub-nanometer measurement accuracy across diverse substrates.
Despite the favorable growth outlook, the industry faces several interconnected challenges that are reshaping competitive dynamics. First, the transition toward three-dimensional device architectures, wider-bandgap semiconductors, and increasingly complex patterned wafers places unprecedented demands on metrology precision. Geometry systems must now resolve nanoscale topography, stress-induced warping, and multi-layer deformation without compromising throughput. Traditional measurement paradigms are struggling to keep pace with device complexity, forcing vendors to rethink sensor architectures, inspection speeds, and data integration capabilities.
Second, the market is navigating pronounced supply chain and input cost volatility. Fluctuations in raw material availability, combined with tightening export controls on critical minerals and semiconductor manufacturing equipment, are disrupting procurement timelines and increasing operational uncertainty. Restrictions affecting materials such as gallium, germanium, graphite, rare earths, tungsten, antimony, bismuth, and magnesium have introduced cost pressure and sourcing complexity across substrates and ancillary components. At the same time, regulatory adjustments extending certain equipment authorizations and refining direct product rules have created a moving compliance landscape that equipment manufacturers must continuously monitor.
Third, demand-side dynamics are exhibiting cyclical tension. Global silicon wafer shipments experienced a modest contraction before rebounding, signaling that capacity planning and procurement strategies remain sensitive to macroeconomic conditions, inventory cycles, and regional investment timing. For wafer geometry system suppliers, this volatility complicates forecasting, lengthens sales cycles, and requires more flexible commercial models. Companies that can align their product roadmaps with substrate economics, regional investment patterns, and evolving quality requirements will be better positioned to convert market growth into durable revenue streams.
Key Drivers Shaping Market Expansion
Technological innovation remains the most powerful engine behind market growth, particularly as device manufacturers push into advanced logic, high-density memory, and power semiconductor segments. Geometry metrology is increasingly integrated into process flows where thickness uniformity, bow, warp, total thickness variation, and nanotopography directly influence lithographic focus budgets, etch uniformity, and packaging reliability. The shift from bare wafer inspection to patterned wafer geometry analysis reflects a broader industry recognition that shape and stress characteristics must be monitored throughout fabrication, not just at initial substrate receipt. Vendors investing in dual-sided measurement, high-speed wavefront or capacitive sensing, and automated handling are gaining traction because they reduce variability and enable in-line feedback loops.
Policy and regulatory developments are simultaneously redefining market boundaries and access patterns. Extensions of temporary general licenses and authorizations for semiconductor manufacturing equipment items have provided short-to-medium-term continuity for cross-border equipment deployment, but they also signal a sustained emphasis on controlled technology transfer. Refinements to foreign-produced direct product rules and targeted controls on specific equipment categories have added compliance complexity for multinational vendors and customers alike. For participants in the wafer geometry space, these dynamics create both friction and opportunity. Companies that can offer regionally adaptable configurations, maintain robust qualification documentation, and support customers through evolving export control requirements are finding it easier to secure long-term engagements in fragmented markets.
Demand-side behavior is shifting as chipmakers and substrate producers realign capacity around technological priorities rather than pure volume growth. Advanced packaging, silicon carbide and gallium nitride applications, and high-bandwidth memory development are driving demand for specialized geometry monitoring on non-silicon and patterned substrates. In parallel, manufacturers are placing greater emphasis on yield enhancement and defect reduction, viewing metrology as a cost-saving lever rather than a compliance expense. This mindset change supports higher adoption of automated geometry systems that can deliver consistent measurements across large lots, integrate with process control software, and reduce reliance on offline laboratory checks.
Supply chain and cost structure changes are reinforcing the need for measurement flexibility and platform modularity. Variability in substrate availability, shifting wafer shipment volumes, and regional cost differentials are encouraging vendors to design systems that can accommodate multiple substrate types, diameters, and process stages without extensive retooling. Capacitive sensing approaches, for example, have gained attention because they allow non-contact measurement of thickness, total thickness variation, bow, warp, flatness, resistivity, and film stress across sliced, lapped, and etched substrates. Such versatility helps equipment owners maximize utilization across product mix changes and reduces the financial risk associated with substrate cycle swings.
Recent product introductions illustrate how vendors are responding to these drivers. The launch of a new wafer geometry monitoring product line using capacitive sensing for thickness, total thickness variation, bow, warp, flatness, resistivity, and film stress on semiconductor substrates demonstrates a clear emphasis on multi-parameter, non-contact measurement for a broad range of substrate conditions. This type of platform addresses a practical pain point: customers want a single measurement architecture that can support multiple process steps and substrate states while maintaining accuracy and throughput. In a market where qualification cycles are long and integration requirements are stringent, offerings that reduce footprint complexity and expand parameter coverage tend to resonate strongly with fabrication and substrate engineering teams.
Competitive Landscape and Leading Strategies
The market’s concentrated structure has fostered a competitive environment where incumbents rely on measurement accuracy, platform breadth, and deep customer integration, while challengers differentiate through speed, novel sensing modalities, and targeted substrate segments. Leading participants have built their positions around metrology systems capable of handling both bare and patterned wafers across diverse materials, including silicon, silicon carbide, and gallium nitride. Their value proposition often extends beyond hardware to include software-driven data interpretation, automation compatibility, and process-specific calibration support. In advanced memory and logic manufacturing, geometry systems that can characterize shape, stress, warp, and nanotopography are increasingly evaluated on their ability to fit into high-volume 생산라인 environments without disrupting cycle time.
Strategic differentiation is evident across several dimensions. Some vendors emphasize established capacitive gauge platforms and manual-to-automated system options that serve both semiconductor and photovoltaic process flows, appealing to customers seeking reliability, broad parameter coverage, and incremental automation upgrades. Others focus on high-speed wavefront phase imaging for blank and patterned 300mm wafers, targeting applications where rapid topography, warp, bow, and in-plane displacement measurement can support tighter process control. A third group concentrates on precision bare wafer geometry metrology and sorting systems designed for wafer manufacturers who need consistent thickness, total thickness variation, bow, and warp measurements across high-throughput production lines. Meanwhile, electron beam-based verification systems have found a niche in advanced NAND, DRAM, and logic manufacturing, where pattern and geometry inspection demand high-accuracy validation and detailed structural feedback.
These divergent approaches reflect a broader market evolution toward segmentation by substrate type, device architecture, and process stage. Rather than competing solely on vertical integration, companies are increasingly building specialized capabilities that align with particular customer workflows. This specialization can create defensible positions in complex applications where measurement physics, substrate handling, and data integration must be carefully matched to fabrication requirements. At the same time, the presence of established multinational players and regionally anchored suppliers contributes to a landscape where qualification trust, service networks, and long-term support matter as much as instrument specifications.
Consolidation and selective new entry are shaping the next phase of competition. The high concentration among top players suggests that scale advantages in R&D, global support, and customer onboarding remain important. Yet the market also leaves room for focused entrants that bring differentiated measurement methods, stronger software ecosystems, or superior handling of emerging substrates. Customers are likely to continue favoring suppliers that can demonstrate repeatable accuracy, reduce integration risk, and evolve with changing device roadmaps. For vendors, the strategic imperative is to balance platform breadth with application depth, ensuring that systems can adapt to new geometry challenges without forcing customers into costly process redesigns.
International trade dynamics and regional investment patterns are further influencing competitive positioning. As equipment authorizations and export control refinements continue to evolve, suppliers with flexible deployment models and strong regional compliance capabilities may gain an advantage in navigating cross-border procurement. In parallel, customers are increasingly evaluating total cost of ownership through the lens of measurement reliability, throughput, and downstream yield impact, which rewards vendors that can translate technical performance into clear operational benefits.
Future Outlook and Emerging Opportunities
Over the next three to five years, the wafer geometry system market is likely to be shaped by three interrelated trends. First, multi-parameter metrology will become the default expectation rather than a premium feature. As device complexity rises, customers will increasingly seek systems that capture geometry, stress, and material-related parameters within a unified workflow, reducing measurement handoffs and improving process feedback. This shift favors platform architectures that can scale across bare and patterned wafers while maintaining high accuracy and throughput.
Second, automated integration and data connectivity will separate high-growth deployments from legacy installations. Geometry systems that interface smoothly with factory automation, support inline decision-making, and provide structured data for process control will command stronger demand. The commercial opportunity lies not only in instrument sales but in enabling yield optimization, reducing re-measurement cycles, and supporting advanced packaging and wide-bandgap manufacturing workflows. Vendors that can demonstrate measurable operational impact will be better positioned to expand within existing customer bases and enter new facilities.
Third, regional capacity shifts and regulatory evolution will continue to influence market access and product configuration. Fluctuations in substrate volumes, alongside policy adjustments affecting equipment deployment, will reward suppliers that can offer adaptable solutions and maintain consistent qualification support across markets. At the same time, export controls on critical minerals and equipment-related authorizations introduce uncertainty around sourcing and deployment timing, making resilience and flexible supply strategies increasingly valuable.
These trends carry tangible commercial implications, but they also introduce risks. Rapid technology changes can shorten product lifecycles, while regulatory uncertainty may delay procurement decisions. Substrate cycle volatility can pressure demand in the short term, and highly concentrated competition can compress margins for suppliers that lack differentiated capabilities or strong service networks. Companies that monitor these signals closely and align their investment and product strategies accordingly will be better prepared to capture growth while managing downside exposure.
Strategic Guidance for Decision-Makers
For wafer and semiconductor manufacturers, the priority is to treat geometry metrology as an integrated process enabler rather than an isolated inspection step. Evaluating systems against actual workflow requirements, substrate mix, and automation compatibility can reveal opportunities to improve yield consistency and reduce downstream variability. Manufacturers should also build flexibility into metrology planning, ensuring that selected platforms can accommodate new materials, patterned structures, and evolving device architectures without major re-qualification overhead.
For investors and strategic planners, the market’s steady growth trajectory and concentrated structure suggest that differentiation in sensing technology, software integration, and substrate specialization will be key value drivers. Tracking product introductions, regional capacity announcements, and regulatory updates can provide early signals about where demand will intensify and which application segments will command premium attention. Companies with adaptable platforms and strong qualification support are likely to capture disproportionate benefit from capacity expansion in advanced memory, logic, and wide-bandgap segments.
For procurement and technology leaders, the focus should be on total cost of ownership and long-term support reliability. Multi-parameter capability, measurement speed, and integration readiness often matter more than headline specifications, especially when production environments require consistent performance across varied substrate states. Engaging early with suppliers on roadmap alignment and qualification requirements can shorten deployment timelines and reduce operational risk.
Detailed segmentation data, company-level benchmarking, and region-specific outlooks can help decision-makers refine these priorities and translate market dynamics into actionable plans. For a fuller view of market sizing, application and type splits, regional nuances, and competitive benchmarks, the complete PW Consulting report provides expanded datasets and tailored recommendations for specific operating contexts.
PW Consulting
Worldwide Wafer Thickness Measuring System Market
Worldwide Overlay Metrology System Market
For detailed analysis of this topic, please visit the official page: Worldwide Wafer Geometry System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


