



Uncooled Infrared Detector Housing Market: Why 8.11% CAGR Reshapes Competition

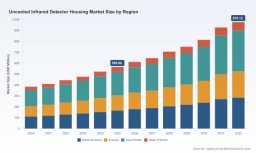
Navigating the Global Uncooled Infrared Detector Housing Market: Strategic Shifts and Commercial Pathways
Market Landscape and Core Challenges
The worldwide market for uncooled infrared detector housings has entered a phase of sustained expansion, driven by the broader adoption of thermal imaging across defense, industrial, and commercial sectors. Revenue has grown consistently from the early 2020s through the base year of 2025, with the trajectory pointing toward a robust forecast window extending to 2032. At the heart of this growth is the continuous reduction in size, weight, power, and cost (SWaP-C) requirements, which has made uncooled microbolometer technology viable for an expanding range of applications. The sector's compound annual growth rate reflects both organic demand pull and structural improvements in packaging and integration methodologies, positioning housings not merely as protective enclosures but as critical enablers of performance, reliability, and miniaturization.
Worldwide Microbolometer Infrared Detector Market
Despite the positive momentum, the industry confronts a set of interconnected challenges that will shape competitive outcomes over the next several years. The first revolves around the tension between performance thresholds and supply chain accessibility. As applications demand lower noise-equivalent temperature difference (NETD) values and higher resolution formats, packaging architectures must preserve thermal stability, mechanical resilience, and signal integrity while accommodating tighter dimensional constraints. This creates a technical bottleneck for manufacturers that cannot simultaneously optimize vacuum integrity, material compatibility, and high-volume yield. The second challenge stems from regulatory and export control dynamics. Performance-based restrictions on certain detector classes have introduced additional qualification cycles and constrained the flow of advanced components across borders, forcing suppliers to navigate divergent compliance regimes depending on end-use and destination markets. The third challenge is the pressure on cost structures amid intensifying competition. As wafer-level and ceramic packaging approaches mature, incumbents and new entrants alike must reconcile the economics of high-precision manufacturing with the expectation of lower unit costs, particularly in price-sensitive commercial and consumer-adjacent segments.
These pressures are not merely operational; they redefine how value is captured in the housing segment. Suppliers that treat packaging as a commodity risk margin erosion, while those that integrate housings with detector design, thermal management, and application-specific qualification can command premium positioning. The market's concentration among leading players underscores the importance of scale, technical know-how, and long-term qualification relationships. Yet the same concentration also signals opportunity for differentiated entrants that can address regional demand nuances, leverage localized production, or offer packaging solutions that reduce integration friction for system integrators. For decision-makers, the central question is no longer whether the market is growing, but which packaging pathways, qualification strategies, and geographic footprints will determine competitiveness in an environment where performance, cost, and compliance must be balanced simultaneously.
Key Drivers Reshaping the Market
Technology Innovation and Packaging Architecture Evolution
The most consequential driver is the ongoing evolution of packaging technologies that directly determine detector performance, durability, and integration cost. Ceramic packaging has emerged as a preferred pathway for many uncooled infrared detectors because it combines mechanical robustness with design flexibility, enabling miniaturization without sacrificing reliability. Optimized ceramic structures have demonstrated the ability to reduce material volume and overall footprint while preserving mechanical integrity under demanding vibration and shock conditions, making them suitable for mobile, airborne, and field-deployed systems. At the same time, wafer-level vacuum packaging is gaining traction for high-volume production of entry-level and mid-tier thermal imaging modules. By moving vacuum encapsulation closer to the wafer process, suppliers can significantly lower assembly complexity and integration cost, supporting mass deployment in applications where SWaP-C is the dominant selection criterion. The coexistence of ceramic and wafer-level approaches reflects a broader segmentation logic: high-performance and mission-critical use cases continue to favor robust ceramic carriers, while volume-driven commercial applications increasingly adopt wafer-level formats to achieve cost thresholds that unlock new market pockets.
Policy, Export Controls, and Compliance as Strategic Variables
Regulatory and export control environments are increasingly shaping technology roadmaps and supply chain decisions. Performance-based thresholds on detector sensitivity and related specifications have introduced compliance considerations into packaging qualification, influencing which architectures can be supplied to specific end-use markets and geographies. For manufacturers, this means that packaging strategies must account not only for technical performance but also for the documentation, traceability, and qualification pathways required in defense, homeland security, and certain industrial deployments. These dynamics can lengthen qualification cycles and narrow the pool of eligible suppliers for advanced applications, reinforcing the value of established relationships and proven reliability records. At the same time, the evolving policy landscape encourages regional diversification, as system integrators seek to de-risk supply by qualifying multiple packaging sources and maintaining flexibility across different compliance regimes.
Demand-Side Shifts Across Application Verticals
Demand is expanding beyond traditional defense and security applications into industrial thermography, advanced driver-assistance systems, and a growing set of commercial imaging solutions. Automotive ADAS is a particularly influential driver, as thermal imaging is increasingly evaluated for low-visibility detection and pedestrian recognition in safety-critical contexts. This application trajectory pushes packaging requirements toward compact form factors, thermal stability under vehicular conditions, and cost profiles compatible with volume production. Industrial and thermography applications, meanwhile, reward housings that support consistent performance across varied environmental conditions and that can be integrated into portable or fixed inspection systems with minimal re-engineering. In security and surveillance, the trend favors smaller, lower-power modules that can be embedded into networked camera platforms, drones, and mobile monitoring solutions. Together, these demand shifts are broadening the base of end-users and forcing packaging suppliers to develop application-tailored variants rather than relying on a single standardized offering.
Supply Chain and Cost Structure Dynamics
Cost structure pressures are intensifying as multiple manufacturing hubs expand capabilities in metal, ceramic, and wafer-level packaging. In Asia-Pacific, domestic production lines for vanadium oxide-based uncooled detectors across multiple packaging formats have supported more competitive pricing and shorter lead times for regional system integrators. This localization trend is reinforced by the desire to reduce exposure to cross-border constraints and to align supply with regional demand growth. However, cost competitiveness must be balanced against reliability and qualification expectations, particularly where applications require proven mechanical and thermal performance. Suppliers that can demonstrate high-yield manufacturing, consistent vacuum integrity, and robust test protocols are better positioned to protect margins even as unit prices face downward pressure. The broader effect is a market in which scale, process control, and application-specific validation are becoming the primary levers for commercial success, rather than packaging alone as a discrete component sale.
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a mix of established defense-linked suppliers, regional specialists, and packaging-focused manufacturers that serve the broader uncooled detector ecosystem. Leonardo DRS stands out for its work in leadless chip carrier and wafer-level vacuum packaging for uncooled vanadium oxide long-wave infrared microbolometers, supporting high-resolution formats for both defense and commercial thermal imaging. Its strategic positioning emphasizes proven packaging reliability and the ability to scale sophisticated architectures for demanding applications, including ongoing development toward higher-resolution focal plane arrays. This approach reflects a broader pattern among top-tier suppliers: differentiation comes from integrating packaging expertise with detector performance roadmaps and from maintaining qualification depth in mission-critical use cases.
Global Sensor Technology, associated with Wuhan Guide Infrared, illustrates a volume-and-flexibility strategy. By offering metal, ceramic, and wafer-level packages across multiple resolutions, the company targets high-volume production with an emphasis on SWaP-C optimization and integration into thermal modules. Its recent introduction of ceramic-packaged uncooled infrared detectors using mainstream technology highlights a push toward improved reliability and cost performance, reinforcing the idea that packaging choices are increasingly tied to application economics. For commercial and industrial customers, this type of multi-format capability can reduce integration risk and provide a path to cost-down without abandoning performance requirements.
European and Israeli suppliers contribute additional differentiation through high-performance formats and compact pixel pitch technologies. Lynred has expanded its uncooled microbolometer portfolio with ceramic packaging options for aerospace, defense, and industrial applications, and its move toward smaller pixel pitch architectures signals a focus on resolution and portability for advanced thermal imaging. SCD complements this landscape with low SWaP-C ceramic-packaged detectors aimed at military, homeland security, and industrial deployments, emphasizing form factors and performance attributes suited to specialized end-use scenarios. These players illustrate how regional technology strengths and application histories shape packaging strategies, with a shared emphasis on reliability, performance consistency, and the ability to support higher-resolution or smaller-format trends.
In South Korea, i3system manufactures uncooled infrared detectors for commercial and military thermal imaging, including formats designed for security, surveillance, and night vision systems. Its footprint demonstrates how regional champions can serve both domestic demand and export markets by aligning packaging and detector capabilities with application-driven requirements. Meanwhile, specialized packaging suppliers such as Hebei Sinopack and Hefei Shengda focus on ceramic and electronic packaging components tailored to uncooled infrared focal plane detectors, supporting night vision, security, and monitoring applications. Their role highlights an important structural dynamic: the housing and packaging segment is not served only by detector manufacturers, but also by suppliers whose core competency lies in precision packaging, thermal management, and mechanical integration. Kyocera adds another dimension with ceramic packages and lids for optical and infrared sensors, including surface-mount designs that replace traditional can-style packages. Its emphasis on miniaturization and thermal management reflects an industry-wide shift toward form factors that simplify integration and support higher packaging density.
Taken together, the competitive landscape is evolving along three axes. First, consolidation of capability is occurring among suppliers that can combine detector know-how, vacuum packaging expertise, and qualification depth, especially for higher-resolution and defense-adjacent applications. Second, segmentation is intensifying as ceramic, wafer-level, and metal packaging each find distinct footholds depending on performance, volume, and cost priorities. Third, new entry opportunities exist for companies that can deliver packaging solutions reducing integration friction, supporting regional supply resilience, or enabling cost thresholds for emerging commercial applications. For system integrators and end-product manufacturers, the implication is clear: supplier selection is increasingly a strategic decision that affects not only component cost, but also qualification timelines, application fit, and long-term flexibility across performance tiers and geographies.
Future Trends and Commercial Opportunities
Over the next three to five years, one of the most important trends will be the continued migration toward smaller pixel pitches and higher-resolution formats in uncooled microbolometer families. As packaging architectures adapt to these tighter geometries, housings will need to preserve thermal stability, vacuum integrity, and mechanical resilience at reduced scales. This trend creates commercial opportunity for suppliers that can deliver compact, high-reliability packages suitable for portable and high-resolution thermal imaging, where size and performance are jointly decisive. It also raises the bar for process control, because yield and consistency become more sensitive as formats shrink and packing density increases.
A second trend is the widening of volume-driven commercial applications, particularly where SWaP-C thresholds open new adoption pathways. Wafer-level vacuum packaging and optimized ceramic designs are well positioned to support high-volume production and lower integration costs, making thermal imaging more accessible for security, industrial, and certain consumer-adjacent use cases. The commercial opportunity here lies in packaging solutions that standardize interfaces, simplify module integration, and reduce qualification burden for platform manufacturers seeking to deploy thermal imaging at scale. Suppliers that can provide repeatable, cost-effective housings with predictable performance will be better positioned to capture demand in these expanding segments.
A third trend is the growing importance of regional supply resilience and compliance-aware sourcing. As export controls and performance-based restrictions influence which components can be supplied to specific markets, system integrators and OEMs will increasingly pursue multi-source strategies and regional qualification pathways. This creates opportunity for packaging suppliers with localized production, flexible compliance documentation, and the ability to support different end-use regimes. At the same time, uncertainty remains. Regulatory shifts, raw material and process cost volatility, and the risk of quality or yield challenges in advanced packaging formats can all affect timing and margin. The companies that navigate this environment most effectively will be those that treat packaging not as a static enclosure, but as a strategic interface between detector performance, application economics, and supply chain risk management.
Strategic Recommendations for Decision-Makers
For packaging and detector manufacturers, the priority is to align packaging roadmaps with the performance-versus-cost curve that different applications demand. This means investing in process maturity for both ceramic and wafer-level pathways, strengthening vacuum integrity and mechanical validation, and developing application-specific variants that reduce integration effort for system builders. Companies should also evaluate where miniaturization, pixel pitch reductions, and higher-resolution formats create openings for differentiated housings, and where volume economics require a more standardized, cost-optimized approach. Building qualification depth and documentation rigor will be especially valuable where compliance cycles and performance thresholds shape purchasing decisions.
Infrared Detector Market
For investors, the most promising signals lie in suppliers that combine scalable manufacturing with clear application focus and compliance-aware supply strategies. Attention should be paid to firms that can demonstrate yield consistency, multi-format capability, and the ability to serve both specialized and volume markets without compromising reliability. Regional production momentum, particularly where domestic lines support cost-competitive supply while maintaining qualification relevance, is another important indicator of resilience. In a market where concentration is meaningful but segmentation is deepening, capital allocation should favor businesses with defensible process expertise and clear pathways to integration into high-growth application verticals.
For procurement and strategic planning teams, supplier selection should extend beyond unit price to include integration complexity, qualification timelines, mechanical and thermal reliability, and the ability to support future format changes. Diversifying across packaging types and geographies can reduce exposure to regulatory and supply disruptions, while standardizing interfaces where possible can lower total system cost. Engaging early with packaging suppliers on application requirements, test protocols, and anticipated resolution or form-factor evolution can shorten integration cycles and improve long-term flexibility. For organizations that need detailed segmentation data, regional revenue splits, and tailored sourcing or investment scenarios, the full market research report provides the deeper quantitative foundation and customized context required to translate these strategic directions into operational decisions.
PW Consulting
For detailed analysis of this topic, please visit the official page: Worldwide Uncooled Infrared Detector Housing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


