



Worldwide Heavy-Duty Wear Protection Materials Market: Asia Pacific Dominance and 5.85% Growth Redefining 2032

Strategic Shifts and Commercial Opportunities in the Global Heavy-Duty Wear Protection Materials Market
Market Status and Core Challenges
The global heavy-duty wear protection materials market has demonstrated resilient growth over the past five years, expanding from approximately $1.38 billion in 2020 to an estimated $1.85 billion in 2025. This trajectory reflects a compound annual growth rate of 5.85 percent through 2032, with revenue projections reaching $2.75 billion by the end of the forecast horizon. Such expansion underscores a structural shift: wear protection is no longer treated as a routine maintenance commodity but as a strategic operational lever that directly impacts asset longevity, downtime reduction, and total cost of ownership across heavy industries.
Beneath these headline figures, several structural tensions are reshaping how organizations evaluate and deploy wear-resistant solutions. First, the market is experiencing a pronounced performance-versus-cost optimization challenge. Operators in mining, cement, and power generation face mounting pressure to extend maintenance intervals while avoiding excessive upfront capital expenditure. This has accelerated demand for engineered hybrid materials that balance abrasion resistance, impact tolerance, and installability, forcing procurement teams to evaluate lifecycle economics rather than unit pricing alone.
Wear Resistant Steel Market
Second, raw material volatility and supply chain fragmentation continue to test margin stability. Advanced ceramics, high-alloy steels, and engineered polymers rely on energy-intensive processing and geographically concentrated feedstock networks. Fluctuations in energy costs, logistics bottlenecks, and regional manufacturing capacity constraints have introduced unpredictability into lead times and pricing structures. Companies that depend on single-source sourcing or rigid specification frameworks are encountering disproportionate exposure to these disruptions.
Third, the regulatory and sustainability agenda is altering material selection criteria. Environmental evaluations of cast wear protection alloys increasingly compare traditional cobalt-, nickel-, and iron-based formulations against lower-impact iron aluminide and alternative composite approaches. While performance requirements in extreme abrasion and high-temperature environments remain non-negotiable, procurement specifications are gradually incorporating lifecycle carbon considerations, recycling pathways, and compliance documentation into vendor qualification processes. These converging pressures are pushing the market past a transition point where incremental material upgrades are being replaced by systematic engineering and sourcing redesigns.
Key Drivers Shaping Market Dynamics
Technological innovation remains the most visible catalyst for market evolution. Material science advancements have shifted the performance ceiling for abrasion-resistant solutions, particularly in ceramic and composite segments. Alumina and silicon carbide continue to serve as primary feedstocks for advanced ceramics deployed in heavy-duty linings, delivering exceptional hardness and thermal stability in high-wear environments. Simultaneously, engineered polymer systems, including polyurethane-based liners and ceramic-filled epoxy coatings, have expanded the solution envelope for applications where spray-applied repair, conformability, and rapid reinstatement are critical. The result is a broader toolkit that enables engineers to match material architecture to specific wear mechanisms rather than applying uniform protective layers across dissimilar operating conditions.
PW Consulting
Policy and regulatory developments are reinforcing this technical diversification. Environmental scrutiny around alloy composition, energy-intensive manufacturing, and end-of-life material handling is influencing both product design and procurement standards. Industry evaluations increasingly compare conventional hardfacing alloys with sustainable iron aluminide alternatives, especially where regulatory reporting, emissions tracking, and responsible sourcing requirements are tightening. This does not eliminate high-performance alloys from consideration, but it encourages specification teams to document environmental impact alongside mechanical performance, gradually shifting vendor selection toward suppliers with transparent material credentials and validated sustainability pathways.
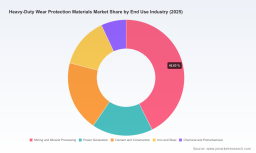
Demand-side behavior is changing as well. Operators are prioritizing predictive maintenance and condition-based replacement strategies over reactive repairs. In mining and mineral processing, cement and construction, and power generation, equipment downtime carries steep production penalties, making wear protection a direct contributor to operational continuity. This mindset favors materials and installation methods that reduce intervention frequency, simplify field repair, and integrate with monitoring programs. Companies are also demanding more consistent performance data, accelerated testing results, and application-specific validation rather than relying solely on generic laboratory benchmarks.
Supply chain and cost structure shifts are amplifying these demand-side expectations. Regionalization of manufacturing, nearshoring of service capabilities, and greater emphasis on inventory resilience are reshaping how wear protection products reach end users. Lead-time reliability, localized technical support, and adaptable product formats are becoming competitive differentiators alongside raw material pricing. At the same time, the need to maintain high wear resistance in steel, cement, and power plant environments has sustained strong demand for materials that can withstand severe abrasion without frequent replacement. Organizations that can combine material performance with responsive supply and installation support are capturing disproportionate share in applications where downtime costs dominate procurement decisions.
Competitive Landscape and Leading Strategies
The competitive landscape is defined by a concentration of specialized material suppliers and industrial solution providers, with the top three players accounting for roughly a third of total market revenue and the top five representing just under half. This structure reflects a market where technical credibility, application-specific engineering, and installed-base relationships matter as much as scale. Leading organizations are competing on differentiated value propositions rather than on product commoditization alone.
Several strategic archetypes are emerging among incumbent players. One group emphasizes advanced ceramic and refractory expertise, positioning high-hardness alumina, silicon carbide, and zirconia-toughened formulations as the default choice for extreme abrasion and thermal stress. These suppliers typically focus on engineered linings, custom shapes, and stringent quality control to serve demanding sectors such as mining, cement, and power generation. Their advantage lies in material science depth, repeatable performance in severe environments, and the ability to tailor formulations to specific wear profiles.
A second archetype centers on composite, coating, and hardfacing solutions designed for repair, retrofit, and rapid field application. Polyurethane liners, chrome carbide overlay plates, ceramic-filled epoxy systems, and hardfacing alloys address applications where installability, impact resistance, and on-site reinstatement are prioritized over monolithic ceramic performance. Companies in this segment often compete through application engineering, field service coverage, and the ability to extend equipment life without full component replacement. Their differentiation comes from bridging the gap between laboratory-grade material performance and practical operational deployment.
A third strategic orientation integrates wear protection into broader equipment ecosystems. The strongest players combine proprietary liner technologies with equipment design, wear monitoring guidance, and maintenance planning. By embedding wear solutions into chutes, hoppers, mills, and conveying systems, they create switching costs and long-term service relationships. This model is particularly effective in mining and mineral processing, where wear patterns are predictable enough to support engineered upgrades that reduce recurring replacement cycles.
Wear Plate Market
Market evolution is moving toward selective consolidation and capability expansion. Larger industrial suppliers are acquiring or partnering with specialized material formulators to broaden their application coverage and geographic reach. At the same time, smaller firms with niche formulations, regional service footprints, or proprietary installation methods continue to compete by serving high-value applications where customization outweighs scale advantages. New entrants are most likely to succeed where they bring genuine material innovation, validated field data, or digitally enabled service models that shorten diagnostic and replacement cycles. The overall trend is fragmentation at the application level combined with consolidation at the strategic level, as buyers increasingly prefer partners who can deliver consistent performance across multiple assets and sites.
Future Trend Forecasts
Over the next three to five years, one defining trend will be the acceleration of hybrid and engineered composite wear systems. Monolithic solutions will remain necessary for the most extreme environments, but many applications will shift toward layered or blended architectures that combine ceramic hardness, polymer toughness, and steel reinforcement where appropriate. This approach enables more precise matching to abrasion, impact, and thermal conditions while reducing installation complexity and enabling partial repairs rather than full component swaps. Commercial opportunity lies with suppliers that can standardize modular system designs, provide clear performance comparison frameworks, and support faster field reinstatement.
A second trend will be the growing integration of wear protection decisions into lifecycle and sustainability planning. Procurement and engineering teams are expected to weigh material composition, manufacturing energy intensity, repairability, and end-of-life handling alongside traditional performance metrics. This creates openings for vendors that can supply lower-impact alloy alternatives, recyclable composite formats, or coatings that extend service life with reduced material input. The risk is that sustainability requirements may outpace standardized testing and reporting norms, creating uneven compliance burdens for suppliers operating across multiple jurisdictions. Companies that move early to document environmental performance and align specifications with operational realities will be better positioned to navigate evolving expectations.
A third trend is the shift toward predictive wear management and service-integrated offerings. As condition monitoring, sensor data, and maintenance analytics become more accessible, wear protection will increasingly be specified as part of a broader uptime strategy rather than as a standalone material purchase. Suppliers that combine durable materials with installation expertise, replacement forecasting, and site-specific wear mapping will capture stronger customer retention. The principal uncertainty is the pace at which smaller operators adopt data-driven maintenance practices and whether labor constraints and skill gaps limit the speed of more advanced wear management deployments.
Strategic Recommendations for Decision Makers
Manufacturers and material suppliers should prioritize application-specific validation and lifecycle-oriented messaging. Investing in field data, comparative performance documentation, and modular system designs will help differentiate offerings in a market where buyers are scrutinizing total cost of ownership rather than unit price. Expanding regional service capability and technical support can also reduce exposure to supply chain volatility while strengthening customer retention.
Investors should look for participants with defensible technical positioning, diversified end-use exposure, and the ability to integrate material performance with service or equipment ecosystems. Companies that can navigate raw material constraints, incorporate lower-impact material options without compromising performance, and capture recurring maintenance demand are likely to deliver more resilient growth than those competing solely on commodity pricing.
Procurement and operations leaders should evaluate wear protection suppliers based on installed performance, repairability, and responsiveness rather than catalog specifications alone. Establishing clear wear mechanism profiles for critical assets, standardizing qualification criteria that include environmental and maintenance considerations, and building relationships with suppliers capable of supporting predictive replacement cycles can materially reduce unplanned downtime. For organizations seeking deeper segmentation data, regional demand patterns, competitive benchmarking, and tailored sourcing or investment scenarios, accessing a comprehensive market study provides the granularity needed to convert these strategic themes into executable decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Heavy-Duty Wear Protection Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


