



Worldwide Low Vision Devices Market: Home Care Leads the $1.1B Growth Trajectory

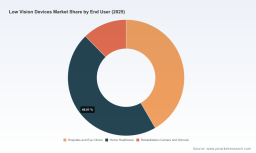
Navigating the Global Low Vision Devices Market: Strategic Trends and Commercial Opportunities
Market Landscape and Core Challenges
The worldwide market for low vision devices has entered a phase of sustained expansion, driven by demographic shifts and rapid advancements in assistive technology. Valued at approximately 685.5 million USD in 2025, the market has demonstrated consistent growth over the past five years and is projected to reach 1,115.2 million USD by 2032, reflecting a compound annual growth rate of 7.2 percent. This trajectory signals more than incremental demand; it indicates a structural transformation in how vision impairment is managed across clinical, home, and rehabilitation settings. As the global population ages and chronic conditions affecting visual acuity become more prevalent, the commercial relevance of low vision solutions continues to rise across both developed and emerging economies.
Despite this favorable headline trajectory, the industry operates within a landscape of persistent structural challenges. The first challenge lies in reconciling clinical prescription pathways with real-world adoption barriers. Many low vision devices meaningfully improve daily functioning, yet end users often face fragmented access to specialized fitting, training, and follow-up care. The second challenge centers on reimbursement architecture. Public and private health programs frequently cover rehabilitation services and assistive technology instruction, but direct device procurement remains inconsistently covered. This mismatch can slow purchase cycles, shift cost burden toward patients, and complicate forecasting for manufacturers. The third challenge is fragmentation within the product ecosystem. Optical aids, electronic video magnifiers, software-driven applications, and wearable systems serve overlapping clinical needs, yet user experience, compatibility, and service expectations vary significantly across categories and channels.
The market is also undergoing a credibility test as technology claims accelerate faster than reimbursement structures and clinical integration models. Devices that deliver clearer performance benefits are entering the field, but adoption depends on more than hardware capability. It requires clinician confidence, caregiver education, and durable support ecosystems. For commercial stakeholders, the implication is clear: success will depend less on isolated product launches and more on how effectively companies reduce friction across prescription, training, reimbursement navigation, and long-term usability.
Key Demand Drivers Shaping the Market
Technological innovation is the most visible force reshaping the low vision market. Electronic video magnifiers and AI-enabled wearables are no longer competing solely on magnification strength; they are increasingly differentiating through contrast optimization, text recognition, voice interaction, and portability. Head-mounted and handheld systems are closing the gap between clinical functionality and everyday convenience, allowing users to move beyond stationary reading tasks into navigation, workplace use, and independent living. The rise of software and application-based support has also broadened the addressable use case set, enabling integration with mobile platforms, remote configuration, and personalized visual profiles. In practical terms, this means device value propositions are shifting from magnification alone to functional independence, which expands adoption potential beyond traditional eye care channels.
Policy and regulatory dynamics are shaping the pace and confidence of innovation. Device classifications under medical device frameworks create structured pathways for many electronic and optical aids, while certain lower-risk optical magnifiers remain exempt from premarket notification requirements. This regulatory stratification matters commercially because it influences time-to-market, documentation burden, and the ability to scale across jurisdictions. At the same time, growing attention to accessibility standards and vision rehabilitation support is reinforcing the legitimacy of low vision technology as a healthcare priority rather than a niche assistive category. The increasing visibility of breakthrough designations and clinical trial activity for advanced visual restoration and augmentation approaches further underscores how seriously the innovation pipeline is being taken by regulators and investors.
Demand-side behavior is evolving as clinical awareness and user expectations change simultaneously. Eye care professionals are increasingly prescribing low vision technology alongside rehabilitation services, particularly when patients face progressive conditions or functional limitations that affect reading, mobility, and work. At the same time, end users are seeking devices that fit seamlessly into daily routines rather than requiring specialized setups or constant assistance. Home healthcare environments are playing a growing role in this shift, as patients and caregivers prioritize tools that can be used independently, maintained easily, and adapted to changing visual needs. This behavioral change favors solutions that combine ease of use with demonstrable functional gains, especially when supported by training and follow-up guidance.
Supply chain and cost structure factors are introducing both pressure and strategic differentiation. Components supporting high-resolution displays, sensing, battery efficiency, and AI processing have become more central to product performance, which increases sensitivity to sourcing stability, quality control, and manufacturing complexity. At the same time, the cost of delivering device-supported rehabilitation has become a critical commercial variable. When device pricing, service expectations, and reimbursement uncertainty combine, manufacturers that offer stronger service models, clearer clinical value narratives, and adaptable product tiers can gain an advantage in procurement discussions. In this environment, cost efficiency is not simply a margin issue; it is a market-access issue.
Competitive Landscape and Leading Strategies
The competitive field in low vision devices is broad, active, and increasingly differentiated by technology orientation and go-to-market style. HumanWare has built a strong reputation around electronic video magnifiers and portable assistive devices designed for reading and daily independence, reflecting a focus on practical usability and sustained user support. Eschenbach Optik GmbH represents the high-precision optical tradition, emphasizing magnifiers, telescopic devices, and illuminated hand and stand magnifiers for professional and everyday use. Vispero, through its VFO Group, offers a broader low vision portfolio that includes CCTV and video magnifiers alongside a range of optical and electronic aids, an approach that allows it to address multiple use cases within a single ecosystem. Enhanced Vision concentrates on electronic video magnifiers with features such as text-to-speech and high-contrast imaging, positioning itself around rehabilitation-oriented functionality. Optelec develops portable and desktop video magnifiers and electronic aids, supporting both low vision and broader vision support applications.
The landscape also includes companies advancing more immersive or intelligent device forms. OrCam Technologies has pushed into AI-powered wearable devices that convert visual information into audio feedback, giving users real-time text reading and object and face recognition capabilities. This direction reflects a broader shift from passive magnification toward active visual assistance. eSight Corp. has focused on electronic eyewear and head-mounted systems that enhance functional vision through advanced imaging, appealing to users seeking hands-free and mobility-friendly solutions. Zoomax Technology produces a range of portable, handheld, and desktop video magnifiers with AI integration and tablet-based systems, illustrating how regional manufacturing strength can align with feature-rich product development. Other contributors, including LVI Low Vision International, Aumed Group Corp., Ocutech, Inc., ZEISS, IrisVision Global, and HIMS Inc., extend the competitive base across optical specialization, bioptic and telescopic design, filter and contrast-control optics, headset-based magnification with voice and OCR capabilities, and broader assistive technology offerings.
Across this set of players, strategic differentiation is emerging around four dimensions. The first is product architecture, where manufacturers choose between optical precision, electronic magnification, wearable augmentation, or software-enabled support. The second is user experience, where portability, intuitive controls, training requirements, and real-world task coverage increasingly influence purchase decisions. The third is regulatory and reimbursement positioning, where companies that proactively align with classification pathways and prescription workflows can reduce friction in clinical adoption. The fourth is ecosystem readiness, where service, fitting support, and follow-up usability become competitive assets rather than secondary operations.
Night Vision Devices Market
The market structure is evolving along two complementary paths. Consolidation is becoming more attractive for players seeking broader portfolios, stronger distribution, and improved ability to serve end users across care settings. Simultaneously, the field remains open to new entrants that bring fresh technology approaches, particularly in wearable AI, intelligent image processing, and integrated digital support. This combination of consolidation pressure and innovation-driven entry suggests that competitive advantage will increasingly depend on how well companies combine technical capability with practical clinical and consumer adoption strategies.
Future Trends and Strategic Outlook
Over the next three to five years, one of the clearest trends will be the continued migration from standalone magnification hardware toward integrated, intelligent assistance. Devices will likely become more adaptive, more connected, and more capable of supporting daily functions beyond reading, including object identification, orientation support, and digital workflow interaction. This trend expands the commercial opportunity beyond traditional low vision segments into broader accessibility-oriented use cases, especially where usability and independence are prioritized.
A second trend will be increasing pressure on reimbursement and access pathways to catch up with product innovation. As devices become more clinically meaningful and more technologically advanced, stakeholders will likely push harder for clearer coverage logic, stronger rehabilitation integration, and better alignment between prescribed services and device purchase models. Companies that invest early in evidence generation, clinician education, and reimbursement navigation will be better positioned to convert innovation into durable demand.
A third trend will be portfolio and channel convergence. The line between optical aids, electronic magnifiers, software support, and wearable systems will continue to blur as users seek flexible solutions that adapt to changing vision levels and living environments. This creates opportunities for manufacturers to design modular product strategies, cross-sell across care settings, and build offerings that support both clinical use and home-based independence.
Still, uncertainty remains. Regulatory pathways can affect launch timing and documentation requirements. Reimbursement inconsistency can slow volume growth, especially in segments where device cost is highly visible. In addition, rapid feature escalation can raise expectations and complicate clinical integration if support, training, and interoperability are not addressed with equal seriousness. The market’s upside is significant, but it will be captured by organizations that can translate technology leadership into practical adoption.
Strategic Actions for Decision Makers
For device manufacturers, the priority should be aligning product roadmaps with adoption friction rather than feature count alone. That means investing in usability, training support, clinician-facing evidence, and reimbursement-friendly positioning as core commercial capabilities. Differentiating through ecosystem strength: fitting, service, compatibility, and long-term user engagement can be as important as the next technical enhancement.
PW Consulting
For investors, the most compelling opportunities are likely to sit at the intersection of intelligent assistance, wearable form factors, and rehabilitation integration. Due diligence should focus not only on technical novelty, but also on regulatory readiness, reimbursement exposure, channel access, and the ability to scale support infrastructure. Companies that can demonstrate real-world functional value and clear access pathways are better positioned for sustained traction.
Assistive Technologies for Visual Impairment Market
For procurement and care-program leaders, the practical opportunity is to treat low vision devices as part of a broader rehabilitation strategy rather than isolated purchases. Selecting solutions with stronger training support, clearer outcome expectations, and compatibility with home healthcare or clinic-based workflows can improve adoption consistency and long-term value. Structured evaluation across clinical benefit, usability, service model, and reimbursement fit will reduce downstream implementation risk.
Detailed segmentation data, company-level positioning, and region-specific commercial dynamics can sharpen these decisions further, especially for teams evaluating product entry, partnership structures, or investment theses in a market that is expanding quickly but remains operationally complex.
For detailed analysis of this topic, please visit the official page: Worldwide Low Vision Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


