



Worldwide Oblong Container Market: Beyond the 4.28% CAGR and Hidden Regional Shifts

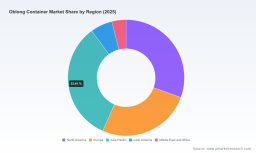
Strategic Trends and Commercial Opportunities in the Worldwide Oblong Container Market
Market Overview and Core Challenges
The worldwide oblong container market has evolved into a structurally significant segment within the broader rigid packaging industry, driven by consistent demand across consumer goods, industrial applications, and pharmaceuticals. With a total market valuation reaching approximately 1,251 million USD in 2025 and projected to advance toward 1,678 million USD by 2032, the segment reflects a compound annual growth trajectory of roughly 4.28 percent. This growth is not a simple continuation of historical expansion but rather a response to converging pressures in material economics, regulatory mandates, and application-specific performance requirements. The market has demonstrated measured resilience through cyclical demand shifts, with notable valuation stability between 2021 and 2023 before a reacceleration in recent years.
Despite this favorable trajectory, the industry faces three defining challenges that will shape competitive outcomes over the next several years. First, rising resin and metal input volatility is compressing margins for mid-tier producers and forcing earlier design-phase decisions around material substitution. Second, fragmented regulatory frameworks across major economies are accelerating the need for standardized sustainability attributes, creating compliance complexity for companies operating across multiple jurisdictions. Third, application differentiation is intensifying as end-use sectors demand containers that balance ergonomics, dispensing precision, chemical compatibility, and recyclability, narrowing the window for generic, low-differentiation product offerings. These pressures are not merely operational hurdles; they are redefining entry barriers and rewarding firms that can integrate material science, regulatory foresight, and application engineering into a single value proposition.
Worldwide Oblong Jar Market
Key Drivers Reshaping the Market
Technological innovation is no longer a peripheral advantage in this segment; it is becoming a core determinant of market share. Advances in blow molding precision, multi-layer coextrusion, and dispensing integration are enabling oblong containers that meet stricter performance criteria without proportionally increasing material weight. For manufacturers targeting personal care, household, and pharmaceutical applications, this translates into containers that can support airless mechanisms, controlled dosing, and improved barrier properties while maintaining the familiar oblong footprint preferred for shelf presence and user handling. The ability to embed functionality directly into container architecture reduces secondary packaging needs and aligns with broader sustainability objectives, creating a compounding benefit for brands seeking to meet both performance and environmental targets.
Regulatory pressure is simultaneously accelerating material transition timelines. In Europe, packaging regulations are establishing recycled content thresholds for plastic packaging that will effectively require redesigned oblong formats by the end of the decade. Parallel requirements in parts of the United States are mandating post-consumer recycled material adoption for rigid plastic containers, while extended producer responsibility frameworks in several states are shifting financial responsibility for end-of-life recovery toward producers. These developments are not isolated compliance events; they are restructuring the economics of container procurement. Companies that adopt recyclability-by-design principles and secure reliable recycled resin streams early are positioned to reduce future reformulation risk and avoid rushed transitions that often accompany late-stage regulatory deadlines.
Demand-side behavior is also shifting the competitive center of gravity. Consumer brands and industrial buyers increasingly evaluate packaging decisions through a combined lens of sustainability performance, supply reliability, and application compatibility. In the chemicals and solvents space, oblong containers must deliver chemical resistance, secure closure systems, and compatibility with industrial handling. In automotive and lubricant applications, containers are expected to support branding durability, safe transport, and efficient dispensing. Food and beverage, personal care, and pharmaceutical buyers are prioritizing material consistency, contamination control, and dispensing precision. This diversification of requirements is increasing the premium on engineered container solutions rather than commodity-style supply, pushing market value toward suppliers that can demonstrate application-specific competency.
Supply chain and cost structure dynamics complete the driver set. The cost of primary materials such as HDPE and PET has experienced measurable volatility, with HDPE resin averaging around 1,450 USD per metric ton in late 2025 and PET resin prices moving upward by roughly 8 percent year-over-year due to supply chain constraints. These fluctuations affect not only direct material costs but also the relative attractiveness of alternative material pathways and regional sourcing models. At the same time, production footprint decisions are being influenced by proximity to end markets, energy costs, and logistics resilience. Suppliers that can balance regional responsiveness with scale efficiency are gaining leverage, especially as buyers prioritize continuity of supply in addition to price competitiveness.
- Material innovation is moving from optional differentiation to baseline expectation, particularly where recycled content, lightweighting, and dispensing integration converge.
- Regulatory mandates are shifting procurement cycles toward longer planning horizons, rewarding early compliance and transparent material traceability.
- Application-specific requirements are raising the value of engineered oblong containers, reducing the share of purely commodity-oriented supply.
- Input cost volatility is reshaping sourcing strategies, increasing the importance of regional supply resilience and resin mix flexibility.
Competitive Landscape and Leading Strategies
The market is characterized by a moderately concentrated structure in which a limited group of established players accounts for a substantial share of revenue, while regional specialists and application-focused suppliers compete on differentiation rather than scale alone. Leading companies are pursuing distinct strategic positions that reflect their material competencies, end-use focus, and integration depth. Berry Global has reinforced its presence in oblong HDPE and PET containers for personal care, household, and pharmaceutical packaging, with recent product introductions emphasizing recycled content integration for personal care applications. Amcor has focused on custom oblong plastic bottles and jars for beauty, food, and healthcare use, showcasing recyclable designs optimized for hot-fill processes at major industry events. These moves reflect a broader emphasis on recyclability and application engineering rather than volume-only competition.
AptarGroup has built advantage around dispensing and closure integration, supplying oblong dispensing containers and pumps that work with rigid packaging for cosmetics and pharmaceuticals. This positioning allows the company to participate in value creation beyond the container body itself, where dispensing functionality, user experience, and dosing precision directly influence brand preference. Gerresheimer has concentrated on oblong glass and plastic primary packaging for pharmaceuticals, including vials and bottles, an area where regulatory compliance, material purity, and dimensional consistency are especially critical. Silgan has extended its portfolio across oblong metal and plastic containers through its plastics operations, targeting personal care and household products where durability and shelf-ready presentation matter. Albea has carved out a recognizable role in skincare and cosmetics packaging by supplying oblong airless and pump-enabled plastic containers, an approach that ties container geometry to product protection and dispensing performance.
What distinguishes these leaders is not simply product breadth but the alignment of capability with regulatory and demand trends. Companies that combine material expertise, dispensing or closure integration, and application-specific validation are better positioned to support customer transitions toward recycled content, recyclable formats, and enhanced end-use functionality. This alignment is also shaping competitive dynamics: larger players are expanding integration across container bodies, closures, and dispensing systems, while application specialists are seeking partnerships or niche scale to serve sectors with stringent performance requirements. New entrants face meaningful hurdles in raw material access, process engineering, and compliance readiness, but targeted entry remains possible in high-value subsegments where dispensability, barrier properties, or pharmaceutical-grade consistency create defensible positioning. Consolidation is likely where overlapping capabilities and regional footprints create cost or capability synergies, while fragmentation will persist where end-use customization demands small-batch engineering and close customer collaboration.
Forward-Looking Trends and Commercial Implications
Over the next three to five years, the oblong container market will likely be shaped by three interconnected trends. The first is the mainstreaming of recycled content and recyclability as procurement prerequisites. As recycled content expectations rise and regional rules tighten, oblong container designs that can accommodate post-consumer resin without compromising strength, clarity, or dispensing performance will gain preference. Commercial opportunity will accrue to suppliers that can provide validated material blends, transparent traceability, and consistent lot-to-lot quality, especially in personal care, household, and pharmaceutical applications where aesthetics and functional reliability are both important.
The second trend is the continued convergence of container geometry with dispensing and closure systems. Oblong formats are well suited to ergonomics and shelf presentation, but their value will increasingly depend on how effectively they integrate pumps, airless mechanisms, and closure technologies. This will favor suppliers that can offer coordinated container-plus-dispensing solutions rather than standalone vessels. For brands, this integration can reduce development risk, improve user experience, and support premium positioning in categories such as skincare, cosmetics, and specialty chemicals. The commercial opportunity lies in co-developed solutions that shorten time to market while meeting sustainability and performance targets simultaneously.
The third trend is regional supply realignment driven by material economics, regulatory geography, and logistics considerations. As resin pricing fluctuates and producer responsibility frameworks expand, buyers will place greater emphasis on supply continuity, regional manufacturing proximity, and compliance readiness. Suppliers with diversified production footprints and flexible material portfolios will be better equipped to manage cost shocks and meet jurisdiction-specific requirements. At the same time, consolidation may accelerate among players with overlapping capabilities, while application-specific niches remain open to focused specialists. The main risk is that rapid regulatory or input-cost changes could outpace product development cycles, forcing reactive redesigns and temporary margin pressure for companies with less flexible architectures.
Actionable Guidance for Decision Makers
For manufacturers, the priority is to align product portfolios with the direction of regulation and demand. This means investing in designs that can accommodate recycled content, ensuring compatibility with recyclable formats, and strengthening dispensing or closure integration where end-use applications justify it. Companies should also evaluate resin mix flexibility and regional sourcing options to reduce exposure to input volatility, while prioritizing application validation that supports customer adoption in higher-value segments.
PW Consulting
For investors, the most relevant signal is the widening gap between commodity-oriented container supply and engineered, application-integrated solutions. Capital allocation should favor businesses that demonstrate measurable progress in recycled content readiness, regulatory compliance, and functional integration, especially where those capabilities are tied to defensible end-use relationships. Monitoring M&A activity and capacity realignment will also help identify where scale synergies are being created versus where niche differentiation remains the stronger value driver.
For procurement and sourcing leaders, the imperative is to treat container selection as a multi-year strategic decision rather than a transactional purchase. Evaluating suppliers on recycled content capability, regulatory preparedness, dispensing integration, and supply resilience will reduce exposure to future reformulation and compliance risk. Longer-term partnerships with suppliers that can support coordinated design, material traceability, and application testing will typically deliver more stable outcomes than short-cycle price optimization alone.
For decision makers seeking deeper segmentation data, regional detail, and tailored scenario planning, the complete research report provides expanded breakdowns across material pathways, application categories, and competitive positioning. It also includes structured guidance for assessing investment timing, procurement strategy, and product development priorities in relation to evolving regulatory and cost dynamics.
Worldwide Bulk box Market
For detailed analysis of this topic, please visit the official page: Worldwide Oblong Container Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


