



Pharma Grade Calcium Hydroxide Market: Beyond the 5.36% CAGR, Unpacking Regional and Form Splits

Strategic Trends and Commercial Opportunities in the Worldwide Pharmaceutical Grade Calcium Hydroxide Market
Market Overview and Core Challenges
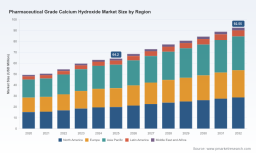
The global market for pharmaceutical grade calcium hydroxide has demonstrated steady expansion over the past half-decade, reflecting the compound's critical role in drug formulation, dental procedures, and specialized manufacturing processes. Valued at approximately 49.3 million USD in 2020, the market reached 64.2 million USD by 2025, and current projections indicate a trajectory toward 92.55 million USD by 2032. This growth path corresponds to a compound annual growth rate of 5.36 percent, signaling a mature yet consistently expanding sector where incremental gains compound over time.
Pharmaceutical Grade Sodium Chloride Market
The revenue base is distributed across multiple forms and applications, with powder formats capturing the largest share of commercial activity. Liquid and suspension variants represent a meaningful secondary segment, particularly in applications requiring uniform dispersion or handling flexibility. From an application standpoint, endodontic and dental filling procedures constitute the most significant demand driver, underscoring the material's established utility in clinical settings. Secondary demand streams include active pharmaceutical ingredient synthesis coupled with pH regulation workflows, as well as the use of calcium hydroxide as an excipient or calcium supplement in nutritional medicines. Geographically, demand is broadly distributed, with Asia Pacific, North America, and Europe each representing substantial portions of total volume. Emerging regions in Latin America and the Middle East and Africa contribute smaller but growing shares, reflecting gradual healthcare infrastructure development and localized manufacturing capacity.
Concentrated market dynamics shape the current landscape. The top three participants command roughly 38.4 percent of total revenue, while the five largest firms account for approximately 52.15 percent. This level of concentration suggests established relationships, entrenched quality certifications, and meaningful barriers to entry for new manufacturers seeking to compete on purity, regulatory compliance, or supply reliability.
Key Challenges at the Inflection Point
Despite the favorable growth narrative, several structural challenges are reshaping how companies plan capacity, pricing, and compliance investments.
-
Raw material cost volatility and environmental compliance pressure. Calcium hydroxide is produced through the hydration of quicklime, itself derived from calcination of high-calcium limestone. Recent data from Northeast Asia shows prices reaching 0.14 USD per kilogram in December 2025, a 12.7 percent increase from September of that year. The surge stems from rising upstream quicklime and energy costs, compounded by supply constraints linked to environmental compliance. These input pressures are not isolated; they reflect a broader pattern where production cost bases are increasingly sensitive to energy markets and regulatory-driven operating conditions.
-
Evolving emissions standards for lime manufacturing. Regulatory authorities in the United States finalized amendments to National Emission Standards for Hazardous Air Pollutants targeting lime manufacturing plants, addressing previously unregulated hazardous air pollutant emissions from lime kilns. In parallel, broader expectations around hazardous air pollutant and potential greenhouse gas emission standards are increasing scrutiny of kiln operations. For calcium-based compound producers, these developments can translate into higher capital expenditure requirements, operational adjustments, and cost structure changes that affect competitiveness.
PW Consulting -
Purity expectations and cross-application regulatory complexity. The material is simultaneously used in pharmaceutical manufacturing, food-grade formulations, and laboratory processes. U.S. FDA regulations explicitly list calcium hydroxide USP as an approved alkali for color additives exempt from certification, including caramel production for food use. This dual-use reality requires manufacturers to maintain rigorous documentation, lot traceability, and grade-specific production controls. Companies that struggle to separate or certify distinct purity tiers face higher compliance costs and greater risk of customer disqualification.
Key Drivers Shaping Market Evolution
The sustained expansion of pharmaceutical grade calcium hydroxide is not merely a function of incremental demand. It is shaped by a convergence of technological, regulatory, demand-side, and supply-side dynamics that are altering competitive requirements and opening differentiated opportunities for firms that respond proactively.
Technological Innovation and Purity Differentiation
Technical differentiation is becoming a decisive competitive lever. Leading producers are emphasizing ultra-low impurity profiles, targeting reductions in aluminum, iron, and manganese content that can interfere with pharmaceutical synthesis, nutritional formulations, or sensitive endodontic applications. High-purity calcium hydroxide meeting FCC, USP, and BP specifications is increasingly expected rather than treated as a premium add-on. Manufacturers that invest in controlled calcination conditions, advanced hydration processes, and rigorous analytical testing can command stronger customer loyalty and improve pricing resilience.
The practical impact of this trend is that technical capability now functions as a barrier to entry and a retention mechanism. Buyers in API synthesis and pH adjustment workflows select suppliers based on impurity thresholds, batch consistency, and documented certificates of analysis. In dental and endodontic applications, consistency and biocompatibility expectations further reward suppliers with mature quality management systems. Over time, these requirements are likely to compress the viable supplier base toward firms that can demonstrate repeatable purity performance rather than simply meet baseline specifications.
Regulatory Environment and Compliance Costs
The regulatory environment is shaping both demand and supply. On the demand side, explicitly approved usage pathways expand the addressable market. For example, the inclusion of calcium hydroxide USP in FDA regulations for color additives exempt from certification validates its role in food-related manufacturing, which can indirectly benefit producers with multi-grade capabilities. On the supply side, emissions-related amendments for lime manufacturing facilities introduce new compliance obligations. National emission standards targeting hazardous air pollutants from lime kilns, along with broader environmental performance expectations, increase the cost of maintaining operating permits and upgrading combustion or filtration systems.
This dual pressure creates a clear strategic implication: regulatory expertise is becoming a source of competitive advantage. Suppliers that anticipate emissions rule implementation, incorporate environmental compliance into capacity planning, and communicate transparently about product grade integrity will be better positioned to retain pharmaceutical and laboratory customers. Conversely, firms that treat compliance as a retrospective cost rather than a forward-looking operational design parameter may face margin compression and customer attrition.
Demand-Side Shifts in Healthcare and Manufacturing Practices
Demand patterns are evolving as healthcare procedures and pharmaceutical manufacturing practices mature. The prominence of endodontic and dental filling applications reflects the sustained clinical use of calcium hydroxide in pulp capping, disinfection, and related procedures. As dental care access expands in developing markets and as clinical protocols continue to favor established materials with predictable performance, demand for high-quality medical-grade material remains robust. Simultaneously, the role of calcium hydroxide in API synthesis and pH adjustment is supported by broader pharmaceutical production activity, where precise pH control and alkali selection influence yield, purity, and downstream processing efficiency.
Another demand-side driver is the use of calcium hydroxide within excipients and calcium supplements, where formulation reliability and mineral quality are central to product acceptance. Across these segments, procurement behavior is increasingly risk-averse: buyers favor suppliers with validated quality systems, consistent lead times, and clear regulatory documentation. This shift encourages longer-term supply relationships and rewards manufacturers that can provide not just a chemical product, but a documented, auditable supply solution.
Supply Chain and Cost Structure Realignment
Supply chain dynamics are being reshaped by energy costs, upstream lime availability, and regional production constraints. As noted in recent market data, regional price movements can be pronounced when energy costs rise or when compliance-driven constraints tighten supply. These fluctuations affect downstream procurement strategies, prompting buyers to consider regional sourcing, inventory buffers, and multi-supplier frameworks rather than relying on single-source procurement.
At the same time, large distributors and diversified chemical suppliers are extending their reach by offering pharmaceutical-grade calcium hydroxide alongside other specialty materials. This distribution model can improve availability, simplify procurement for smaller manufacturers, and create value through logistics and technical support. However, it also intensifies pressure on niche producers to differentiate through purity, technical service, or regional responsiveness. The net effect is a market where cost structures are increasingly tied to energy, compliance, and logistics, and where value capture depends on the ability to manage these elements while maintaining grade integrity.
Competitive Landscape and Leading Strategies
The competitive field includes manufacturers and distributors spanning North America, Europe, and Asia, with notably strong activity among Indian producers and Western suppliers serving pharmaceutical, laboratory, and food-related end markets. The current landscape is characterized by distinct strategic positions rather than a single unified approach.
Strategic Positioning of Leading Players
Several companies illustrate the range of viable strategies in this market. One U.S.-based producer specializes in high-purity calcium hydroxide with FCC/USP grades and ultra-low impurities, including low aluminum, iron, and manganese, targeting pharmaceutical synthesis and nutritional formulations. This profile reflects a purity-centric strategy where technical specifications and traceability are the primary differentiators. Another U.S. supplier provides pharmaceutical-grade material meeting USP standards for laboratory and manufacturing use, emphasizing consistent availability and compliance-aligned documentation for research and production environments.
Indian manufacturers represent a significant and differentiated cohort. Firms based in Maharashtra, Uttarakhand, and Gujarat produce calcium hydroxide in BP/USP/FCC/ACS grades, often with ISO-9001-2015 and GMP certifications. Their value proposition combines pharmaceutical and food-grade capabilities with regional cost advantages, enabling them to compete on price while maintaining accredited quality systems. Some Indian producers also pursue national standard participation, including involvement in drafting standards for food-additive calcium hydroxide, which can strengthen downstream acceptance and create reputational advantages in regulated markets.
European participants add further diversity. One German firm offers high-purity mineral salts including pharmaceutical-grade calcium hydroxide, while a major global distributor supplies calcium hydroxide across pharmaceutical and industrial applications. The distributor model emphasizes breadth, logistics, and technical support, often serving customers who prefer consolidated sourcing or who require flexible regional fulfillment. Another U.S. company provides calcium hydroxide suitable for food and pharmaceutical applications, reinforcing the multi-grade strategy that allows a single producer to serve overlapping demand streams.
Differentiation and Market Evolution
Across these profiles, differentiation is concentrated in a few recurring themes. Purity and impurity control remain central, especially for buyers in API synthesis and sensitive formulations. Certifications and audit-ready documentation are increasingly treated as baseline expectations. Regional availability and lead-time reliability influence purchasing decisions, particularly for dental and laboratory customers with tight production schedules. Multi-grade capability, allowing a supplier to serve pharmaceutical, food, and laboratory needs from related production assets, can broaden revenue opportunities and improve asset utilization.
Market evolution is likely to proceed through both consolidation and selective fragmentation. Concentration data indicates that a limited number of participants already command a meaningful share of revenue, and this pattern may persist as larger or better-capitalized firms invest in compliance, technical service, and supply reliability. At the same time, specialized producers with strong purity credentials or regional certifications can sustain defensible positions by serving high-value segments where specification control and documentation outweigh price alone. New entrants will face meaningful hurdles, not because the chemistry is complex, but because pharmaceutical customers require proven quality systems, consistent supply, and regulatory alignment that take time to build.
The role of distributors is also likely to expand as procurement teams seek flexibility. Distributors can aggregate supply from multiple producers, reduce administrative burden, and provide technical logistics support. However, their growth depends on the willingness of manufacturers to maintain consistent grade integrity and on buyers' confidence that distributor-supplied material meets the same specifications as direct procurement.
Future Trends and Commercial Implications
Looking ahead to the 2026-2032 period, three trends are likely to shape market behavior and commercial outcomes.
1. Compliance-Linked Cost Structures Will Become a Strategic Variable
Emissions-related standards for lime manufacturing and broader environmental expectations will continue to influence production economics. As facilities adapt kiln operations, filtration, and monitoring processes, cost structures will evolve. Suppliers that plan for compliance as part of capacity design, rather than reacting after rule implementation, will be better able to preserve margins and maintain supply continuity. Buyers should anticipate periodic cost pressure and build procurement strategies that incorporate resilience, such as qualified alternate sources and contract structures that account for input volatility.
2. Purity and Documentation Will Drive Segment Winners
As pharmaceutical, dental, and laboratory buyers increasingly prioritize impurity control and traceable documentation, firms that can consistently deliver USP/FCC/BP-grade material with low contamination profiles will capture disproportionate value. This trend favors producers with strong analytical capabilities, disciplined batch control, and transparent certification practices. It also suggests that multi-grade producers with clear internal segregation between pharmaceutical and food grades may gain advantage by reducing cross-contamination risk and simplifying audits.
3. Regional Demand Growth and Distribution Models Will Redefine Access
Demand growth is expected to remain broad-based, with Asia Pacific, North America, and Europe continuing to anchor volume, while Latin America and the Middle East and Africa contribute incremental expansion as healthcare and manufacturing capacity develop. distributors and regional suppliers are likely to play a larger role in connecting producers with end users, especially where localized availability, technical support, and flexible logistics are valued. For manufacturers, this creates opportunities to expand reach without necessarily building extensive direct sales infrastructure, provided product quality and documentation remain dependable.
Potential risks include sharper-than-expected energy price swings, tightening environmental requirements that accelerate cost escalation, and the possibility that procurement teams shift toward alternative alkalis or formulation approaches in specific applications. These uncertainties do not undermine the overall growth trajectory, but they do emphasize the need for flexible sourcing and continuous monitoring of regulatory and input-cost developments.
Actionable Guidance for Decision-Makers
The evolving market environment rewards proactive positioning. Different stakeholders can derive distinct value from a focused response.
For Manufacturers
-
Invest in purity assurance and analytical documentation as core capabilities rather than support functions. Ultra-low impurity profiles and audit-ready certificates can improve retention in pharmaceutical and dental segments.
-
Incorporate environmental compliance into capacity and operational planning. Anticipating emissions standards and energy cost exposure can reduce surprise margin compression and protect supply reliability.
-
Evaluate multi-grade production strategies carefully. Clear segregation between pharmaceutical and food-grade output can reduce risk while enabling broader customer coverage.
For Investors
-
Assess companies based on their ability to manage compliance-linked cost structures, maintain grade integrity, and serve stable demand segments such as endodontics, API synthesis, and excipient use.
-
Look for suppliers and distributors with diversified geographic exposure and credible certifications, since these attributes support resilience amid input volatility and regulatory change.
-
Monitor consolidation potential among smaller producers and the strategic role of distributors, as both can reshape competitive dynamics over the forecast period.
Magnesium Hydroxide Market
For Procurement and Supply Chain Leaders
-
Diversify sourcing where feasible, balancing price with purity credentials, lead-time reliability, and documentation quality. Single-source dependence can increase exposure to regional price spikes or compliance disruptions.
-
Align supplier selection with application sensitivity. Dental and API synthesis uses may warrant stronger emphasis on impurity control and traceability, while less sensitive uses may allow broader sourcing flexibility.
-
Track regulatory developments affecting lime manufacturing and downstream material availability. Early awareness can support contract planning and inventory decisions.
Given the interplay of purity requirements, regulatory shifts, energy-linked cost dynamics, and regional demand growth, timely access to detailed segment data and customized strategic assessment is essential for effective decision-making. For deeper visibility into regional breakdowns, application-level demand patterns, pricing trajectories, and competitor-specific positioning, the full PW Consulting market report provides expanded data coverage and tailored implications across manufacturing, investment, and procurement scenarios.
For detailed analysis of this topic, please visit the official page: Worldwide Pharmaceutical Grade Calcium Hydroxide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


