



Global Stainless Steel Bailers Market: Why 6.82% CAGR and Groundwater Demand Redefine Growth

Navigating the Stainless Steel Bailers Market: Strategic Shifts and Commercial Frontiers (2025–2032)
Market Overview and Core Challenges
The global stainless steel bailers market has matured into a specialized yet steadily expanding segment, characterized by consistent demand from environmental monitoring, industrial remediation, and materials processing applications. Between 2020 and 2025, the sector demonstrated resilient growth, settling into an estimated revenue trajectory that extends through 2032. Current market sizing places the industry at approximately USD 54.6 million in 2025, with projections indicating a compound annual growth rate of 6.82 percent through the forecast horizon. By 2032, total market revenue is expected to surpass USD 86.5 million, reflecting sustained institutional procurement cycles and gradual substitution of legacy sampling equipment with corrosion-resistant alternatives.
This growth trajectory is neither uniform nor guaranteed. The market operates within a fragmented ecosystem where three leading manufacturers collectively account for roughly a third of total revenue, while the top five players capture just under half. Such concentration suggests that scale advantages exist, yet the remaining share is distributed across regional specialists, niche fabricators, and emerging equipment assemblers. This structural dispersion creates both operational friction and strategic opening. Companies that rely on standardized product lines without adapting to regional compliance requirements or material specifications frequently encounter margin compression and slower order conversion. Conversely, firms that align manufacturing capabilities with localized sampling protocols and decontamination standards are capturing repeat contracts and longer equipment lifecycles.
Three intersecting challenges currently define the market’s inflection point. First, material cost volatility and geographic price divergence are reshaping cost structures. Stainless steel pricing has shown meaningful variation across major sourcing corridors, forcing manufacturers to recalibrate procurement strategies, hedge inventory exposure, or shift production footprints to maintain competitive pricing without sacrificing metallurgical integrity. Second, regulatory expectations around contamination control and sampling integrity are accelerating design evolution. Buyers increasingly require equipment that eliminates cross-sample interference, supports rapid decontamination, and avoids legacy sealing materials that compromise analytical accuracy. Third, the convergence of corrosion-resistant sampling tools with broader industrial compaction and recycling equipment is blurring traditional category boundaries. Organizations that previously sourced bailers and balers from entirely separate supply chains are now evaluating integrated procurement frameworks, which pressures incumbent suppliers to clarify product positioning and avoid internal cannibalization.
These dynamics do not merely represent operational headwinds; they function as signal filters for market entry, product investment, and partnership strategy. Firms that treat the current period as a static demand environment risk misallocating engineering resources and missing procurement consolidation windows. Those that recognize the overlap between material science, compliance timing, and procurement behavior can position themselves ahead of specification shifts and contract renewal cycles.
Key Drivers Reshaping the Market
Technological innovation is reshaping how stainless steel bailers are specified, manufactured, and deployed in the field. Advances in forming precision, weld integrity, and surface finishing have moved crevice-free and mirror-polished configurations from premium custom orders toward standard expectations for high-integrity sampling. Equipment engineered with fully welded seams, controlled internal geometries, and removable top and bottom assemblies reduces residual contamination risk and shortens decontamination cycles. These design attributes directly translate into fewer sampling errors, faster site turnaround, and lower long-term replacement frequency, which procurement teams increasingly value when comparing total cost of ownership rather than upfront unit price alone.
Stainless Steel Sink Market
Regulatory and compliance environments are exerting parallel pressure on product architecture. Environmental sampling standards continue to tighten around PFAS-related concerns and analytical purity, prompting manufacturers to introduce sealing and component configurations that avoid contamination pathways. Equipment supplied with PFAS-free O-ring options and fluoropolymer check mechanisms is gaining preference in groundwater monitoring programs where regulatory bodies and laboratory partners demand verifiable sample integrity. At the same time, safety and hygiene certification requirements are influencing broader stainless steel equipment categories, including compaction and recycling machinery used in sensitive operational environments. Compliance with recognized safety standards and material traceability documentation is becoming a procurement prerequisite rather than an optional differentiator.
Worldwide Stainless Steel Fermenter Market
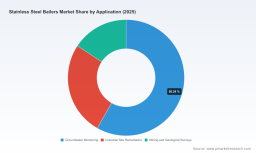
Demand-side behavior is shifting as end users consolidate sampling programs and prioritize equipment durability over short-cycle replacement. Groundwater monitoring remains the dominant application driver, supported by ongoing environmental assessment, site characterization, and regulatory compliance activities. Industrial site remediation and mining or geological survey work contribute additional demand, particularly where repeated borehole access, composite sample collection, and field decontamination efficiency matter. Procurement teams in these segments are increasingly favoring reusable stainless steel configurations that withstand repeated cleaning, resist pitting and stress corrosion in demanding media, and support standardized attachment or retrieval systems across multiple well diameters.
Supply chain and cost structure changes are reinforcing these demand trends. The broader stainless steel market continues to expand on the back of industrial equipment demand, yet regional price differentials require deliberate sourcing strategies. Manufacturers operating with transparent material grade documentation and consistent finish specifications can command stronger positioning in procurement evaluations, especially when buyers need to verify material provenance for compliance records. Meanwhile, the cost of non-compliance is rising. Equipment that fails to support adequate decontamination, introduces particulate or chemical interference, or requires excessive maintenance adds hidden operational expense that outweighs initial savings. This reality is pushing buyers toward suppliers that can demonstrate repeatable quality control, consistent metallurgical specifications, and service-ready component designs.
Taken together, these drivers suggest that the market’s growth will be defined less by volume expansion alone and more by specification upgrading, compliance alignment, and procurement rationalization. Companies that integrate material traceability, contamination-reducing design, and service-friendly construction into their product roadmaps are better positioned to capture share in contracts where sample integrity and operational efficiency carry significant weight.
Competitive Landscape and Leading Strategies
The competitive field reflects a mix of established environmental sampling specialists, regional fabricators, and broader industrial equipment manufacturers whose stainless steel product lines touch overlapping customer needs. Several firms have anchored their positioning around durability, material grade consistency, and decontamination efficiency. Manufacturers offering 304 and 316 stainless steel configurations with removable ends, tapered profiles, or fully welded and crevice-free interiors are emphasizing ease of cleaning, material compatibility, and long service life in sampling contexts. These design choices are not merely technical preferences; they function as commercial signals that align with buyer priorities around repeat use, sample protection, and reduced field downtime.
Differentiation is increasingly expressed through compliance readiness and application-specific fit rather than generic durability claims. Some suppliers have focused on groundwater sampling specifications that support composite collection, well retrieval, and rapid decontamination, with material and sealing configurations chosen to meet environmental testing expectations. Others have extended stainless steel bailer and baler capabilities into hygiene-sensitive or heavy-duty environments, where certification documentation, surface finish quality, and corrosion-resistant construction support procurement requirements in food-adjacent, recycling, or industrial processing settings. This divergence in focus illustrates how the market is splitting into application-driven sub-positions, even as the underlying material and manufacturing technologies overlap.
The landscape is evolving along three observable directions. First, consolidation remains selective rather than sweeping. Larger players with established distribution channels and recognized product lines are gaining incremental advantage through repeat procurement relationships and specification familiarity, but the market still accommodates specialized manufacturers that can respond faster to regional compliance nuances or custom size requirements. Second, segmentation is sharpening. Procurement teams are distinguishing between bailers intended for high-integrity environmental sampling and balers or compactors used in scrap handling and recycling workflows. Suppliers that clearly articulate these boundaries, while retaining shared manufacturing efficiencies where possible, are less exposed to comparison confusion and margin erosion. Third, new entrants and re-entering competitors are leveraging trade platforms and regional supply networks to validate technology relevance and sourcing connectivity. Industry gatherings and supplier exhibitions continue to function as alignment points where component suppliers, fabricators, and end users compare material options, finish standards, and integration requirements. The resulting visibility can accelerate adoption of newer specifications, particularly when they address contamination control, material traceability, or cleaning efficiency.
Strategic advantage in this environment belongs to organizations that combine consistent metallurgical control with clear application positioning. Firms that invest in repeat-use durability, rapid decontamination design, and documented material conformity can compete on reliability rather than price alone. At the same time, those that maintain responsive production for diameter variations, sealing options, and region-specific compliance documentation are better equipped to capture procurement cycles where buyers evaluate total operational impact rather than unit economics in isolation.
Forward Outlook: Trends Shaping the Next Three to Five Years
The market’s next phase will likely be defined by specification upgrades, procurement consolidation, and continued convergence between sampling integrity and broader industrial stainless steel equipment requirements. One central trend is the deepening preference for contamination-minimizing construction and sealing configurations. As sampling programs face more stringent analytical expectations and laboratory partnership requirements, equipment that supports crevice-free geometries, controlled finishes, and alternative sealing materials will become harder to replace with lower-specification alternatives. This trend favors suppliers that can standardize such features without sacrificing production efficiency or inflating lead times.
A second trend is the increasing alignment of procurement decisions with total lifecycle value. Buyers are paying closer attention to decontamination speed, corrosion behavior under repeated use, and component accessibility for cleaning and inspection. This shift rewards manufacturers that design for serviceability and repeated field use, and it pressures those that compete primarily on initial price to justify hidden maintenance or replacement costs. Over the next several years, contract renewals and multi-unit procurement agreements are likely to reflect these lifecycle considerations more explicitly, creating opportunities for suppliers with demonstrable durability records and consistent quality control.
A third trend involves regional sourcing strategy adaptation in response to material cost divergence and compliance documentation expectations. As buyers verify material grades, certification traceability, and finish consistency, suppliers that can provide clear documentation and stable specification control will gain an edge in evaluation processes. At the same time, regional price variation will continue to push manufacturers toward more deliberate procurement routing, inventory planning, and production allocation. Companies that treat material cost fluctuation as a design and sourcing variable rather than a passive input are more likely to preserve margins while meeting specification demands.
These trends carry commercial opportunity, but also risk. Demand for higher-specification equipment may intensify competition among capable manufacturers, compressing differentiation if multiple suppliers converge on similar construction standards. Regulatory language around contamination and sampling integrity may also evolve, requiring product updates or documentation adjustments that are not always predictable in timing. Additionally, if downstream sampling programs reduce activity levels or shift toward alternative collection methods in certain regions, revenue growth could become uneven across applications. Firms that monitor specification changes, procurement behavior, and material cost movement will be better placed to adjust product emphasis and contract strategy before cycles turn.
Actionable Guidance for Decision-Makers
Manufacturers should prioritize specification clarity and design-for-cleaning as core commercial levers. Where product lines span multiple applications, maintaining clear distinctions between environmental sampling configurations and industrial compaction or recycling equipment reduces comparison confusion and protects positioning. Engineering effort is best directed toward repeatable weld quality, accessible decontamination design, and documented material conformity, since these attributes increasingly influence procurement evaluation beyond initial pricing.
Investors and strategic partners should evaluate exposure to specification-driven demand rather than volume assumptions alone. Companies with strong documentation practices, consistent metallurgical control, and application-specific positioning are more likely to retain purchase cycles in environments where sample integrity and compliance requirements carry weight. Monitoring procurement consolidation, regional price dynamics, and certification expectations provides early signals about which product categories will face margin pressure and which will command stronger retention.
Procurement teams and end users should structure evaluations around total operating impact. Variables such as decontamination time, residual contamination risk, corrosion behavior under repeated use, and material traceability can materially affect program reliability and long-term cost. Requesting consistent specification documentation and comparing lifecycle implications across diameter options, sealing configurations, and finish standards supports more resilient sourcing decisions, especially when equipment is deployed across multiple sites or monitoring campaigns.
For decision-makers seeking a deeper mapping of segment dynamics, competitive positioning, and procurement trends across regions and applications, the full PW Consulting market analysis provides expanded segmentation detail, scenario-based projections, and customization options tailored to internal planning needs.
PW Consulting
For detailed analysis of this topic, please visit the official page: Worldwide Stainless Steel Bailers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


