



Worldwide Technical Grade Salicylic Acid Market: A 6.28% CAGR Outlook to 2032

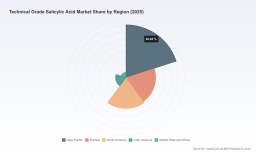
Global Technical Grade Salicylic Acid Market: Strategic Trends and Commercial Opportunities Through 2032
Market Snapshot and Core Challenges
The global market for technical grade salicylic acid has demonstrated steady, resilient growth over the past half-decade, expanding from approximately USD 382.5 million in 2020 to an estimated USD 516.6 million in 2025. Projections indicate continued expansion at a compound annual growth rate of 6.28 percent through 2032, with the market expected to surpass USD 790 million by the end of the forecast window. This trajectory reflects a sector that has moved beyond cyclical volatility to establish a more structurally robust demand foundation, driven by its critical role as a building block in industrial chemistry, cosmetics formulation, and polymer synthesis.
Despite this positive momentum, the industry is navigating a set of interconnected challenges that are reshaping competitive dynamics and investment calculus. The first major pressure point is cost volatility tied to upstream feedstock dependencies. Technical-grade salicylic acid is synthesized primarily through the Kolbe-Schmitt reaction, which relies heavily on phenol and carbon dioxide as core inputs. Phenol pricing, in turn, tracks closely with benzene markets and broader crude oil fluctuations. Recent price movements illustrate this sensitivity: in Northeast Asia, salicylic acid prices dipped to USD 1.68 per kilogram in early 2026, driven by lower phenol input costs and regional oversupply, while European markets experienced the opposite pressure, with prices reaching USD 5.38 per kilogram following elevated phenol and energy costs throughout late 2025. This regional divergence creates uneven margin landscapes and complicates global sourcing strategies for downstream buyers.
The second critical challenge revolves around regulatory compliance and environmental standards. Stringent frameworks such as EU REACH have raised the operational bar for chemical manufacturing facilities, requiring significant capital allocation toward waste treatment infrastructure, emission controls, and process modifications. For producers operating in or exporting to regulated markets, these requirements are no longer optional overhead but foundational cost components. Facilities that cannot absorb or pass through these compliance costs risk margin compression, while those that proactively upgrade processes can leverage regulatory readiness as a competitive differentiator.
A third structural tension lies in market concentration and capacity alignment. The industry exhibits moderate concentration, with the top three players accounting for roughly 44.5 percent of revenue and the top five capturing approximately 61.2 percent. While this level of consolidation provides some pricing stability, it also means that supply disruptions at a handful of major facilities can ripple through global availability. At the same time, demand patterns are shifting across application verticals, with industrial intermediates and personal care formulations absorbing growing shares of production output. Manufacturers must balance capacity allocation across competing end-use segments while maintaining grade purity and consistency that meet increasingly specific customer requirements.
Key Demand Drivers and Structural Shifts
Innovation in Manufacturing Processes and Product Grade Optimization
Process innovation has emerged as a primary catalyst for market evolution, particularly as manufacturers seek to differentiate technical grade offerings in a commodity-adjacent space. Recent industry activity highlights a clear pivot toward capacity optimization and grade specialization. In early 2026, a leading European producer executed a strategic internal restructuring and asset integration initiative designed to expand global salicylic acid production capacity across both pharmaceutical and industrial technical grades. This consolidation signals a broader industry recognition that scale, process efficiency, and grade flexibility are increasingly intertwined competitive advantages. Around the same period, multiple manufacturers advanced capacity expansion projects and process innovations specifically targeting industrial-grade and technical-grade supply, indicating that the segment is attracting focused investment rather than serving as a residual output of pharma-grade operations.
These process advancements translate directly into commercial value. Improved yield rates, reduced waste streams, and tighter control over impurity profiles allow producers to offer technical grade material that meets increasingly stringent specifications from downstream formulators. For applications such as dyes, pigments, rubber auxiliaries, and organic synthesis intermediates, batch-to-batch consistency and purity thresholds directly impact end-product performance. Manufacturers that can reliably deliver high-purity technical grades with lower processing costs are capturing preferential supplier status and building longer-term supply agreements.
Regulatory Evolution and the Compliance Premium
Regulatory dynamics are reshaping the competitive landscape by creating a compliance premium that separates established producers from marginal capacity. Environmental mandates and chemical safety regulations have elevated the cost of market participation, particularly in Europe and other highly regulated jurisdictions. Facilities that have already invested in advanced waste treatment systems, closed-loop processing, and documented quality management frameworks are positioning compliance as a value proposition rather than a burden. This is especially relevant for buyers in cosmetics, personal care, and industrial applications who face their own downstream scrutiny and require suppliers with verifiable environmental and quality credentials.
The regulatory environment also influences geographic sourcing patterns. As compliance costs rise in certain regions, buyers are reassessing supply chain configurations, weighing the trade-offs between proximity, logistics costs, and regulatory assurance. Producers with established certifications, transparent audit trails, and documented process controls are gaining leverage in negotiations, while those without clear compliance positioning face increasing friction in accessing premium markets.
Worldwide Sodium Salicylate Market
Shifting Demand Patterns Across End-Use Verticals
Demand-side behavior is evolving as formulation trends, industrial manufacturing needs, and consumer preferences reshape application priorities. Technical grade salicylic acid serves as a versatile intermediate across multiple sectors, and its growth is being pulled by several distinct demand streams. In personal care and cosmetics, the compound continues to play a foundational role in exfoliating formulations, acne treatments, and skin-conditioning products. Consumer preferences for effective, scientifically backed skincare ingredients have sustained demand for high-quality salicylic acid, while formulators increasingly require materials that meet both performance and regulatory standards.
Industrial and chemical synthesis applications represent another powerful demand engine. Technical grade material is widely used in the production of dyes, pigments, preservatives, resins, and rubber auxiliaries. Growth in specialty chemicals, advanced materials, and performance coatings has increased the need for reliable, specification-grade intermediates that can be integrated into complex manufacturing workflows. Additionally, the pharmaceutical intermediates segment continues to absorb a significant portion of production, with technical grade output often serving as a cost-effective feedstock for further refinement or for applications where ultra-high purity is not the primary requirement.
Feedstock Economics and Supply Chain Realignment
The economics of salicylic acid production are fundamentally tied to phenol availability and pricing, which themselves depend on benzene markets and crude oil dynamics. This upstream linkage means that feedstock cost fluctuations can rapidly alter production economics, influencing capacity utilization decisions, pricing strategies, and regional competitiveness. Recent market conditions have underscored this relationship, with price divergence between Northeast Asia and Europe reflecting localized differences in feedstock costs, energy inputs, and supply-demand balances.
Supply chain realignment is also being driven by logistics considerations, regional trade dynamics, and the desire to reduce exposure to single-source dependencies. Buyers are increasingly evaluating multi-regional sourcing strategies, balancing cost advantages from lower-price regions against the reliability and compliance assurance offered by established suppliers in other markets. For producers, this environment rewards operational flexibility, transparent pricing mechanisms, and the ability to maintain consistent supply across fluctuating input cost cycles.
Competitive Landscape and Leading Strategies
The competitive structure of the technical grade salicylic acid market features a mix of vertically integrated European producers, established Indian manufacturers with strong export orientation, and a growing cohort of Chinese suppliers serving both domestic and global industrial markets. This geographic and strategic diversity creates a dynamic environment where differentiation is achieved through process expertise, grade specialization, regulatory readiness, and supply reliability rather than price alone.
Seqens Group (Novacyl) stands out as the sole European producer of salicylic acid, leveraging a vertically integrated model and a proprietary single-step process that converts phenol directly into both pharmaceutical and technical grades. This integration provides control over key process stages and enables the company to supply high-purity material for industrial intermediates, dyes, and resins while maintaining the flexibility to shift output across grade categories based on demand signals. The company's recent capacity consolidation and asset integration efforts reinforce its focus on scaling production capabilities to support both pharma and industrial technical grade requirements, positioning it as a strategic supplier for customers seeking European-sourced material with established process credibility.
Indian manufacturers represent a significant and growing presence in the technical grade segment, with companies such as Siddharth Carbochem Products Ltd., Alta Laboratories Ltd. (Lona Industries), and Muby Chemicals (Mubychem Group) focusing on industrial applications including dyes, resins, rubber auxiliaries, and chemical synthesis. These producers benefit from competitive cost structures and established export channels, while also investing in product grade consistency and application-specific capabilities. Their ability to supply reagent and technical grades for a range of non-pharma industrial uses makes them important partners for downstream buyers seeking reliable, cost-effective material for bulk and intermediate applications.
Chinese producers, including JQC (Huayin) Pharmaceutical Co., Ltd., Hebei Jingye Medical Technology, Zhenjiang Gaopeng Pharmaceutical Co., Ltd., and Achilles Chemical, have expanded their footprint by offering technical, pharmaceutical, and cosmetic grades with varying degrees of compliance documentation and international certification. Achilles Chemical, for example, emphasizes REACH and ISO9001 compliance to support access to global industrial markets, while other Chinese manufacturers have built supply portfolios that span dyes, preservatives, organic synthesis, and rubber auxiliaries. The scale of Chinese production capacity, combined with growing attention to grade differentiation and compliance, has made these suppliers increasingly relevant for buyers looking to diversify sourcing or access competitive pricing without sacrificing specification reliability.
Worldwide Toluicacid Market
The market is showing signs of both consolidation and differentiation. Capacity expansion and process innovation activity has concentrated among manufacturers that are investing specifically in technical and industrial grade supply, suggesting that the segment is moving from a byproduct mindset to a strategic focus. At the same time, regulatory requirements, feedstock cost pressures, and application-specific quality demands are creating barriers that favor established players with documented process control, compliance infrastructure, and supplier relationships. New entrants face the challenge of matching not only price but also grade consistency, certification readiness, and supply reliability, which means that competitive advantage is increasingly earned through operational capability rather than capacity alone.
Future Trends and Commercial Implications
Looking ahead to the 2027 through 2030 period, several trends are likely to shape the technical grade salicylic acid market and create distinct commercial opportunities. First, grade specialization and specification-driven sourcing will intensify. As downstream formulators in cosmetics, industrial coatings, dyes, and chemical synthesis demand tighter impurity controls and more consistent batch profiles, producers that can offer clearly differentiated technical grades with documented quality parameters will command stronger positioning. This creates an opportunity for manufacturers to move up the value chain within the technical grade segment itself, capturing margin by aligning product specifications with application requirements rather than competing solely on volume and price.
Second, regional supply chain rebalancing will continue as buyers respond to feedstock cost divergence, regulatory differences, and logistics considerations. The price gap observed between Northeast Asia and Europe in early 2026 is indicative of a broader pattern where regional cost structures and supply-demand balances influence sourcing decisions. Companies that can offer transparent pricing, flexible supply arrangements, and multi-region fulfillment options will be better positioned to serve global customers navigating these variations. For producers, this environment rewards operational agility and the ability to maintain reliable output across fluctuating input cost cycles.
Third, regulatory compliance and environmental process investment will increasingly function as strategic differentiators rather than pure cost centers. As environmental standards tighten and downstream industries face greater scrutiny over their supply chains, suppliers with robust waste treatment, energy efficiency, and quality management systems will gain preference in qualification processes. This trend opens opportunities for producers that have already invested in compliance infrastructure, while raising the stakes for those that have not. Buyers, in turn, will place greater weight on documented compliance and process transparency when evaluating supplier portfolios.
Potential risks and uncertainties remain. Feedstock price volatility linked to crude oil and benzene markets can disrupt production economics and compress margins if not managed through hedging, pass-through mechanisms, or process efficiency gains. Regulatory changes in key markets could require additional capital investment or alter the cost competitiveness of certain production sites. Additionally, if regional oversupply emerges in specific markets, price pressure could intensify, testing the ability of producers to maintain differentiation and protect margins. Navigating these uncertainties will require proactive monitoring of feedstock trends, regulatory developments, and application-level demand shifts.
Strategic Recommendations for Decision Makers
For manufacturers and producers, the priority should be to strengthen grade differentiation and process reliability as competitive anchors. Investing in process control, impurity profiling, and compliance documentation enables technical grade offerings to be positioned as specification-matched solutions rather than undifferentiated commodities. Capacity decisions should account for the ability to serve multiple application verticals without compromising consistency, and supply chain strategies should incorporate feedstock cost monitoring and scenarios for regional price divergence.
For investors and strategic stakeholders, the market's 6.28 percent CAGR trajectory and the ongoing capacity and process innovation activity suggest that technical grade salicylic acid remains an attractive segment for targeted investment, particularly in operations that combine scale with grade flexibility and regulatory readiness. Due diligence should evaluate feedstock exposure, compliance infrastructure, application diversification, and the supplier's ability to maintain consistent output across input cost cycles. Companies that have already consolidated capacity or advanced process improvements are likely to capture disproportionate share in a market where reliability and specification control are increasingly decisive.
For procurement and sourcing leaders, the current environment rewards a structured evaluation of supplier capabilities beyond unit price. Qualification processes should weigh grade consistency, compliance certifications, supply reliability across regions, and the supplier's track record in managing feedstock and energy cost volatility. Building a diversified supplier base that includes both cost-competitive regional sources and compliance-assured strategic partners can reduce exposure to regional price shocks while maintaining access to material that meets application-specific requirements.
Given the pace of capacity consolidation, process innovation, and regulatory evolution, decision makers benefit from access to detailed segmentation data, regional price dynamics, and company-level capability profiles to inform sourcing, investment, and production strategy. Comprehensive market research that maps grade specifications, application demand shifts, and competitive positioning can provide the granularity needed to translate broad trends into actionable business decisions.
PW Consulting
For detailed analysis of this topic, please visit the official page: Worldwide Technical Grade Salicylic Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


