



M.2 SSD Market: Why NVMe PCIe and 17% CAGR Redefine the 2032 Growth Trajectory

The M.2 Interface SSD Market at an Inflection Point: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
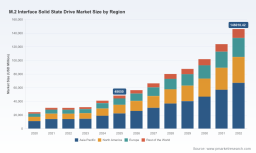
The worldwide M.2 interface solid-state drive market has entered a phase of aggressive expansion, fueled by the convergence of high-performance computing, AI-driven workloads, and rapidly evolving endpoint devices. Over the historical period from 2020 to 2025, the sector demonstrated remarkable resilience and growth, with revenues climbing from roughly 24.15 billion USD in 2020 to an estimated 48.65 billion USD in 2025. This trajectory positions the market to sustain a compound annual growth rate of approximately 17.02 percent through the forecast horizon ending in 2032, reaching a projected revenue scale that underscores the M.2 form factor's dominance across consumer, enterprise, and specialized computing applications.
Such rapid expansion is not without structural friction. The first critical challenge lies in the severe tightness of NAND flash supply. Contract pricing for memory components has experienced dramatic swings, with late 2025 and early 2026 reports documenting increases ranging from over 50 percent to nearly 246 percent compared to early 2025 baselines. Major suppliers have indicated that 2026 production capacity is fully committed, extending lead times and pressuring the bill of materials for M.2 SSDs. This supply-demand imbalance forces manufacturers and OEMs to navigate volatile input costs while maintaining competitive pricing and margin structures.
A second pivotal challenge stems from the intensifying geopolitical and regulatory landscape. Ongoing export controls on advanced semiconductors and related manufacturing equipment continue to reshape global supply chains for memory components. Concurrently, geopolitical tensions and associated tariffs create additional layers of complexity for sourcing NAND flash and finished SSD components across regions. These dynamics elevate the strategic importance of supply chain resilience, regional diversification, and inventory planning, particularly for organizations that rely on tightly coupled component ecosystems.
The third challenge centers on the rapid pace of protocol and form factor evolution. As PCIe Gen5 technology matures and moves into mainstream and ultra-compact applications, the market faces a transitional period where legacy SATA-based M.2 deployments must be carefully managed alongside next-generation NVMe solutions. The coexistence of multiple generations, varying endurance requirements across client, enterprise, and industrial segments, and the emergence of highly specialized compact form factors creates a complex engineering and product strategy environment. Companies that fail to align their roadmaps with these technological inflection points risk losing relevance in increasingly performance- and efficiency-driven segments.
Key Drivers of Market Evolution
Technological Innovation and Architectural Breakthroughs
The most potent catalyst for M.2 SSD growth is the rapid advancement of NAND flash density, controller efficiency, and interface bandwidth. The transition to PCIe Gen5 represents a fundamental shift in performance ceilings, enabling dramatically higher sequential and random throughput that directly benefits AI inference at the edge, content creation workstations, and high-density client computing. Manufacturers are pushing these capabilities into increasingly compact footprints. For example, Samsung showcased the PM9E1, recognized as the world's first 4TB PCIe Gen5 SSD in a compact M.2 2242 form factor, specifically optimized for AI workloads and compact systems. Such innovations demonstrate that high capacity and top-tier performance can be delivered in space-constrained environments, opening new design possibilities for OEMs and system integrators targeting both mainstream and specialized applications.
Worldwide SSD Memory Card Market
Equally significant is the democratization of advanced NAND technologies for broader market reach. Micron's launch of the 3610 NVMe SSD, the industry's first PCIe Gen5 G9 QLC client SSD for mainstream computing, brought single-sided M.2 2230, 2242, and 2280 form factors with capacities up to 4TB to the forefront of general-purpose laptop and ultra-thin designs. Kioxia followed with the BG8 series, introducing PCIe Gen5 to mainstream PC systems across 2230, 2242, and 2280 form factors with 512GB to 2TB capacities, with sampling to OEM partners leading to expected system availability in the second quarter of 2026. These moves signal that cutting-edge performance is no longer confined to premium niche products; it is being systematically embedded into volume platforms, expanding the addressable market and raising the baseline expectations for consumer and business computing devices.
Demand-Side Shifts Across Endpoint Segments
Demand-side dynamics are being reshaped by the proliferation of AI-enabled workflows, data-intensive professional applications, and the continuous evolution of client and embedded computing. Enterprise and client environments are increasingly requiring storage solutions that can sustain high I/O concurrency, low latency, and robust endurance under sustained workloads. At the same time, the industrial and embedded sectors are developing specialized requirements that call for secure boot capabilities, ruggedized designs, and compliance with ecosystem standards. Virtium's announcement of the StorFly-HS OCP S.A.F.E.-certified industrial M.2 2242 PCIe Gen4 NVMe boot SSD highlights this trend, delivering the first such certified solution for secure boot in OCP ecosystems with mass production and qualification samples available. The expansion of Greenliant's PrimeDrive SX Series economical NVMe M.2 2280 SSDs, with volume shipping beginning in late 2025, further illustrates how industrial and embedded applications are accessing cost-optimized NVMe performance while meeting stringent deployment needs.
On the brand and market positioning side, Western Digital unveiled SANDISK Optimus as the new branding for its internal NVMe SSD portfolio, consolidating previously separated lines and signaling updated product rollouts expected at retailers during the first half of 2026. This rebranding reflects a broader industry pattern: as performance tiers and use cases become more granular, companies are refining their go-to-market narratives to better align with creator, gaming, professional, and mainstream segments. The cumulative effect is a market where demand is not only growing in volume but also becoming more segment-aware, requiring tailored performance, reliability, and value propositions.
Supply Chain Dynamics and Cost Structure Pressures
The cost structure of M.2 SSDs is being redefined by raw material dynamics and the strategic behavior of vertically integrated assemblers. NAND flash constitutes the majority of the SSD bill of materials, meaning that contract price movements directly translate into OEM and end-product pricing shifts. Industry commentary in late 2025 emphasized that SSD prices faced significant upward pressure as NAND contract increases were passed through to downstream customers. Combined with reports that major suppliers had fully allocated 2026 production, this environment creates an acute tension between volume growth and margin preservation.
Vertically integrated participants are positioned to navigate this tension with greater flexibility, as they control critical stages from memory fabrication through controller integration and final assembly. This structure offers leverage in prioritizing high-margin applications, managing allocation during tight cycles, and accelerating time-to-market for next-generation platforms. Meanwhile, controller specialists and solution providers continue to play a vital enabling role, supplying controllers and complete M.2 SSD designs across PCIe Gen4 and Gen5 drives to multiple NAND vendors and brands. The interplay between memory suppliers, controller designers, and system-level assemblers is becoming increasingly strategic, with collaboration and co-engineering accelerating the arrival of differentiated products in a constrained environment.
Competitive Landscape and Leading Strategies
The competitive architecture of the M.2 SSD market is defined by a concentrated group of dominant players alongside a diverse set of specialists and enablers. Market concentration remains high, with the top three firms holding a combined share exceeding half of total revenue and the top five capturing more than four-fifths. This concentration reflects the structural advantages of scale, vertical integration, and deep relationships with OEM and enterprise customers. Yet the landscape is not static; differentiation is increasingly determined by how companies balance performance leadership, capacity innovation, form factor versatility, and ecosystem alignment.
Samsung and SK hynix stand out as vertically integrated Korean manufacturers with broad exposure across consumer and enterprise segments. Samsung leverages proprietary V-NAND technology and a comprehensive portfolio spanning high-performance consumer drives and enterprise PCIe Gen5 M.2 solutions, including compact form factors tailored for AI applications. SK hynix, including its Solidigm brand, supplies M.2 SSDs across multiple use cases, with Solidigm placing particular emphasis on high-capacity client and data center M.2 NVMe drives that target enterprise-grade requirements. Both firms benefit from end-to-end control over key components, enabling them to optimize cost, performance, and supply continuity in a market where input constraints are acute.
Micron and Kingston reinforce the competitive depth of the segment with strong U.S. footprints and broad M.2 NVMe portfolios. Micron's Vertically integrated approach and the rollout of the 3610 series demonstrate a strategy of pushing advanced Gen5 QLC technology into mainstream and ultra-thin laptop segments across single-sided M.2 form factors. Kingston maintains a wide-reaching consumer and enterprise M.2 NVMe portfolio, active in high-capacity and performance solutions that serve diverse deployment scenarios. These players highlight the importance of aligning product breadth with segment-specific performance and endurance requirements.
PW Consulting
Regional strength and specialization further enrich the competitive spectrum. Kioxia and TEAMGROUP bring Japanese and Taiwanese expertise to bear, with Kioxia targeting mainstream PC OEMs through BG8 series client M.2 SSDs in multiple form factors and TEAMGROUP offering high-performance PCIe 5.0 NVMe options such as the NV10000 series. Western Digital, through its WD Black and SanDisk branding and the 2026 SANDISK Optimus rebrand, provides an extensive M.2 NVMe lineup covering gaming, creator, and professional applications. Phison operates as a leading controller designer and SSD solution provider, supplying controllers and complete M.2 SSD designs to multiple NAND vendors and brands, thereby acting as a critical enabler across the value chain. Virtium and Greenliant address the industrial and embedded niche with certified, ruggedized, and economical M.2 NVMe solutions, reflecting the growing demand for application-specific storage.
The market is evolving through a blend of consolidation at the top and differentiation at the edges. Incumbents are strengthening their moats via vertical integration, brand restructuring, and targeted form factor innovation for AI and compact systems. At the same time, opportunities are emerging for specialists who can deliver certified security features, cost-optimized embedded solutions, and controller-level expertise that de-risks customer development cycles. New entrants and sub-segment challengers are unlikely to dislodge the leaders through scale alone; instead, success will depend on precise alignment with supply chain realities, protocol transitions, and the rising demand for application-tailored performance and reliability.
Forward Trends and Strategic Horizons
Looking ahead over the next three to five years, the M.2 SSD market will likely be shaped by the continued mainstreaming of PCIe Gen5 and the concurrent refinement of form factor strategies. High-performance protocols will migrate from premium and enterprise-centric deployments into volume client platforms and compact edge devices, expanding the base of systems that demand next-generation throughput and low latency. This shift will reward manufacturers that can deliver competitive performance across a range of M.2 sizes without compromising thermal efficiency or cost viability. The emergence of multi-capacity, single-sided solutions in 2230, 2242, and 2280 formats indicates a trajectory toward more flexible design envelopes that accommodate thin-and-light laptops, handhelds, and AI-capable compact systems.
A second trend is the deepening segmentation between client, enterprise, and industrial/embedded storage requirements. As workloads diverge, one-size-fits-all propositions will lose traction. Enterprise and data center adjacent applications will prioritize sustained endurance, predictable latency, and ecosystem certifications, while client segments will balance performance, capacity, and price sensitivity. Industrial and embedded deployments will increasingly seek secure boot, ruggedness, and supply reliability, creating space for certified, application-specific drives. Organizations that design portfolios with clear segment logic and corresponding go-to-market narratives will be better positioned to capture margin and customer loyalty.
A third trend concerns the interplay of supply constraints, pricing volatility, and geopolitical complexity. If NAND availability remains tight and contract pricing elevated, the market will likely see sustained upward pressure on component costs and extended lead times, with implications for OEM planning and end-product pricing. At the same time, export controls and trade friction will continue to influence sourcing strategies, encouraging regional diversification, multi-supplier risk management, and inventory buffering for critical programs. Potential risks include sudden shifts in demand intensity as AI capital expenditure cycles adjust, technology transitions that outpace customer qualification timelines, and margin erosion if pricing power does not keep pace with input cost escalation. Navigating this environment will require disciplined roadmap planning, scenario-aware inventory strategies, and close coordination across the memory, controller, and system integration layers.
Strategic Actions for Decision-Makers
For manufacturers and solution providers, the immediate priority is to align product roadmaps with protocol transitions and form factor flexibility while safeguarding supply continuity. Investing in controller and SSD design collaborations, securing early allocations for next-generation NAND, and developing clear segment-specific value propositions can help convert market momentum into defensible market share. Companies should also evaluate platform-level co-engineering opportunities with OEM and enterprise customers to shorten qualification cycles and lock in design wins ahead of volume ramps.
For investors, the market offers attractive growth signals but demands rigorous evaluation of vertical integration, allocation resilience, and segment exposure. Favor companies that demonstrate control over critical components, diversified customer bases, and differentiated positioning in high-growth subsegments such as AI-adjacent compact storage and certified industrial/embedded solutions. Monitor margin trajectories, lead time trends, and branding or portfolio restructuring as leading indicators of how well firms are adapting to pricing volatility and demand shifts.
Solid State Drive (SSD) Market
For procurement and supply chain leaders, the emphasis should be on scenario planning and supplier diversification. Establishing multi-region sourcing options, qualifying alternative controllers and form factors where feasible, and building buffer strategies for mission-critical programs can reduce exposure to sudden price spikes and extended lead times. Engaging with suppliers early to align on capacity commitments and roadmap timing will improve visibility and enable more predictable program execution. For stakeholders seeking detailed, segment-level data and customized strategic recommendations, the full research report provides the granular breakdowns and forward-looking models needed to translate these dynamics into actionable plans.
For detailed analysis of this topic, please visit the official page: Worldwide M.2 Interface Solid State Drive Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


