



Luxury Cosmetics Packaging: 5.18% CAGR Reshaping Value and Design

Global Luxury Cosmetics Packaging Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The worldwide luxury cosmetics packaging market has demonstrated remarkable resilience and steady expansion over the past half-decade. Valued at approximately USD 5.8 billion in 2020, the market reached USD 7.45 billion by 2025, reflecting a compound annual growth rate of 5.18 percent through the forecast horizon extending to 2032. This trajectory translates to a projected valuation exceeding USD 10.6 billion by the end of the forecast period. The growth pattern reveals consistent upward momentum, with notable acceleration expected from 2029 onward as regulatory frameworks mature and consumer preferences continue to shift toward premiumized, sustainability-aligned offerings.
At the macro level, the market structure remains moderately fragmented, with the top three players holding an 18.4 percent share and the top five collectively commanding 27.15 percent. This concentration level indicates a competitive landscape where no single entity dominates outright, allowing specialized manufacturers to thrive alongside broad-line suppliers. The moderate fragmentation creates both pressure and opportunity: established players must continuously differentiate through design, material innovation, and service capabilities, while agile newcomers can capture niches by addressing unmet needs in specific application categories or regional markets.
Several structural challenges currently define the industry's inflection point. First, the regulatory environment is undergoing its most significant transformation in decades, particularly in Europe, where the Packaging and Packaging Waste Regulation entered into force in early 2025 and will apply from mid-2026. This framework introduces mandatory recyclability criteria, minimum post-consumer recycled content thresholds for certain plastic formats, and extended producer responsibility schemes with fees modulated by recyclability performance. For luxury cosmetics packaging, these requirements create a complex compliance landscape that demands proactive design-for-recycling strategies rather than reactive adjustments.
Second, raw material dynamics are introducing cost volatility and sourcing complexities. Glass continues to serve as a cornerstone material for high-end packaging due to its barrier properties, aesthetic versatility, and recyclability profile, with the broader cosmetic glass packaging segment reflecting substantial value concentration. Simultaneously, premium plastics and metal formats face mounting pressure from both regulatory cost mechanisms and consumer expectations around sustainability. Italy's planned plastic tax, scheduled for implementation in 2026, exemplifies the national-level fiscal measures that are reshaping material economics across the value chain.
Third, the tension between luxury brand aesthetics and sustainable material performance remains a persistent challenge. Premium positioning historically relied on visual and tactile cues—weight, transparency, metallic finishes, intricate molding—that can conflict with lightweighting, mono-material conversion, or PCR integration mandates. Brands and packaging suppliers must navigate this balance carefully, as compromising perceived quality can undermine the premium value proposition that drives margin premiums in the first place.
Key Drivers Reshaping the Market
Technological Innovation and Material Science Breakthroughs
Material science and dispensing technology are driving the most consequential product-level changes in the market. Airless packaging systems have evolved significantly, offering improved product preservation, reduced contamination risk, and enhanced consumer dosing precision—attributes that resonate strongly with high-end skincare and fragrance applications. Several leading suppliers have expanded their airless portfolios with lines specifically engineered for recyclability and premium performance, targeting the 15 to 50 milliliter range that dominates prestige skincare formats.
Parallel advances in mono-material design and post-consumer recycled content integration are enabling brands to meet sustainability targets without abandoning premium aesthetics. Mono-material structures simplify end-of-life recycling streams and align with design-for-recycling criteria, while PCR incorporation allows manufacturers to communicate tangible sustainability credentials. The challenge lies in maintaining visual and tactile quality: advanced coatings, textured substrates, and refined molding techniques are increasingly deployed to preserve the sensory experience that luxury consumers expect. Specialty label providers have also contributed by introducing textured substrates and sustainable material options that enhance brand differentiation on primary and secondary packaging surfaces.
Regulatory Pressure and Compliance-Driven Redesign
Regulatory momentum represents both a constraint and a catalyst for innovation. The EU Packaging and Packaging Waste Regulation establishes a comprehensive framework that will influence packaging formulations, labeling, and end-of-life management well into the 2030s. Extended producer responsibility obligations with fee modulation tied to recyclability grades create a direct financial incentive for designers to prioritize recyclable architectures from the outset. Standardized labeling requirements further push toward transparency and consumer education, which can become a brand advantage when executed thoughtfully.
Cosmetics Brushes Market
National-level measures add additional layers of complexity. Plastic packaging taxes and modulated EPR fees are being implemented or considered across multiple jurisdictions, altering the cost calculus for plastic-intensive formats. These measures disproportionately affect non-recyclable or multi-material constructions, accelerating the shift toward mono-material solutions and higher PCR content. For market participants, the strategic implication is clear: regulatory compliance is no longer a checkbox exercise but a core design parameter that influences material selection, supplier partnerships, and total cost of ownership.
Demand-Side Evolution: Consumers and Brand Strategies
Consumer expectations continue to drive premiumization, but the definition of luxury is expanding. High-income consumers increasingly evaluate sustainability credentials alongside craftsmanship, heritage, and sensory appeal. The rise of refillable and reusable formats reflects this shift: consumers are willing to accept slightly different usage mechanics if the design communicates environmental responsibility without sacrificing perceived quality. Refillable architectures also create recurring engagement opportunities, strengthening brand loyalty and enabling lifetime value expansion.
PW Consulting
Brand strategies are adapting accordingly. Prestige houses are investing more heavily in packaging that tells a coherent sustainability story, recognizing that packaging serves as a tangible touchpoint for brand values. This dynamic elevates the importance of packaging suppliers that can deliver customizable, high-end solutions with verified material credentials and transparent lifecycle narratives. The demand for bespoke designs remains strong, particularly in fragrance and color cosmetics, where packaging function as brand signature.
Supply Chain Reconfiguration and Cost Structure Shifts
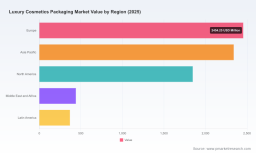
Supply chain dynamics are undergoing recalibration as manufacturers balance cost efficiency with resilience and compliance. Regional concentration patterns show Europe and Asia Pacific as the largest value pools, followed by North America, with Middle East and Africa and Latin America representing smaller but growing contributions. This geographic distribution encourages suppliers to develop regional production and sourcing strategies that reduce logistics exposure while meeting local regulatory expectations.
Cost structures are being reshaped by material taxes, recycled content premiums, and the capital investment required for recycling-compatible manufacturing processes. At the same time, consolidation activity is intensifying as larger players acquire specialized capabilities to expand their premium portfolios. A notable acquisition saw a packaging group strengthen its folding carton offerings for perfumery and cosmetics, illustrating how inorganic growth is being used to secure high-end presentation capabilities. These moves signal a market where integrated capabilities—from primary packaging to secondary presentation—are increasingly valued.
Competitive Landscape and Leading Strategies
Incumbent Strengths and Differentiation Pathways
The competitive field features a diverse mix of multinational suppliers and regional specialists, each pursuing distinct differentiation strategies. AptarGroup has built a strong position around dispensing systems, airless packaging, pumps, and closures designed for premium skincare, fragrance, and color cosmetics. The company's emphasis on sustainable and customizable high-end solutions aligns with the dual imperatives of performance and compliance, and recent portfolio expansions in Latin America reflect a deliberate push to capture growth in emerging premium segments.
Albéa Group stands out as a global leader in cosmetic tubes, compacts, lipsticks, and jars, with a particularly strong footprint in luxury and prestige beauty packaging. Its focus on mono-material structures, PCR integration, and refillable designs positions it well for the regulatory and consumer trends reshaping the market. Gerresheimer AG leverages its heritage in high-quality glass and plastic packaging to serve luxury cosmetics and skincare, offering premium jars, bottles, and vials that capitalize on glass's enduring appeal for high-end formulations. Amcor plc brings a broad capability set spanning flexible and rigid packaging with premium finishes, emphasizing sustainable materials and high-barrier properties that suit luxury cosmetics applications.
Specialist players are carving out niches through focused expertise. Silgan Holdings supplies metal and plastic containers, closures, and dispensing systems suitable for luxury personal care, while HCP Packaging concentrates on luxury color cosmetics packaging including compacts, lipsticks, jars, and brushes for high-end global brands. Quadpack emphasizes sustainable and premium packaging for beauty, including airless systems, jars, and bottles for luxury skincare and makeup. Regional specialists such as Lumson and Baralan in Italy provide premium dispensing systems, airless packaging, and glass and plastic solutions that leverage the country's strong design heritage. Meanwhile, U.S.-based players like World Wide Packaging, FusionPKG, and Cosmopak serve prestige brands with innovative and custom luxury packaging components, focusing on stock and bespoke solutions for high-end applications.
Market Evolution: Consolidation, Differentiation, and New Entrants
The market is evolving along three parallel tracks. Consolidation is accelerating as larger suppliers acquire specialized assets to deepen their premium capabilities, expand geographic reach, or strengthen material and format portfolios. These acquisitions tend to target companies with proven design expertise, proprietary dispensing technologies, or strong relationships with prestige brands. The result is a landscape where integrated suppliers increasingly offer end-to-end solutions spanning primary packaging, dispensing mechanisms, closures, and secondary presentation elements.
Differentiation is intensifying around sustainability credentials, customization depth, and application-specific engineering. Suppliers that can demonstrate verifiable recyclability, PCR content, mono-material architectures, or refillable systems gain a competitive edge, particularly when paired with the design sophistication that luxury brands demand. Customization remains a key battleground: bespoke molds, exclusive finishes, and tailored dispensing experiences allow brands to create distinctive packaging signatures that reinforce premium positioning.
New entrants and regional specialists continue to find opportunities by addressing underserved niches or geographies. The moderate market concentration leaves space for agile players that can deliver high-quality, design-forward solutions with shorter lead times or specialized material expertise. At the same time, the regulatory environment raises the barrier to entry for low-cost, non-compliant offerings, effectively filtering the market toward participants that can invest in compliant design and material innovation.
Future Trends: 2026 to 2032 Outlook
Sustainability as a Design Baseline, Not a Differentiator
Over the next three to five years, sustainability will transition from a competitive differentiator to a baseline requirement. The cascading effect of EU regulations, national plastic taxes, EPR fee modulation, and PCR content mandates will make recyclable, mono-material, and recycled-content packaging the default expectation for luxury cosmetics. Brands and suppliers that treat sustainability as an afterthought will face rising compliance costs and potential market access limitations. Those that integrate these requirements into core design processes will unlock efficiencies in material sourcing, waste management, and brand messaging. Commercial opportunities will emerge for suppliers offering verified PCR content, design-for-recycling consultation, and refillable system architectures that balance convenience with environmental performance.
Premiumization Through Intelligent and Refined Formats
Luxury consumers will continue to reward packaging that enhances the product experience through refined engineering rather than sheer material volume. Airless systems, precision dispensing mechanisms, and packaging that preserves product integrity will gain prominence, especially in skincare and fragrance categories. Intelligent features—such as tamper evidence, dosage control, and interactive elements that communicate usage guidance or brand stories—may become more prevalent as brands seek to justify premium price points through functional value. The opportunity lies in integrating these features without compromising recyclability or inflating material costs unnecessarily. Suppliers that can deliver sophisticated dispensing and preservation performance within recyclable or mono-material frameworks will capture increasing share.
Luxury Packaging Market
Regional Growth Divergence and Supply Chain Localization
Regional growth patterns will diverge as local regulatory regimes, consumer income trends, and brand distribution strategies shape demand. Europe's regulatory leadership will continue to influence global design standards, while Asia Pacific's expanding premium beauty market will drive volume growth and encourage localized packaging solutions. Latin America and Middle East and Africa represent smaller but increasingly relevant opportunities, particularly as international prestige brands expand their footprints and local consumers adopt premium consumption patterns. Supply chain localization will become more pronounced as manufacturers seek to reduce logistics exposure, respond faster to regional regulatory changes, and align material sourcing with local recycling infrastructure. This trend favors suppliers with multi-region production capabilities and the flexibility to adapt material specifications to regional compliance environments.
Risks and Uncertainties
Several uncertainties could alter the trajectory. Regulatory implementation timelines and enforcement intensity may vary across jurisdictions, creating compliance complexity for globally distributed brands. Material cost volatility, particularly for recycled content and specialty glass, could pressure margins if supply does not keep pace with demand. Consumer willingness to accept material substitutions or refillable formats may diverge from stated preferences, requiring careful testing and brand communication. Finally, rapid technological change in recycling infrastructure and waste management could shift what counts as "recyclable" in practice, requiring ongoing design adaptation.
Strategic Recommendations for Decision-Makers
For Manufacturers and Packaging Suppliers
Embed design-for-recycling and PCR integration into product development cycles now, rather than treating them as retrofit requirements. Invest in mono-material architectures and airless or dispensing technologies that meet both performance and compliance standards. Build verifiable material credentialing and transparent lifecycle narratives that luxury brands can use in consumer communication. Monitor regulatory developments closely, particularly around PCR thresholds and recyclability grading, and align product roadmaps with the 2030 horizon when several mandates will take full effect.
For Investors
Evaluate targets based on their ability to deliver premium aesthetics alongside sustainable material performance, as this dual capability will command pricing power and customer loyalty. Prioritize companies with strong relationships in skincare and fragrance segments, where airless systems and glass formats drive value, and those with proven customization and bespoke design capabilities. Assess geographic balance: suppliers with exposure to Europe's regulatory-driven redesign and Asia Pacific's premium growth offer complementary risk-return profiles. Watch for consolidation opportunities where specialized design or dispensing technologies can be integrated into broader portfolios.
For Procurement and Brand Teams
Treat packaging suppliers as strategic partners rather than transactional vendors. Develop joint roadmaps that align material selection, dispensing technology, and sustainability credentials with brand positioning and regulatory timelines. Prioritize suppliers that can provide transparent material data, recyclability documentation, and flexible customization without compromising lead times. Explore refillable and reuse formats where brand architecture and consumer behavior support recurring engagement, and pilot these formats in controlled segments before scaling. Ensure packaging decisions reflect total cost of ownership, including compliance risk, recyclability fees, and brand perception impact, not just unit price.
Navigating this market successfully requires detailed, segment-specific intelligence that connects macro trends to actionable decisions across materials, applications, regions, and company strategies. Comprehensive analysis with granular data on market sizing, competitive positioning, regulatory timelines, and material dynamics can help decision-makers prioritize investments and mitigate risk with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Luxury Cosmetics Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


