



LFP Cathode Material Market: Why 19.24% CAGR Through 2032 Changes Everything

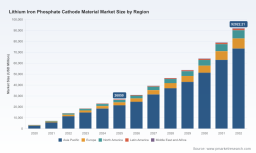
Worldwide Lithium Iron Phosphate Cathode Material Market: Strategic Trends and Commercial Opportunities
Market Overview: Scale, Momentum, and Critical Inflection Points
The worldwide lithium iron phosphate (LFP) cathode material market has transitioned from a regional specialty to a central pillar of the global battery supply chain. Valued at approximately 3,480 million USD in 2020, the market expanded to 26,850 million USD by 2025, reflecting an aggressive compound annual growth rate of 19.24% through 2032. By the end of the forecast window, total revenue is projected to approach 92,022 million USD, reshaping how automakers, energy developers, and industrial manufacturers approach cost structures, performance trade-offs, and sourcing strategies.
This trajectory is not merely a reflection of broader battery demand. It signals a structural shift in chemistry preference, where LFP has captured meaningful share from nickel-cobalt-based alternatives in applications that prioritize cycle life, thermal stability, and manufacturing economics over raw gravimetric energy density. The market’s expansion has been broad-based across segments, with commercial momentum concentrated in regions that host integrated battery manufacturing, rapid EV deployment, and large-scale stationary storage projects.
Despite the clear growth narrative, the industry sits at a strategic inflection point defined by three overlapping challenges. First, suppliers must navigate a volatile raw material environment. Lithium carbonate prices, which languished near 59,000 CNY/ton in mid-2025, rebounded sharply and surpassed 130,000 CNY/ton by year-end, directly pressuring cathode input costs and squeezing margins where long-term pricing agreements lag spot market movement. Second, geographic policy asymmetry is fragmenting supply chains. Export controls introduced in late 2025 on high-density, high-capacity LFP cathode materials and associated production technologies have tightened the movement of advanced manufacturing know-how, encouraging parallel development efforts outside China and altering previously efficient cross-border flows. Third, pricing pressure in key destination markets is intensifying. In the United States, LFP cathode material pricing reached roughly 12,799 USD/MT in the third quarter of 2025 before softening, as cell makers prioritized output and lithium salt dynamics shifted. For cathode producers, the implication is clear: volume growth alone will not protect profitability. Competitive advantage will increasingly depend on cost discipline, process efficiency, and the ability to align product specifications with regional regulatory and performance requirements.
Key Drivers Reshaping Demand, Supply, and Competitive Advantage
Technology innovation remains the most potent catalyst for LFP cathode market expansion. The standard LFP chemistry has matured into a highly reliable baseline, but the real strategic action now centers on lithium manganese iron phosphate (LMFP) and process engineering that pushes compacted density and gram capacity higher. These advancements matter because they allow manufacturers to retain LFP’s cost and safety benefits while improving energy density for mobility applications and reducing material intensity per kilowatt-hour. Companies actively refining one-pot synthesis routes, continuous production workflows, and more consistent particle engineering are building a measurable edge in throughput quality and capital efficiency. The broader trend is toward cathode architectures that align more closely with cell-level design optimization rather than treating cathode material as a commoditized input.
Policy and regulatory dynamics are simultaneously restructuring where capacity is built and how trade flows. Chinese export restrictions on high-density LFP and LMFP cathode production technologies have elevated the strategic importance of non-Chinese manufacturing capabilities. At the same time, tariff exposure on Chinese LFP cells in the United States has reinforced the case for re-shoring cathode active material production, especially as battery energy storage system demand accelerates. These policy shifts are not simply barriers; they are allocation mechanisms. They create incentives for localized supply, technology transfer partnerships, and regional qualification cycles that can become durable sources of advantage for producers who move early. In effect, the market is moving from a globally integrated model to a more multi-node architecture, where regional compliance, customer proximity, and certification readiness carry increasing commercial weight.
Demand-side behavior is another critical driver. Electric vehicles continue to anchor the largest share of LFP cathode consumption, but the growth profile is broadening. Energy storage systems are becoming an increasingly strategic volume pool because stationary applications tolerate LFP’s heavier pack weight while rewarding long service life, safety, and total cost of ownership. In consumer electronics and industrial use cases, LFP adoption remains more selective, yet it offers manufacturers a predictable, lower-volatility chemistry for specific performance envelopes. More importantly, procurement behavior is changing. Buyers are less willing to accept undifferentiated supply at volatile spot prices. They are seeking qualified suppliers with stable quality, reliable delivery, and transparent cost structures. This shift tilts bargaining power toward producers who can demonstrate process consistency, capacity credibility, and regional responsiveness.
Worldwide Cathode and Precursor Materials Market
Finally, cost structure and supply chain strategy are being redefined together. LFP cathode economics are closely tied to lithium feedstock exposure, precursor availability, and manufacturing yield. When lithium prices spike, margin resilience depends on how efficiently a producer can convert inputs, manage inventory cycles, and negotiate customer contracts. This environment rewards manufacturers with scale, backward integration options, or process technologies that reduce waste and energy intensity. It also elevates the importance of partnerships across the value chain, including cathode producers, cell manufacturers, and end-market customers who are willing to coordinate product roadmaps. In this setting, cost leadership is no longer purely about input price timing; it is about structural efficiency and supply chain coordination.
Competitive Landscape: Positioning, Differentiation, and Structuring Shifts
The competitive landscape is defined by a concentration of established producers, a growing set of technology-focused entrants, and an expanding group of regional players seeking to capture policy-driven localization opportunities. Several large-scale manufacturers in the Asia-Pacific region have built strong positions through high-volume output, extensive customer networks, and deep familiarity with battery cell qualification cycles. Their strategic value lies in proven scale, repeatability, and the ability to support EV and energy storage programs with consistent supply. For global battery manufacturers, these producers often serve as core-volume partners, which gives them leverage in customer relationships but also exposes them to cyclical pricing pressure and geopolitical trade dynamics.
Differentiation is increasingly visible along three dimensions: process innovation, regional footprint, and application specialization. Technology-oriented producers are pursuing proprietary synthesis routes and continuous manufacturing models that promise better control over particle morphology, energy consumption, and quality consistency. Where these approaches translate into lower cost per useful ton or superior electrochemical consistency, they become meaningful differentiators rather than marketing claims. At the same time, regional diversification is emerging as a distinct strategic posture. Stakeholders outside China are building capacity not only to serve domestic markets but also to reduce exposure to cross-border constraints and align with customer requirements tied to local content, certification, and logistics resilience.
Recent developments illustrate how these strategies are being executed. One Canadian producer has advanced detailed engineering and equipment procurement for an 800 tpa LFP cathode capacity expansion in Quebec, signaling a focus on scaling proprietary process technology in North America. In South Korea, POSCO Future M moved decisively by approving investment in an LFP cathode plant with up to 50,000 tons of annual capacity and converting selected existing Pohang lines to begin LFP supply in the second half of 2026. The same effort expanded through a joint venture with CNGR and FINO to build a 50,000-ton facility in Pohang, with site construction scheduled for 2026. These moves highlight a broader pattern: incumbents with existing chemical or materials expertise are using brownfield conversion, partnerships, and targeted greenfield capacity to enter or scale LFP offerings with lower timing risk than fully organic standalone builds.
The market is therefore evolving through a blend of consolidation, differentiation, and new entry. On one side, scale players are likely to continue consolidating volume positions and tightening relationships with major cell customers. On the other, chemically adjacent companies, regional materials suppliers, and technology specialists are entering with narrower but higher-value propositions. The result is a market that is not simply fragmenting into many small competitors, but rather stratifying by value proposition: high-volume cost leaders, technology-differentiated producers, and regionally anchored suppliers positioned for policy and customer proximity advantages. Over the next several years, competitive success will depend less on the sheer announcement of capacity and more on execution quality, qualification speed, and the ability to align product specifications with regional demand realities.
Forward Outlook: Three Trends Defining the Next Three to Five Years
The first trend is the continued regionalization of LFP cathode supply. As export controls, tariff exposure, and customer localization preferences shape procurement decisions, production capacity is expected to become more geographically distributed. This does not eliminate global trade, but it increases the value of regionally qualified supply bases. For businesses, that means sourcing strategies will need to account for certification timelines, technical support proximity, and the risk of policy shifts that can disrupt previously efficient flows.
The second trend is the progressive refinement of LFP and LMFP product portfolios. Demand will increasingly reward cathodes that offer an optimized balance of energy density, cycle durability, and manufacturing practicality. Standard LFP will remain essential for cost-driven applications, but LMFP and higher-performance LFP variants are likely to capture growing attention in automotive and storage use cases where incremental energy gains and specification flexibility improve total system economics. Companies that can produce differentiated grades with consistent quality will be better positioned to command pricing and stickier customer relationships.
The third trend is cost structure competitiveness becoming a strategic moat rather than a temporary advantage. Lithium feedstock volatility and evolving manufacturing economics will continue to test margins. The producers most likely to sustain profitability will be those that combine scale, efficient process design, inventory and contract management, and the flexibility to serve both high-volume baseline demand and specialty-grade needs. At the same time, risk remains. Policy uncertainty, technology export constraints, demand pacing in certain EV segments, and commodity price swings can all alter the speed and distribution of value capture. Planning will need to treat these variables as structural inputs, not temporary noise.
Strategic Actions for Decision-Makers
For cathode and battery materials manufacturers, the priority is to convert capacity plans into execution credibility. That means aligning process choices with customer qualification requirements, securing feedstock resilience, and building product lines that span both cost-sensitive baseline demand and higher-specification opportunities. Suppliers that can demonstrate stable quality, regional responsiveness, and transparent cost logic will be better placed to win long-term contracts in a more fragmented trade environment.
Lithium Hexafluorophosphate Market
For investors, the key is to distinguish announced capacity from commercially viable capacity. The most valuable opportunities are likely tied to producers with credible technology differentiation, disciplined cost structures, and clear regional positioning that matches policy incentives and customer demand. Capital allocation should weigh not only tonnage targets but also process maturity, qualification readiness, and exposure to lithium input volatility and trade constraints.
PW Consulting
For procurement and sourcing leaders, resilience should take precedence over short-term spot optimization. Diversifying qualified suppliers across regions, securing visibility into production roadmaps, and aligning specifications with application needs can reduce vulnerability to pricing spikes and policy-driven supply disruptions. As LFP cathode markets mature, purchasing advantage will increasingly come from strategic supplier relationships and forward visibility rather than transactional bargaining alone.
For organizations seeking deeper segment data, regional breakdowns, cost-model scenarios, and company-level benchmarking, the full PW Consulting research report provides a more detailed analytical framework to support planning, sourcing, and investment decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Lithium Iron Phosphate Cathode Material Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


