



The Real Drivers Behind Bismuth Ingot Market's 5.45% CAGR Trajectory to 2032

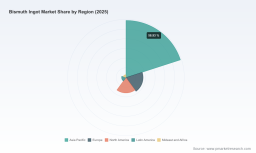
Strategic Trends & Commercial Opportunities in the Worldwide Bismuth Ingot Market
Market Snapshot: Growth Dynamics and Structural Constraints
The global bismuth ingot market has entered a phase of sustained expansion, driven by resilient demand across specialty alloys, pharmaceuticals, and high-purity industrial applications. With a compound annual growth rate of 5.45% projected through 2032, the sector is transitioning from a niche minor-metal segment to a strategically significant component of advanced manufacturing supply chains. This trajectory reflects not only incremental volume growth but also an upward recalibration of value, as producers capture premiums for higher purity grades and more consistent metal specification.
Despite the optimistic forward curve, the industry operates under structural constraints that define both its near-term volatility and its long-term evolution. One of the most defining characteristics of the market is its byproduct dependency. Bismuth is overwhelmingly recovered from lead, copper, tungsten, or zinc processing streams rather than from primary extraction dedicated solely to bismuth. This means supply responsiveness is inherently lagged and partially decoupled from downstream demand signals. Producers cannot simply commission new capacity to chase price rallies; additional volumes must align with broader smelting economics and base-metal market conditions.
A second structural challenge lies in geographic concentration and regulatory friction. Production is heavily clustered in regions where lead and nonferrous smelting infrastructure is mature, and where the mineral endowment supports integrated metal recovery. Recent policy actions in key producing jurisdictions have added a new layer of complexity. Export controls and licensing requirements on bismuth metal and related products have tightened global availability, contributed to price volatility, and forced downstream buyers to rethink procurement logic. The combination of concentrated supply, policy-driven disruption, and byproduct-linked production creates an environment where inventory management, qualification cycles, and substitution readiness become critical operational disciplines.
A third challenge is the widening gap between standard and high-purity supply. Demand for controlled-purity bismuth ingots is accelerating in electronics, semiconductor-adjacent processes, and specialty catalysts, yet the metallurgy to reach and validate elevated purity grades is not uniformly available across smelters and refiners. This creates a bifurcated market. Lower-specification ingots may move through commodity-oriented channels, while high-purity material often requires traceability, process validation, and long-term offtake alignment. The result is a market where commercial success is increasingly tied to technical capability and qualification infrastructure rather than volume alone.
Key Drivers Reshaping the Bismuth Ingot Landscape
Technological Innovation in Refining and Purity Control
Metallurgical progress is one of the clearest value-creation vectors in the bismuth ingot market. Test work and process optimization efforts have demonstrated that concentrated leachates can be transformed into high-purity ingots through integrated leaching, cementation, and pyrometallurgical refining pathways such as liquation, sulphuration, and chlorination. These process refinements matter commercially because they can improve yield consistency, reduce equipment footprint, and lower the unit cost of reaching target purity.
For downstream users, this translates into a more reliable pathway to 4N-grade and above material without relying solely on legacy refining operations that were designed around older product specifications. In high-value applications, small improvements in purity control can be the difference between qualification approval and procurement rejection. The broader implication is that refining competence is becoming a strategic asset. Producers that can demonstrate repeatable purity outcomes, supported by metallurgical validation and controlled process parameters, are better positioned to serve electronics, pharmaceutical-adjacent users, and specialty alloy makers that require specification integrity rather than occasional bulk availability.
Policy, Trade Controls, and the Reorientation of Procurement
Regulatory developments have shifted bismuth from a relatively stable minor metal into a material with explicit strategic trade sensitivity. Export controls on bismuth metal and products, introduced in response to broader tariff dynamics, have influenced global supply tightness and price behavior. In parallel, defense-related procurement activity has surfaced as a notable demand signal, with government agencies issuing tenders for high-purity bismuth in slab or ingot form for stockpile purposes.
These developments do more than move prices. They change the incentives for supply chain design. Buyers that previously treated bismuth as a readily available minor commodity are now factoring in geographic diversification, supplier qualification, and contractual flexibility. At the same time, the concentration of refinery production in one dominant producing region amplifies the effects of policy shifts. When a major share of global refined material flows from a limited set of countries, trade frictions can quickly propagate into lead times, price discovery, and inventory strategy.
For executives, the strategic takeaway is that regulatory risk has become a procurement variable, not just a compliance concern. Flexible sourcing, dual-supplier strategies, and reserves planning are increasingly relevant, especially for applications where substitution is technically constrained or where qualification cycles are long.
Demand-Side Shifts in Specialty Alloys, Pharmaceuticals, and Electronics
Demand growth is being pushed by a cluster of application trends rather than a single volume driver. In fusible alloys and solders, bismuth continues to serve as a functional substitute in formulations where lower melting points, density characteristics, or environmental constraints matter. In pharmaceuticals and related chemical applications, bismuth-based compounds and metal inputs remain embedded in product lines that depend on controlled specifications and consistent supply. In pigments, electronics, and specialty metallurgical uses, the need for purity assurance is intensifying as downstream processes become more sensitive to impurity profiles.
What makes this demand environment distinctive is that it rewards reliability and specification control more than it rewards cheap availability. A pharmaceutical or high-purity electronics supply chain does not respond in the same way as a generic alloy market. Qualification lead times, documentation, lot consistency, and technical support all influence purchasing decisions. As a result, application growth in higher-value segments is strengthening the commercial logic of dedicated high-purity production and long-term customer relationships, even when total tonnage remains comparatively modest relative to base metals.
Supply Chain Structure and Cost Dynamics
Cost and availability in the bismuth ingot market are shaped less by standalone mining economics than by the health and configuration of base-metal smelting. Because bismuth is primarily a byproduct, its supply is tied to the operational intensity of lead, copper, tungsten, and zinc circuits. This has two practical effects. First, bismuth availability can expand or contract depending on smelting throughput and concentrate processing decisions that are made for reasons unrelated to bismuth alone. Second, cost structures are influenced by the complexity of separation and refining, especially when higher purity grades are required.
Price behavior has also reflected this structural reality. Recent annual price levels have reached historically elevated averages, and warehouse pricing in key hubs has shown sharp intermittent peaks. Such movements indicate that the market is not only reacting to demand but also absorbing the effects of supply concentration, policy disruption, and the premium attached to specification-sensitive material. For producers, this creates an opportunity to capture value through purity differentiation and service reliability. For buyers, it underscores the importance of visibility into refining capacity, inventory positions, and the metallurgical route used to produce the ingots they purchase.
Competitive Landscape and Leadership Strategies
The competitive field in the bismuth ingot market is defined by a mix of integrated smelters, specialty refiners, and distributors with strong technical and application orientation. Concentration is meaningful, with a relatively small group of players accounting for a substantial share of market activity. This structure favors companies that combine production competence with application knowledge, purity control, and the ability to serve complex procurement requirements.
A clear pattern in the landscape is the divergence between byproduct-oriented smelting operations and more specialized minor-metal producers. Companies that recover bismuth from lead smelting or from battery-related recycling streams can benefit from existing infrastructure and scale, particularly when bismuth is packaged for alloys, industrial uses, and pharmaceutical-adjacent applications. Their strategic advantage often lies in established processing routes and the ability to supply material that aligns with ingot form requirements at commercial scale.
At the same time, high-purity specialists are positioning around purity assurance, traceability, and application-specific service. These producers focus on controlled grade architecture, working with customers in electronics, thin-film deposition, specialty alloys, and catalytic applications where specification integrity is paramount. Their differentiation typically comes from process discipline, lot documentation, custom formulations, and the capacity to bridge laboratory demand with bulk supply.
Another important evolution is the emergence of project-stage producers aiming for vertically integrated operations. One notable direction is the development of projects intended to produce high-purity bismuth ingots alongside cobalt, gold, and copper-related outputs. Recent milestones in these initiatives have included metallurgical test work validating 4N bismuth ingot production and progress on site control for hydrometallurgical processing. If such projects advance through construction decisions, they could add supply diversification and reinforce the strategic relevance of non-China refining outside traditional byproduct channels. For the market overall, these developments matter because they could introduce new sourcing geographies, new purity pathways, and additional optionality for buyers seeking to reduce concentration risk.
The competitive trend to watch is therefore not simply consolidation, but functional specialization. Some players will continue to compete on volume and integrated smelting economics. Others will compete on purity, qualification support, and reliability for high-specification buyers. The most strategically resilient firms are likely to be those that can navigate both worlds: producing material at meaningful scale while maintaining the technical credibility to serve demanding end-use segments.
Indium Market
Forward Outlook: Three Trends Shaping the Next 3-5 Years
The first likely trend is widening premium differentiation by purity and application readiness. As more customers in electronics, pharmaceuticals, catalysts, and specialty materials require documented purity and lot consistency, the market will increasingly separate standard commercial ingots from validated high-purity supply. This creates commercial opportunities for producers that can formalize quality systems, support qualification processes, and maintain stable grade control. It also raises the cost of entry for new suppliers targeting higher-value segments, since metallurgical competence and customer validation will be decisive.
Solar Ingot Wafer Market
The second trend is continued supply-side reconfiguration driven by policy and byproduct economics. Because bismuth availability is linked both to smelting dynamics and to trade policy, buyers should expect periodic tightening and price volatility rather than smooth, linear supply growth. At the same time, interest in refining diversification and project-stage development may gradually broaden geographic supply. The commercial implication is that procurement strategies will need to incorporate redundancy, qualification lead times, and scenario planning for regulatory change, especially where bismuth has no easy substitute.
The third trend is the growing strategic relevance of bismuth in resilience-focused procurement. Strong price signals and stockpiling interest point to recognition of bismuth as a material with both industrial and strategic value. For commercial players, this can mean stronger negotiating leverage for qualified producers, but also higher inventory expectations from some buyers. The uncertainty lies in the pace and direction of policy evolution, the timing of new project capacity, and whether base-metal smelting conditions remain favorable for consistent byproduct recovery. These variables will shape whether the market remains tight and premium-driven or opens up as new supply matures.
PW Consulting
Actionable Recommendations for Decision-Makers
For manufacturers and application developers, the priority is to treat purity specification and supplier qualification as core business variables rather than administrative requirements. Where applications depend on tight impurity control, building longer qualification cycles into planning, requesting documented metallurgical routes, and securing multi-source options can reduce exposure to supply shock and quality variability. Aligning product design with available purity grades can also unlock more stable sourcing and reduce substitution friction.
For investors and corporate development teams, the strategic opportunity lies in identifying where value is being created along the bismuth value chain. Premium capture is increasingly tied to refining capability, purity assurance, and access to demand segments that tolerate less substitution. Projects and producers that can demonstrate validated high-purity output, diversified supply logic, or strong application-oriented service may offer more durable positioning than volume-only plays in a market shaped by byproduct constraints and trade sensitivity.
For procurement and supply chain leaders, the recommendation is to move from transactional buying to structured resilience planning. That means mapping exposure to concentrated supply, evaluating inventory and stockpiling options where substitution is limited, and negotiating contracts that account for purity variability and lead-time risk. In a market where prices can react sharply to policy shifts and refining constraints, visibility into the supply base becomes a competitive advantage in its own right.
Detailed segment-level sizing, purity-grade dynamics, regional exposure, and company-specific operating profiles can materially sharpen these decisions. For teams that need deeper granularity on demand composition, refining pathways, and competitive positioning, the full market research report provides the dissection required to translate these trends into company-specific action.
For detailed analysis of this topic, please visit the official page: Worldwide Bismuth Ingot Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


