



CLD NOx Analyzer Market: Why 4.96% CAGR and Regional Shifts Redefine Growth Basins

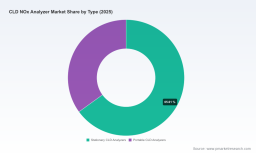
Global CLD NOx Analyzer Market: Strategic Trends, Competitive Dynamics, and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The worldwide market for chemiluminescence detection (CLD) nitrogen oxide analyzers has demonstrated resilient expansion over the past half-decade, reaching approximately USD 524.45 million in 2025. Following a period of moderate volatility between 2020 and 2023, the sector has stabilized and resumed a steady upward trajectory, with sales spanning USD 420.15 million in 2020 to the current baseline. Projections indicate continued growth through the forecast horizon, with revenues expected to approach USD 735.84 million by 2032, reflecting a compound annual growth rate of 4.96 percent. This expansion is not merely a function of incremental demand; it reflects the deepening integration of precision emission monitoring into regulatory compliance, industrial operations, and environmental stewardship frameworks across multiple geographies.
Despite the constructive demand backdrop, the CLD NOx analyzer market faces structural friction points that will shape competitive outcomes in the near term. The first challenge lies in balancing measurement sensitivity with operational robustness. Modern environmental and industrial mandates increasingly require detection at parts-per-billion and even parts-per-trillion levels, yet field-deployed systems must withstand harsh exhaust conditions, temperature fluctuations, and particulate-laden gas streams. Manufacturers that cannot reconcile laboratory-grade precision with ruggedized, low-maintenance field performance risk losing share to alternative sensing approaches or to competitors who have successfully engineered hybrid architectures.
A second tension emerges from the evolving regulatory patchwork. Compliance frameworks are tightening globally, but they do so at different speeds, with differing certification pathways, and often with ambiguous alignment between ambient air quality monitoring standards and continuous emissions monitoring requirements. Organizations deploying or procuring CLD systems must navigate overlapping validation protocols, which increases integration costs, extends qualification timelines, and complicates multi-region product strategies. The result is a market where regulatory alignment is as commercially important as raw instrument performance.
The third challenge is market concentration and its implications for pricing, innovation cadence, and customer leverage. A relatively small group of established players accounts for a substantial portion of total sales, while the remaining market is distributed across specialized and regional suppliers. High concentration can stabilize pricing and accelerate technology diffusion through well-resourced R&D programs, but it can also raise barriers to entry for new innovators and constrain buyer flexibility. Procurement teams seeking multiple sourcing options, or smaller laboratories requiring cost-efficient configurations, often encounter limited alternatives outside the dominant tiers. This dynamic is gradually pressuring incumbents to demonstrate clear total-cost-of-ownership advantages and to offer modular, application-tailored solutions rather than relying solely on generalized flagship models.
Taken together, these challenges create a market that rewards technical credibility, regulatory fluency, and deployment flexibility. Companies and buyers that understand where the friction points sit can position themselves more effectively, whether by investing in hardened measurement platforms, aligning products with specific certification regimes, or structuring procurement to manage supply concentration risk. The remainder of this analysis examines the forces currently reshaping demand and competitive positioning, followed by forward-looking implications for strategy and investment.
Key Drivers of Market Change
Technological Innovation and the Push Toward Lower Detection Limits
The most visible driver of growth in the CLD NOx analyzer market is the ongoing refinement of chemiluminescence detection architecture itself. Traditional photomultiplier tube-based designs remain widely deployed, but there is a meaningful shift toward solid-state detection elements and heated-flow configurations that improve signal stability, reduce warm-up times, and extend service intervals. These advances matter because the practical value of a NOx analyzer is no longer determined solely by its specified detection threshold; it is increasingly judged by how reliably that threshold is maintained under real-world sampling conditions.
Ozone Analyzer Market
Recent exhibition activity and product demonstrations highlight this trajectory. In May 2025, ECO PHYSICS showcased its chemiluminescence NOx analyzers at the EPRI CEMUG 2025 event in Atlanta, reinforcing the industry’s focus on continuous emissions monitoring applications where robust field performance and traceability are paramount. Such appearances are not merely promotional; they signal where engineering attention and customer interest are converging. Manufacturers are investing in instruments that combine low-level measurement capability with practical operational features, such as improved ozone generation control, minimized optical drift, and software-assisted calibration workflows.
For buyers, this innovation cycle changes the evaluation criteria. The most competitive instruments increasingly distinguish themselves through measurement repeatability across long deployment cycles, ease of integration into existing monitoring networks, and transparency in validation documentation. For manufacturers, the strategic implication is clear: incremental sensitivity improvements alone are insufficient. The next layer of differentiation belongs to systems that reduce downtime, simplify compliance reporting, and maintain accuracy in demanding combustion and stack environments.
Regulatory Pressure and Standardization as Demand Catalysts
Policy and regulatory evolution remains a foundational demand driver. The chemiluminescence method continues to be embedded in widely recognized testing and monitoring protocols, reinforcing its position in both ambient air quality networks and industrial emissions applications. In the United States, reference methods and audit procedures applicable to chemiluminescent NOx analyzers continue to shape procurement specifications, particularly for facilities subject to routine relative accuracy evaluations and emissions compliance reporting.
In Europe and the UK, certification pathways under quality assurance frameworks for continuous emissions monitoring and ambient monitoring networks remain central to procurement decisions. The establishment of updated European standards specifying requirements for the selection, installation, and operation of chemiluminescence NOx analyzers in air quality monitoring networks underscores the sector’s shift from generic performance claims toward documented, auditable deployment practices. These standards matter commercially because they influence not only which instruments can be used, but also how implementation is scoped, validated, and maintained over time.
This regulatory environment creates a dual effect. First, it sustains baseline demand from compliance-driven buyers who must meet defined monitoring obligations. Second, it raises the value of instruments and service packages that reduce the administrative and technical burden of certification maintenance. Suppliers that can provide clear alignment with recognized methods, along with practical support for audit readiness and network integration, are better positioned to convert regulatory pressure into durable contract value.
Demand-Side Shifts Across Automotive, Industrial, and Environmental Monitoring
Demand patterns are being reshaped by changes in how combustion emissions are tested, how industrial stacks are monitored, and how ambient air quality networks are designed. In automotive emission testing, the emphasis on real-time, high-sensitivity measurement of NO and NOx continues to support heated analyzer configurations that perform reliably under dynamic sampling conditions. This application area benefits from both regulatory oversight and engineering demand for precise combustion diagnostics, making it one of the more consistently active segments of the market.
Industrial stack monitoring represents another major demand center. Facilities operating combustion processes, turbines, boilers, and related equipment increasingly treat continuous emissions data not simply as a compliance obligation but as a source of operational insight. When NOx measurement is integrated into plant performance monitoring and combustion optimization workflows, the analyzer becomes part of a broader efficiency and risk-management system rather than a standalone compliance instrument. This shift expands the value proposition of CLD technology beyond regulatory minima and into operational decision support.
Ambient air quality monitoring and research applications form a third demand vector, though with a different purchasing profile. In these settings, measurement accuracy, certification status, and network compatibility often carry more weight than high-throughput industrial durability. The research and laboratory segment, while smaller in absolute terms, plays an outsized role in validating new measurement approaches and in training procurement and operations teams on best practices for low-level NOx detection. Across these demand centers, a common thread is the desire for instruments that can credibly support both compliance and analytical rigor without requiring excessive maintenance burden.
Supply Chain, Cost Structure, and the Practical Economics of Ownership
A fourth driver shaping the market is the underlying cost structure of CLD instruments and the practical economics of ownership. These analyzers depend on specialized components such as light detection elements and internal ozone generation subsystems, which influence both performance and service requirements. Because the chemiluminescence reaction relies on controlled ozone production and stable optical detection, variations in component quality, calibration gas management, and maintenance scheduling can materially affect total cost of ownership.
As a result, cost competition in this market rarely plays out as a simple instrument price war. More often, it unfolds through service contracts, calibration support, component lifecycle planning, and software-enabled maintenance scheduling. Buyers are increasingly attentive to whether a supplier can provide predictable uptime, manageable consumable costs, and rapid resolution of field issues. Suppliers, in turn, are incentivized to design instruments that reduce sensitivity to component drift, standardize service procedures, and offer configurable configurations aligned with specific application profiles. This dynamic is gradually tilting the competitive battleground toward reliability engineering and commercial flexibility, not just nominal measurement specifications.
Combustion Analyzer Market
Competitive Landscape and Leading Strategies
The CLD NOx analyzer market is characterized by a set of established, technically credible manufacturers that compete across overlapping application areas while maintaining distinct strategic emphasis. ABB occupies a strong position through instruments built around solid-state chemiluminescence detection for low and ultra-low NOx measurement in combustion applications and continuous emissions monitoring. Its positioning reflects a focus on next-generation detection elements and on meeting the precision demands of modern combustion diagnostics and compliance monitoring. For customers, this translates into a value proposition centered on measurement stability at low concentration levels and on integration with combustion and emissions workflows.
HORIBA competes with a strong emphasis on heated-type CLD configurations, particularly for high-sensitivity real-time measurement of nitrogen oxide species in emissions testing. Its approach is closely aligned with applications where temperature management and rapid response are essential to sample integrity. In practice, HORIBA’s differentiation rests on instrument architectures that prioritize measurement fidelity under dynamic sampling conditions, which is especially relevant for vehicle and engine testing environments where transient emissions behavior must be captured accurately.
Servomex, as part of Spectris, supplies analyzer systems that apply the chemiluminescence method to NO, NO2, and NOx measurement across emissions monitoring, engine testing, and process applications. Its commercial strength is reinforced by alignment with widely recognized testing standards and by a reputation for measurement consistency in regulated environments. This positions Servomex as a trusted option for buyers who need instruments that can withstand scrutiny under formal compliance frameworks and integrate into both continuous monitoring and test-cell operations.
ENVEA addresses a distinct portion of the market through instruments designed for ambient air monitoring and continuous emissions monitoring, with certification status that supports deployment in regulated monitoring networks. Its portfolio reflects an emphasis on suitability for air quality networks and for ongoing emissions measurement, supported by recognized quality assurance alignment. This dual applicability is strategically useful because it allows the company to serve both environmental monitoring authorities and industrial customers who require credible, validated measurement across different operating contexts.
California Analytical Instruments contributes a strong field-oriented offering through heated CLD configurations intended for gas sample analysis in NO, NOx, and NO2 applications. Its 700 series emphasis on heated models signals a practical orientation toward demanding sample environments where temperature control helps preserve measurement accuracy. This positions CAI as a relevant supplier for customers focused on robust field deployment and straightforward integration into gas analysis setups that must handle variable and challenging sample conditions.
ECO PHYSICS distinguishes itself through high-performance CLD instruments spanning both compliance-focused and scientific use cases. Its product range includes analyzers designed for continuous emissions monitoring and trace-level measurement in laboratory settings, reflecting an ability to serve customers who require extreme sensitivity alongside operational compliance. This breadth is strategically important because it allows the company to address both regulated field monitoring and high-precision research demand, two segments that increasingly value instruments capable of bridging measurement rigor with practical deployment demands.
Teledyne API offers chemiluminescence analyzers for ambient and dilution-based continuous emissions monitoring, supported by software tools designed to aid data management and operational oversight. Its approach highlights the growing importance of software-assisted monitoring workflows, where instrument performance is complemented by usability features that simplify data handling and configuration management. In environments where monitoring networks must be operated efficiently and maintained consistently, this combination of measurement hardware and operational software can be a meaningful differentiator.
Signal Group rounds out this competitive field with heated vacuum chemiluminescence analyzers aimed at emissions monitoring, combustion studies, and process applications. Its emphasis on vacuum-based chemiluminescence architecture reflects a technical positioning oriented toward measurement sensitivity and controlled reaction environments. For customers involved in combustion research and emissions characterization, this positioning offers an alternative technical route within the broader CLD landscape.
Taken together, these players illustrate a market in which differentiation is increasingly multidimensional. Leadership no longer depends on a single performance claim; it depends on how effectively a company aligns detection technology, certification compatibility, service economics, and application-specific engineering. Looking forward, the competitive landscape is likely to evolve along three lines. First, consolidation and portfolio breadth may become more valuable as buyers seek suppliers that can support multiple monitoring contexts without fragmenting their compliance and maintenance responsibilities. Second, specialization will remain important for companies that address niche requirements such as ultra-trace laboratory measurement or highly ruggedized field configurations. Third, new entrants and alternative sensing approaches will continue to exert pressure at the margins, especially where buyers are willing to trade some measurement tradition for lower cost or simpler deployment. The likely outcome is a market where incumbents maintain strength through credible differentiation and service ecosystems, while competitive pressure steadily improves the quality, transparency, and usability of CLD-based monitoring solutions.
Future Trends and Commercial Implications
One of the most consequential trends for the next three to five years is the continued migration from compliance-only monitoring toward measurement systems that also support operational optimization. As industrial operators and testing organizations become more comfortable using NOx data for combustion tuning, process diagnostics, and emissions strategy planning, demand will increasingly favor instruments that deliver stable, integrated data streams rather than isolated periodic readings. This creates commercial opportunity for suppliers that can package measurement hardware with software-enabled workflows, standardized data handling, and practical integration support. The risk is that buyers may begin to compare CLD systems not only on analytical performance but also on their ability to reduce operational overhead, which raises the stakes for service design and lifecycle economics.
PW Consulting
A second trend is the growing importance of multi-context compliance readiness. As regulatory expectations continue to tighten across regions and application types, instruments and monitoring packages that can demonstrate alignment with recognized methods and certification pathways will enjoy stronger procurement positioning. This favors suppliers that invest in documentation, validation support, and deployment guidance, especially for buyers managing monitoring networks across multiple sites or jurisdictions. At the same time, the unpredictability of regulatory pacing introduces uncertainty. If standards evolve unevenly or if audit expectations shift, companies that have over-indexed on a narrow compliance assumption may face rework costs, while more flexible architectures may gain advantage.
A third trend concerns the balance between sensitivity and field robustness. Demand for lower detection limits will persist, particularly in ambient monitoring and research, but the practical winner in broader commercial deployments will be the solution that maintains that sensitivity with manageable maintenance and stable long-term performance. This trend creates opportunities for instrument designs that reduce optical drift, streamline calibration management, and improve resilience in challenging sample environments. The associated risk is that overly ambitious sensitivity claims, if not matched by serviceable field performance, can erode trust and open space for alternative measurement approaches where appropriate. For investors and manufacturers, the strategic implication is to prioritize demonstrated reliability and integration value alongside analytical specifications, because those are likely to determine repeat purchasing and long-term customer retention.
Strategic Recommendations for Decision-Makers
For manufacturers, the priority should be to strengthen total-value positioning rather than competing exclusively on nominal detection capability. That means investing in configurations that address real deployment pain points: maintenance predictability, calibration and audit readiness, software-supported data workflows, and application-specific robustness. Companies that can map their instruments clearly to recognized compliance contexts while also demonstrating operational convenience will be better positioned to defend pricing and expand share in both emissions monitoring and testing markets. It is equally important to monitor where regulatory alignment is becoming more demanding, because products that are designed with certification and documentation discipline from the outset will scale more easily across regions and customer segments.
For investors, the most informative signals are not headline revenue figures alone but the direction of product architecture, service economics, and regulatory alignment. Instruments and suppliers that combine credible measurement performance with defensible service models and software-supported operation are more likely to sustain demand through compliance cycles and operational adoption. Attention should also be paid to segments where monitoring is shifting from a pure obligation to an operational tool, because that transition expands the addressable value of CLD-based measurement. Conversely, caution is warranted where pricing pressure is being addressed through component compromise or where product claims are not matched by support infrastructure, since those conditions can undercut long-term competitiveness.
For procurement and operations leaders, the practical goal is to evaluate CLD NOx analyzers as part of a broader monitoring and compliance strategy rather than as isolated instrument purchases. Evaluation criteria should include certification status, compatibility with applicable methods, expected maintenance burden, service responsiveness, and the degree to which the instrument can integrate with existing data and reporting workflows. Where monitoring networks span multiple sites or jurisdictions, flexibility in configuration and clarity in validation documentation can reduce implementation risk. Buyers should also consider whether a supplier’s offering supports the intended balance between compliance assurance and operational insight, because that balance increasingly shapes the long-term value of the investment.
For organizations seeking to move from general market awareness to detailed segment-level decisions, a focused examination of regional demand patterns, application-specific sizing, competitive positioning by product family, and the commercial implications of certification and service economics can materially improve planning quality. Detailed breakdowns of segmentation, supplier share dynamics, and application-driven procurement criteria provide the granularity needed to translate these strategic themes into procurement specifications, product roadmaps, and investment theses.
For detailed analysis of this topic, please visit the official page: Worldwide CLD NOx Analyzer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


