



Global Egg Packing Machinery Market: Why Automatic Systems and 5.43% CAGR Redefine Supply Chains

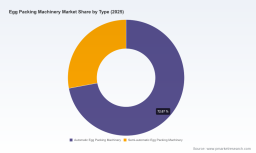
Strategic Trends and Commercial Opportunities in the Worldwide Egg Packing Machinery Market
1. Market Overview and Core Challenges
The global market for egg packing machinery has demonstrated consistent expansion over the past half-decade, with revenue estimates indicating a trajectory from approximately $572.25 million in 2020 to a projected $1.079 billion by 2032. Driven by a compound annual growth rate of 5.43 percent during the 2026-2032 forecast period, the sector reflects a maturation phase where efficiency, hygiene, and scalability dictate procurement decisions rather than mere capacity expansion. The current market size of roughly $745.5 million in 2025 underscores a robust foundation, yet the path forward is not without structural friction. Industry participants must navigate a landscape where volume growth increasingly depends on operational excellence rather than simple market penetration.
One of the most pressing challenges facing the sector is the persistent tension between labor availability and automation requirements. Agricultural and egg processing facilities across multiple regions are grappling with workforce constraints, which directly impact manual grading and packing lines. This labor shortage is not merely a temporary cyclical issue; it represents a structural shift that forces producers to reconsider their reliance on manual processes. The imperative to reduce manual handling and operational costs is accelerating the transition toward automated solutions, yet the capital expenditure required for such transitions can be a barrier for smaller operators who lack the cash flow to invest in high-throughput systems without clear ROI timelines.
Tray Sealing Machines Market
Regulatory pressures form a second critical pivot point. Stringent food safety mandates, particularly those focused on hygiene, Salmonella control, and pasteurization protocols during egg handling, are reshaping equipment specifications. Compliance is no longer optional, and machinery that lacks enhanced sanitary design faces obsolescence risk. Manufacturers and end-users alike must account for these regulatory demands in their capital planning, as retrofitting older lines or investing in new systems with compliant materials—such as stainless steel components for egg contact areas—adds complexity to procurement cycles and total cost of ownership calculations.
A third challenge lies in balancing throughput demands with product integrity. The macro trend of increasing global demand for eggs and processed egg products is pushing facilities to adopt machines capable of handling 10,000 to 60,000 eggs per hour. However, higher speeds must not compromise gentle handling, a requirement that remains paramount for table eggs and breeding stock. Equipment that can deliver both velocity and care is in high demand, but engineering such dual-capability systems requires sophisticated modular designs and precise control systems. Companies that fail to align their product offerings with this balance risk losing ground to competitors who can demonstrate verifiable gentle handling at scale.
2. Key Drivers of Market Growth and Transformation
Technological innovation stands as the primary catalyst reshaping the competitive dynamics of egg packing machinery. Advances in sensor technology, vision systems, and automated sorting algorithms are enabling machines to achieve higher accuracy in grading while minimizing breakage rates. Modular designs have become a hallmark of modern equipment, allowing producers to scale their operations incrementally rather than committing to monolithic line replacements. This flexibility is particularly valuable in an environment where farm sizes and processing volumes can fluctuate due to market conditions, avian influenza outbreaks, or shifting consumer preferences. The ability to integrate fixed or variable speed options, mobile units, and adaptable packing configurations means that machinery can evolve alongside the business, reducing the risk of stranded assets.
The policy and regulatory environment is exerting a profound influence on equipment selection and deployment. Beyond the baseline hygiene and food safety requirements, there is an increasing expectation for traceability and data capture within packing lines. Automated systems that log grading decisions, track egg batches, and integrate with broader farm management software are gaining traction as producers seek to demonstrate compliance and optimize operational insights. Regulations that mandate specific sanitation protocols for wash and packing lines also drive demand for materials and designs that facilitate rapid cleaning and reduce contamination risks. Equipment manufacturers that proactively align their R&D with these regulatory trajectories position themselves as partners in compliance rather than mere vendors of hardware.
On the demand side, consumer and enterprise behavior is shifting in ways that favor processed and value-added egg products alongside traditional table eggs. This diversification requires packing and grading equipment that can handle multiple formats, from standard trays to specialized packaging for liquid egg or further processing. Medium and large farms, as well as dedicated egg processing plants, are increasingly looking for integrated solutions that bridge grading, washing, printing, and packing into a cohesive workflow. The pursuit of throughput efficiency is not solely about volume; it is about consistency, reduced waste, and the ability to meet fluctuating order profiles without sacrificing quality. Enterprises that can demonstrate reliable performance across varied product streams are capturing a larger share of capital expenditure budgets.
PW Consulting
Supply chain and cost structure dynamics also play a pivotal role. The reliance on stainless steel for components in contact with eggs ensures hygiene and durability, but material costs and availability can influence pricing and lead times. Furthermore, the concentration of manufacturing capabilities in certain geographic clusters means that logistics, customs, and local support networks become critical considerations for buyers. Companies that can offer localized service, spare parts availability, and rapid response to downtime minimize the operational risks associated with global procurement. At the same time, cost pressures are driving a search for machines that deliver higher throughput per unit of labor and energy, reinforcing the value proposition of automation even in contexts where labor is available but expensive.
Recent industry activities illustrate how these drivers converge in practice. Participation in major trade exhibitions such as IPPE 2026, which featured extensive exhibits on poultry and egg processing equipment with record attendance and floor space, signals the sector's vitality and the intensity of innovation dissemination. Similarly, manufacturers showcasing their latest grading and packing machines at regional events like CAHE 2026 in Chengdu highlight the growing importance of Asian markets and the desire to demonstrate capabilities directly to a diverse audience of producers and integrators. These events serve as barometers for where technology, demand, and regional growth intersect, offering tangible evidence of the market's directional shifts.
3. Competitive Landscape and Leading Strategies
The competitive environment in egg packing machinery is characterized by a mix of established multinational players and specialized regional manufacturers, with a concentration ratio that suggests a moderately consolidated structure. Leading firms differentiate themselves through a combination of product breadth, technological sophistication, and service ecosystems. Companies that offer automated systems spanning from small farm applications to full-scale production lines with gentle egg handling and modular designs are well-positioned to capture value across diverse customer segments. The ability to provide high-capacity automated packing lines and integrated solutions allows leaders to address the throughput demands of large operations while maintaining the flexibility to adapt to varying egg types and packaging formats.
Strategic positioning among top competitors often hinges on the balance between automation level and operational practicality. Some manufacturers specialize in compact, versatile automatic packing machines that emphasize modularity, mobility, and fixed or variable speed options, catering to facilities that require reliable performance without excessive footprint or complexity. Others focus on gentle egg handling and packing for table eggs in trays, offering both semi-automatic and automated packers suited for layers and breeders. This segmentation of strengths means that buyers must evaluate not only technical specifications but also the alignment of a supplier's core competencies with their own operational profile, growth plans, and regulatory obligations.
Regional diversity among manufacturers adds another layer to the competitive dynamics. Firms based in Europe and North America often emphasize advanced automation, integration with broader poultry systems, and compliance with stringent food safety frameworks, while manufacturers from Asia and other emerging regions frequently compete on cost efficiency, rapid deployment, and complete automated processing and packing lines that cover grading, washing, printing, and separation. This divergence creates opportunities for cross-regional learning and partnership, as well as potential friction in terms of perceived quality, support infrastructure, and long-term reliability. Buyers increasingly weigh total cost of ownership, including service availability and spare parts logistics, against upfront pricing, which can shift the competitive advantage toward suppliers with strong local presence and responsive after-sales networks.
The market is also witnessing evolutionary trends in consolidation and new entry. Larger players with integrated poultry and egg production system portfolios, including egg handling and packing solutions, are well-placed to offer end-to-end value propositions that reduce integration risk for customers. At the same time, specialized firms focusing on egg processing equipment with capabilities supporting packing and sorting lines for food industry applications are carving niches around specific processing needs, such as pasteurization readiness or specialized tray configurations. New entrants and expanding regional players continue to challenge incumbents by targeting underserved segments, leveraging cost structures, and adopting proven technologies to accelerate time-to-market. In this environment, the ability to demonstrate consistent performance, gentle handling, and regulatory compliance becomes a key differentiator, as does the capacity to provide modular, scalable solutions that grow with the customer's business.
The competitive landscape is further shaped by the emphasis on hygiene and material standards. Equipment that prioritizes stainless steel components for egg contact areas not only meets sanitary design expectations but also signals durability and lower long-term maintenance burdens. Suppliers that embed these material choices into their core engineering philosophy, and that can articulate the operational and compliance benefits clearly, build trust with procurement teams that must justify capital investments against both financial and risk-management criteria. The interplay of these factors suggests a market where differentiation is increasingly derived from integrated technology, service reliability, and the ability to navigate the intersection of throughput, hygiene, and flexibility.
4. Future Trends and Strategic Outlook (2026-2032)
One of the most significant trends likely to define the next three to five years is the deepening integration of automation with data-driven management. As labor constraints persist and regulatory scrutiny intensifies, packing lines will increasingly function as nodes within broader digital ecosystems. Grading and packing equipment will be expected to capture granular operational data, support traceability requirements, and interface with farm and processing management platforms. This shift creates commercial opportunities for manufacturers and integrators who can offer seamless connectivity, analytics dashboards, and predictive maintenance capabilities, while also posing a risk for those whose products remain isolated hardware solutions without clear pathways to data integration.
A second trend is the continued push toward higher throughput combined with uncompromising gentle handling. Demand for eggs and processed egg products is expected to remain robust, and facilities will seek machines that can process 10,000 to 60,000 eggs per hour without elevating breakage or compromising hygiene. Innovation in conveyance, cushioning, and speed control will differentiate suppliers, and end-users will reward systems that balance speed with product protection. The opportunity here lies in engineering and marketing solutions that provide verifiable performance metrics, enabling buyers to model ROI based on reduced waste and higher quality output. A risk to monitor is the potential for over-optimization on speed at the expense of handling quality, which can erode trust and lead to costly retrofits or replacements.
Third, regional demand dynamics will continue to reshape where growth is most pronounced and where competitive pressure intensifies. Markets with expanding medium and large farm operations, as well as dedicated processing plants, will drive demand for integrated, high-capacity lines, while smaller or more cost-sensitive regions may favor semi-automatic or modular solutions that allow incremental upgrades. This divergence creates opportunities for tailored go-to-market strategies, localized support models, and product configurations that match regional regulatory and operational contexts. A key uncertainty is the pace of regulatory evolution and the extent to which hygiene and safety mandates accelerate automation adoption across all segments, which could compress the window for semi-automatic solutions in certain markets.
5. Strategic Considerations for Decision-Makers
For manufacturers, the priority is to sustain investment in modular, sanitary, and data-ready designs that can serve a spectrum of farm sizes and processing formats. Aligning R&D with the dual imperatives of throughput and gentle handling, while ensuring compliance with evolving hygiene standards, will strengthen competitive positioning. Building robust service and parts networks, along with clear communication of material choices such as stainless steel for critical components, can differentiate offerings in a market where total cost of ownership matters as much as initial price.
High Speed Packaging Machine Market
For investors, the landscape suggests selective opportunities in companies that demonstrate scalable technology platforms, strong regional presence, and the ability to integrate packing solutions with broader poultry system portfolios. Concentration dynamics indicate that consolidation and partnership activity may continue, and due diligence should weigh service capabilities, regulatory alignment, and the flexibility of product lines to adapt to shifting demand patterns. Tracking exhibition activity and product launches at major industry events can provide early signals of innovation direction and regional focus.
For purchasers and procurement teams, the decision matrix should extend beyond headline throughput figures. Evaluating gentle handling performance, hygiene design, modularity, and the supplier's ability to support compliance and data integration will reduce long-term operational risk. Engaging with suppliers that can demonstrate reliable performance across varied product streams, and that offer clear pathways for incremental capacity expansion, helps balance immediate needs with future growth. For those seeking granular segmentation data and tailored strategic recommendations, the full research report provides detailed breakdowns across regions, types, and applications, along with scenario analysis to support capital planning and competitive positioning.
For detailed analysis of this topic, please visit the official page: Worldwide Egg Packing Machinery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


