



Enclosed Track Conveyors Market: How 5.85% CAGR Drives 2032 Expansion Beyond Scale

Strategic Trends and Commercial Opportunities in the Global Enclosed Track Conveyors Market
Market Overview: Current Landscape and Core Challenges
The global enclosed track conveyor industry enters the late 2020s as a mature yet steadily expanding segment within material handling and industrial automation. Valued at approximately USD 784.5 million in 2025, the market has demonstrated consistent growth from its 2020 baseline, with projections indicating a trajectory toward USD 1.17 billion by 2032. This expansion reflects a compound annual growth rate of 5.85 percent across the forecast horizon, signaling durable demand rather than cyclical volatility. The sector's resilience stems from its foundational role in overhead material transport, where enclosed track systems offer a compelling balance of load capacity, spatial efficiency, and operational safety compared to open I-beam alternatives.
However, growth trajectories are not without friction. Three structural challenges currently shape the industry's evolution. First, supply chain volatility in specialized steel profiles and precision chain components continues to influence lead times and system pricing. Enclosed track conveyors depend on engineered track geometries and hardened chain links that require controlled metallurgical processes, making upstream material availability a persistent operational variable. Second, the regulatory environment is tightening around safety and dust exposure, with updated standards introducing new compliance requirements for design, inspection, and maintenance protocols. Manufacturers and end-users must now navigate more rigorous documentation and installation verification, which raises upfront engineering costs but also creates a barrier that favors established players with mature quality systems. Third, the market faces a integration paradox: as facilities pursue smarter, data-driven operations, legacy enclosed track installations often lack native connectivity, forcing operators to weigh retrofit investments against full system replacements. This tension between operational continuity and digital upgrade paths defines much of the current procurement discourse.
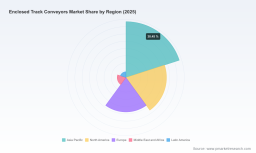
Geographically, the market exhibits a clear concentration pattern, with the Asia Pacific and North America regions accounting for the largest revenue shares, followed by Europe. This distribution reflects differing industrial maturation levels, automotive and electronics manufacturing footprints, and logistics infrastructure investment cycles. Application demand remains anchored in automotive assembly and industrial finishing, while e-commerce fulfillment and food processing continue to gain incremental share as hygiene standards and flexible layout requirements intensify. The competitive structure remains moderately fragmented, with the top three suppliers capturing roughly one-third of total revenue and the top five approaching half, leaving substantial room for regional specialists and technology-differentiated entrants.
Key Demand Drivers and Structural Shifts
Technological Innovation and Modular System Design
The most visible driver of market expansion lies in the ongoing refinement of modular, enclosed track architectures that prioritize installation flexibility and maintenance efficiency. Traditional overhead conveyor deployments often required extensive structural modification and long commissioning windows. Newer system designs emphasize standardized trolley interfaces, quick-swap chain segments, and pre-engineered bend radii that reduce on-site fabrication. This modularity aligns directly with the operational reality of modern manufacturing floors and distribution centers, where production lines must be reconfigured for product mix changes, seasonal volume swings, or footprint optimization. Companies that have showcased integrated demonstrations combining enclosed track conveyors with robotic handling and automated order fulfillment illustrate how mechanical material transport is increasingly treated as a component within broader automation ecosystems rather than a standalone utility. The commercial implication is clear: system value is shifting from pure load-moving capability toward integration readiness, serviceability, and layout adaptability.
Policy, Safety Standards, and Compliance Dynamics
Regulatory and standards activity is reshaping procurement criteria across the sector. Updated safety frameworks for conveyors and related equipment now extend more explicitly to enclosed track designs, introducing provisions that address dust hazards, inspection frequency, and operational verification. These requirements do not merely add bureaucratic steps; they alter the total cost of ownership calculus. Facilities operating in finishing, powder coating, food processing, and light industrial environments must account for contamination control, surface protection, and worker exposure in ways that favor enclosed configurations over exposed alternatives. At the same time, compliance pressure rewards suppliers with documented quality management, traceable component sourcing, and field service networks capable of supporting recurring inspection cycles. The trend effectively raises the floor for market participation while creating a differentiation axis for vendors that can package safety compliance, documentation, and lifecycle support into a single procurement proposition.
Demand-Side Shifts in Manufacturing and Logistics
End-user behavior is evolving under the combined influence of labor availability pressures, throughput expectations, and facility design priorities. In automotive and heavy assembly environments, enclosed track systems continue to serve as reliable work-in-process transporters that keep floor space clear and reduce manual handling risk. In finishing and coating applications, the enclosed nature of the track helps contain overspray, protect moving components, and support cleaner_process environments. Meanwhile, e-commerce and logistics operations increasingly evaluate overhead conveyance not only for bulk movement but also for sequenced order picking, sorting integration, and ergonomically optimized workstations. This broadening application base reduces dependence on any single vertical and creates cross-sector demand for systems that can be scaled in span, speed, and load rating without major redesign. The practical outcome is a more diversified demand profile, where flexibility and hygiene considerations often compete with pure cost-per-foot arguments.
Supply Chain and Cost Structure Considerations
Cost dynamics are being reshaped by the interplay of raw material sourcing, component specialization, and service expectations. Enclosed track systems rely on engineered steel tracks, precision chains, trolleys, and drive units, meaning that fluctuations in metal pricing, motor availability, and machining capacity reverberate through project quoting and delivery schedules. At the same time, customers are increasingly sensitive to installed cost, downtime during changeovers, and long-term maintenance burden. This environment favors suppliers that can offer standardized component libraries, regional inventory positioning, and predictive maintenance guidance. It also encourages end-users to evaluate lifecycle economics more rigorously, weighing initial capital expenditure against spare parts availability, technician training, and the ability to expand or reconfigure the system without replacing the entire track infrastructure. In effect, cost competition is moving from unit price to reliability, lead time, and upgrade-option value.
Competitive Landscape and Strategic Positioning
The competitive field combines long-established North American manufacturers with international component suppliers and regional specialists. This mix creates a layered environment where incumbents compete on system breadth, engineering support, and installed-base service, while newer or regional players compete on price, niche load ratings, and localized deployment agility.
PW Consulting
Among the established names, companies with long track records in enclosed track monorail systems emphasize durability, modular installation, and application breadth. Profiles from firms originating in the mid-twentieth century often highlight standardized configurations that simplify specification for auto-body shops, manufacturing floors, and receiving areas. Their differentiation rests on proven uptime narratives, extensive field references, and the ability to offer power-only, power-and-free, and towline variations within a common design language. This breadth allows them to address a wide range of load profiles and throughput requirements while maintaining consistent spare-parts logistics.
Other leading players focus on capacity tiers and integration readiness. Some offer medium-capacity solutions tailored for tight spaces, while others provide heavy-duty variants or over-under configurations designed for large-volume production at a favorable cost position versus traditional I-beam systems. A distinct subset of competitors centers on component-level strength, supplying chains, trolleys, and specialty hardware to system builders and end-users alike. This component-focused model is strategically important because it embeds the supplier within multiple system architectures, creating recurring demand even when full-system projects fluctuate.
Recent activity underscores how competition is shifting toward integration and application-specific demonstrations. Public showcases combining enclosed track conveyors with robotic handling for carton movement and order fulfillment point to a market where mechanical transport is increasingly validated within end-to-end automation scenarios. At the same time, catalog and product updates emphasizing standard components with free-running trolleys for lower-cost overhead applications indicate continued segmentation between value-oriented installations and engineered, higher-capacity systems. The competitive signal is that suppliers are pursuing both ends of the spectrum: premium integration for complex workflows and standardized affordability for simpler overhead transport needs.
Worldwide Enclosed Torque Motor Market
Future Outlook: Trends Shaping the Next Three to Five Years
Several interdependent trends are likely to define market direction through the early 2030s. First, integration depth will increase as facilities seek overhead conveyance that communicates with broader control architectures. This does not necessarily mean every installation becomes highly automated, but it does suggest that compatibility with sensors, programmable logic, and data collection layers will become a more frequent selection criterion. Systems that can be instrumented for throughput monitoring, fault detection, and maintenance scheduling will hold a growing advantage in environments where downtime is costly and changeover frequency is high.
Second, hygiene and contamination control will continue to pull demand toward enclosed configurations in finishing, food-adjacent processing, and clean manufacturing contexts. As environmental and operational standards tighten, the enclosed track's ability to shield chains and trolleys from particulates, overspray, and incidental contamination will be valued not only for equipment longevity but also for process consistency. This trend favors suppliers that can articulate cleaning protocols, material compatibility, and service practices aligned with regulated or high-purity environments.
Third, regional capacity and supplier diversification will likely expand, particularly as end-users seek shorter lead times, localized service, and reduced exposure to single-region supply disruptions. Asia Pacific's substantial revenue presence and the presence of component manufacturers in Taiwan and India indicate an ecosystem capable of supporting both full-system projects and component-level supply. The opportunity for new entrants and expanding incumbents lies in pairing regional manufacturing responsiveness with reliable engineering specifications and compatible interface standards.
Potential risks remain. Steel and motor cost volatility can compress margins and delay projects, especially for engineered systems with long quote-to-delivery cycles. Regulatory updates may raise compliance costs in the near term, particularly for operators retrofitting older installations. In addition, if automation budgets soften in key verticals, procurement may shift toward incremental upgrades rather than full replacement, pressuring suppliers to offer flexible expansion paths and retrofit-compatible components.
Strategic Actions for Decision-Makers
For manufacturers and automation engineers, the priority should be to evaluate enclosed track systems not only on load capacity and footprint, but also on integration readiness, service access, and reconfiguration flexibility. Favor designs that allow span adjustments, trolley interchangeability, and straightforward inspection access, and align component selection with the facility's anticipated product-mix volatility.
For investors and corporate development teams, the opportunity lies in identifying suppliers that combine application breadth with credible service networks and component-level repeatability. Companies that can support multiple verticals while maintaining standardized interfaces and documented compliance practices are better positioned to capture demand as facilities modernize incrementally rather than replacing systems wholesale.
Enclosed Belt Conveyor Market
For procurement and operations leaders, total cost of ownership should be assessed across lead time, spare-parts compatibility, maintenance burden, and upgrade options rather than initial installed price alone. Where hygiene, dust control, or turnover frequency are material, enclosed track configurations warrant explicit comparison against open alternatives, with due attention to compliance documentation and service-response capability. Given the pace of standards updates, integration expectations, and regional supply shifts, more granular segmentation data and tailored scenario analysis can help decision-makers narrow specification choices and time investments more effectively. Readers seeking deeper breakdowns by application profile, regional deployment patterns, and company-level positioning can review the full PW Consulting market report for detailed segmentation metrics and actionable recommendations aligned to specific operational contexts.
For detailed analysis of this topic, please visit the official page: Worldwide Enclosed Track Conveyors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


