



Computer on Wheels Market: Why 14.5% CAGR Through 2032 Changes Everything

Strategic Trends and Commercial Opportunities in the Worldwide Computer on Wheels Market
Market Landscape and Core Challenges
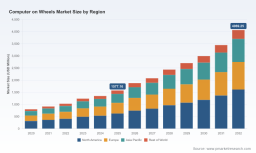
The global computer on wheels (COW) market has demonstrated robust expansion over the past half-decade, transitioning from a niche healthcare mobility segment to a mainstream component of clinical infrastructure. Market valuation placed the sector at approximately USD 1,577.16 million in 2025, reflecting consistent year-over-year growth from a base of USD 801.4 million in 2020. Forward-looking projections indicate a compound annual growth rate of 14.5 percent through 2032, with revenue anticipated to surpass USD 4 billion by the end of the forecast horizon. This trajectory underscores a structural shift rather than cyclical fluctuation, as healthcare delivery models increasingly prioritize bedside documentation, mobile diagnostics, and real-time electronic medical record access. Regional and product-type dynamics reveal a mature but still evolving demand pattern, with powered systems commanding the largest share of revenue while non-powered alternatives maintain relevance in cost-sensitive or space-constrained environments.
Despite the favorable growth trajectory, the industry faces several structural headwinds that will shape competitive positioning over the next decade. First, regulatory scrutiny around medical device compliance continues to tighten across multiple jurisdictions. Electrical safety, electromagnetic compatibility, and infection control standards now function as baseline requirements rather than differentiators, forcing manufacturers to embed compliance into design cycles rather than retrofitting existing platforms. Second, the integration of advanced battery and power management systems has introduced both an operational imperative and a supply chain vulnerability. Lithium iron phosphate packs with hot-swap capabilities have become the de facto infrastructure for sustained clinical operation, yet sourcing, lifecycle management, and replacement logistics remain fragmented across the vendor ecosystem. Third, labor cost pressures and nursing workflow inefficiencies are driving demand for mobility solutions, but procurement cycles in healthcare systems remain lengthy and highly sensitive to total cost of ownership calculations. Organizations must navigate the tension between immediate workflow gains and long-term capital justification, which can delay adoption in budget-constrained settings.
The market is also approaching a consolidation inflection point. Revenue concentration among the top three and top five participants indicates a moderately fragmented landscape with clear leadership clusters, but the presence of specialized regional suppliers and custom-configuration providers suggests that differentiation will increasingly hinge on integration depth, service networks, and lifecycle support rather than pure hardware specifications. Companies that treat COW deployments as static equipment purchases risk losing ground to competitors who position these systems as configurable, service-enabled platforms aligned with clinical workflow evolution.
Medical Computer Cart Market
Key Drivers Shaping Market Evolution
Several interdependent forces are accelerating demand and reshaping product requirements across the COW sector. At the technology frontier, the convergence of low-profile computing architectures, ruggedized enclosures, and modular battery ecosystems has redefined what mobile workstations can deliver at the point of care. Patented fast-swap battery technologies and lithium iron phosphate systems with hot-swap capabilities now enable continuous operation without downtime, which is critical for hospitals running extended clinical shifts. Manufacturers have responded by designing carts that accommodate third-party computing modules or integrate all-in-one medical-grade displays, allowing facilities to standardize on a mobility platform while retaining flexibility in processor selection, operating system configuration, and peripheral attachment. This modularity reduces replacement friction and extends asset longevity, aligning hardware refresh cycles with clinical IT roadmaps rather than forcing simultaneous upgrades across every deployment.
Policy and regulatory environments are acting as both a constraint and a catalyst. Healthcare computer on wheels systems must comply with medical device standards for electrical safety, electromagnetic compatibility, and infection control in hospital environments. Rather than treating these requirements as purely defensive, leading manufacturers are using compliance as a trust signal and a design anchor. Standardized certification pathways reduce procurement friction for health systems, while infection-control features such as seamless surfaces, antimicrobial coatings, and easily disinfected contact points are increasingly specified in tender documents. In parallel, broader digital health policies that encourage electronic medical record adoption and bedside data capture indirectly expand the addressable base for mobile workstations, since facilities investing in digital workflows require reliable, mobile access points that move with clinicians rather than anchor them to fixed terminals.
On the demand side, the most pronounced shift is the operational response to labor cost pressures and workflow inefficiency. Mobile computer on wheels reduce time spent by nurses walking to stationary terminals, supporting workflow efficiency in point-of-care documentation. This logistical benefit translates into measurable time savings during documentation, medication administration, and bedside rounding, which in turn influences purchasing decisions among nursing leadership and clinical operations teams. Beyond time savings, the expectation for real-time data access has raised the stakes for device reliability. Clinicians increasingly view mobile workstations as extensions of the clinical team rather than peripheral equipment, which elevates expectations for uptime, ergonomic design, and seamless docking or charging behavior. Facilities that have deployed sit-to-stand configurations or customizable workstation heights are reporting improved clinician acceptance, suggesting that ergonomics and usability have become as important as raw computing capability.
Supply chain and cost structure changes are also reshaping competitive dynamics. The shift toward battery-centric infrastructure has introduced a recurring component management dimension to what was historically a one-time capital purchase. Hot-swap battery packs and modular power systems create opportunities for repower services, warranty extensions, and lifecycle support contracts, converting some hardware revenue into longer-duration service relationships. At the same time, ISO-certified manufacturers with established export experience are expanding their footprint into global healthcare markets, increasing price and specification competition in regions where procurement teams balance clinical-grade requirements against budget constraints. This dynamic is encouraging both incumbents and new entrants to clarify their value propositions: whether they compete on integration depth, regional service coverage, cost efficiency, or specialized workflow configurations.
Competitive Landscape and Strategic Positioning
The competitive field is anchored by a group of U.S.-based manufacturers that have built recognizable positions around customization, battery innovation, and workflow alignment. Scott-Clark Medical has carved a niche around customizable healthcare computer on wheels and mobile computer carts, with powered systems featuring patented FMCPT battery technology optimized for point-of-care use in hospitals. This battery-led differentiation gives the company a tangible engineering narrative in procurement discussions where uptime and battery reliability are primary concerns. Altus Inc. competes across both powered and non-powered medical carts, offering battery-powered computer on wheels workstations designed for hospital EMR and patient care workflows. Its broader product span allows flexibility across budget tiers and deployment contexts, which is useful for health systems standardizing across multiple units or campuses. DTG Power emphasizes battery-powered workstation on wheels solutions and LFP battery systems, and notably positions repower services for existing carts from various manufacturers. This service-oriented angle extends the company's relevance beyond new equipment sales and into lifecycle support, an increasingly important consideration for facilities managing mixed-fleet environments.
Ergotron and Capsa Healthcare illustrate complementary strategic angles within the same ecosystem. Ergotron manufactures mobile computer carts and workstations on wheels for healthcare environments, frequently integrated with third-party battery and computing solutions, which positions the brand as a flexible platform partner rather than a closed-system vendor. Capsa Healthcare produces medical carts including computer on wheels and medication workstations designed for hospital point-of-care documentation and mobile computing, aligning product design directly with documentation and medication workflows. Cybernet and Teguar approach the market from the computing-hardware side, supplying all-in-one medical computers and rugged medical computers respectively, with configurations suitable for integration into computer on wheels carts in healthcare settings. Their strength lies in hardware durability, certification readiness, and compatibility with mobile cart ecosystems, making them relevant to buyers who prioritize compute reliability and environmental resilience. DataCart adds a further dimension with customizable workstations on wheels featuring sit-to-stand capabilities, targeting healthcare mobility and point-of-care applications where ergonomics and clinician posture are decision factors.
International participants are expanding the scope of competition. All Modul GmbH develops various models of computer on wheels from budget to high-end configurations, with customization options for European healthcare markets, which allows it to address both price-sensitive and specification-driven buyers in its region. ZHAOFA Technology operates as an ISO-certified manufacturer of hospital-grade computer on wheels and mobile workstations for global healthcare markets, and its continued offering of custom hospital-grade COW and WOW systems reflects a sustained focus on export-oriented, specification-adaptable production. Convergint Innovative Medical supplies workstations on wheels and computer on wheels solutions tailored for nursing workflows and simulation labs in healthcare, underscoring a workflow-and-training orientation that resonates with academic medical centers and simulation-based training environments.
The recent dynamics across these players point to a market that is simultaneously consolidating around a few recognizable leaders and fragmenting around specialized use cases. ZHAOFA's ongoing catalog emphasis on custom hospital-grade COW and WOW systems, supported by a decade of manufacturing experience, signals that configurable production remains a viable entry and growth path for established OEMs serving international buyers. Indurock's updated analysis of COW terminology, hospital applications, and future trends in mobile computer workstations for healthcare and logistics indicates that the category itself is being refined and communicated more precisely, which benefits buyers but also raises the bar for vendors to articulate clear use-case fit. Convergint's continued promotion of WOW/COW benefits for nurses and ongoing supply for healthcare simulation and clinical use highlights how workflow advocacy and training environments are becoming explicit demand channels, not just end-point deployments.
Strategically, the most successful players are those that convert hardware into a platform story. Battery technology, repower services, ergonomic configuration, infection-control design, and simulation-ready deployment all function as differentiators when they are tied to measurable clinical outcomes or operational savings. The market is therefore moving away from generic cart specifications toward solution-level competition, where vendors are evaluated on how well their mobile workstations fit nursing workflows, EMR integration expectations, and lifecycle management requirements. New entrants that bring clear workflow alignment, regional service capacity, or cost-efficient ISO-certified manufacturing can still gain traction, but they must do so by targeting a defined segment rather than competing broadly on price alone.
Forward-Looking Trends and Commercial Implications
Over the next three to five years, several trends are likely to define how the COW market evolves and where commercial opportunities concentrate. First, battery and power management will become the central lifecycle differentiator rather than a secondary feature. As lithium iron phosphate packs with hot-swap capabilities become standard expectations in clinical settings, competitive advantage will shift toward battery reliability metrics, replacement logistics, and repower or refresh services. Manufacturers and service providers that can standardize battery health monitoring, hot-swap training, and predictable replacement cycles will be better positioned to retain customers and expand into service-based revenue. The commercial implication is clear: mobility hardware will increasingly be evaluated as part of a managed power ecosystem, and procurement decisions will weigh total uptime and service coverage alongside initial unit economics.
PW Consulting
Second, workflow-integrated configurations will gain prominence over generic mobile carts. The push to reduce nursing walking time and improve point-of-care documentation is driving demand for sit-to-stand features, ergonomic adjustability, medication-specific workstation layouts, and simulation-ready setups. This trend favors vendors that can demonstrate how a specific cart configuration supports a documented clinical pathway, whether for bedside rounding, medication administration, or training environments. Companies that invest in workflow research, clinician feedback loops, and configurable options are likely to secure stronger preference in tenders, particularly in health systems that have moved beyond pilot deployments and are standardizing across multiple units. The opportunity here lies in packaging configuration flexibility with clear guidance on which layouts fit which workflows, reducing the decision burden for procurement teams and clinical leaders.
Third, the market will see continued pressure toward regional specialization and certified manufacturing footprints. ISO-certified manufacturers with global export experience are expanding reach into international healthcare markets, while regional customizers are refining offerings for local compliance expectations and procurement norms. This creates a dual dynamic: global scale players compete on integration breadth and service networks, while regional and cost-efficient manufacturers compete on specification adaptability and price-to-performance ratios. For commercial strategy, this means that buyers will increasingly choose between standardized global platforms and locally tailored configurations depending on their compliance environment, service expectations, and budget posture. The risk for vendors is that undifferentiated hardware becomes commoditized quickly, while the risk for buyers is that over-customization complicates maintenance and standardization across sites.
Computer On Module (COM) Market
A persistent uncertainty across these trends is the pace of health system capital cycles. Even when workflow benefits are well documented, procurement timelines can stretch, especially in environments where total cost of ownership justification must compete with other clinical priorities. Supply chain stability for battery components and the consistency of infection-control compliance across product lines will also influence adoption speed. Organizations that can align their value proposition with both clinical workflow gains and predictable lifecycle economics are best positioned to navigate these uncertainties.
Actionable Recommendations for Decision Makers
For manufacturers and solution providers, the priority is to move beyond product specifications and build a defensible workflow-and-lifecycle narrative. Differentiate around battery reliability, repower or refresh services, ergonomic configurations, and infection-control design, and make those claims traceable to documented clinical or operational benefits. Tailor go-to-market messaging to specific use cases rather than broad category language, since procurement teams increasingly evaluate mobile workstations against defined workflows and service expectations. Companies that can combine configurable hardware with predictable service coverage will be better positioned to protect margin and extend customer relationships over the asset lifecycle.
For investors evaluating exposure to this segment, focus on the durability of competitive advantages rather than headline growth alone.Assess whether a target company has genuine differentiation in battery technology, service infrastructure, workflow-aligned design, or regional manufacturing scale. Examine the balance between one-time hardware sales and longer-duration service potential, since lifecycle support and repower capabilities can materially affect recurring revenue quality. Also pay attention to compliance readiness and certification positioning, as these factors influence procurement speed and customer retention in regulated clinical environments. Companies whose growth depends primarily on price competition without workflow or service differentiation carry higher exposure to margin compression as the category matures.
For healthcare procurement teams and clinical operations leaders, the most effective approach is to evaluate mobile workstations as configurable platforms integrated into documented workflows, not as interchangeable equipment purchases. Standardize on core requirements for electrical safety, electromagnetic compatibility, infection control, and battery uptime, then use configuration flexibility to address department-specific needs such as sit-to-stand ergonomics, medication workstation layouts, or simulation lab use. Where possible, prioritize vendors that can support mixed-fleet environments, provide clear battery lifecycle management, and offer training or workflow guidance for clinicians. This reduces operational friction and helps ensure that mobility investments translate into measurable time savings and documentation efficiency rather than unused capacity.
Given the speed at which battery standards, compliance expectations, and workflow preferences are evolving, detailed segment-level data and customized scenario planning remain valuable for precise decision making. Organizations preparing capital plans, product roadmaps, or procurement strategies can benefit from a fuller breakdown of regional demand patterns, product-type economics, end-user dynamics, and company-level benchmarking to ensure that commitments are aligned with the most current market structure.
For detailed analysis of this topic, please visit the official page: Worldwide Computer on Wheels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


