



Polymer Substrates Market Hits $25.4B by 2032: 5 Strategic Shifts

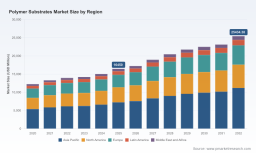
Strategic Trends and Commercial Opportunities in the Global Polymer Substrates Market
Market Landscape and Core Challenges
The worldwide polymer substrates market has demonstrated robust expansion over the past half-decade, evolving from a steady growth trajectory into a dynamic sector shaped by technological convergence and shifting industrial priorities. Valued at approximately $12.25 billion in 2020, the market reached an estimated $16.45 billion by 2025, reflecting a compound annual growth rate of 6.42 percent through the forecast period extending to 2032. This expansion is not merely a function of volume but reflects deepening penetration across high-value electronics, energy infrastructure, and security applications. The market structure remains moderately fragmented, with the top three participants capturing just over 32 percent of total revenue and the top five firms approaching 48 percent. Such concentration levels indicate a landscape where scale advantages exist but are not insurmountable, leaving room for specialized players to compete on performance, regional proximity, or application-specific engineering.
Despite the positive trajectory, the industry stands at a critical inflection point defined by three interlocking challenges. First, raw material volatility has transitioned from a periodic disruption to a structural stressor. Feedstocks such as ethylene, propylene, and purified terephthalic acid form the backbone of mainstream polymer films, yet their pricing can swing by as much as 25 percent within a single year. This unpredictability compresses margins for manufacturers who operate on fixed-price contracts or lack the agility to pass costs downstream. Second, regulatory tightening is reshaping compliance economics. Recent restrictions on methylene chloride as a bonding agent for acrylic and polycarbonate substrates, alongside the phase-out of hexavalent chromium in plastic plating, have elevated compliance expenditures by roughly 18 to 25 percent for treatment facilities. These rules do not merely add administrative burden; they force retooling, process redesign, and verification protocols that disproportionately affect mid-tier producers. Third, the rapid proliferation of advanced display architectures and flexible circuit designs is raising performance thresholds. Suppliers must now balance thermal stability, optical clarity, dielectric consistency, and mechanical durability within thinner form factors, creating a technical barrier that favors companies with integrated R&D and application-specific formulation capabilities.
For executives evaluating market entry, expansion, or procurement strategies, these dynamics signal a shift from volume-driven competition to value-driven differentiation. The organizations that navigate this phase successfully will be those that treat feedstock risk, regulatory adaptation, and performance specification as interconnected strategic variables rather than isolated operational concerns.
Key Drivers Reshaping the Market
Technological innovation remains the primary engine of market evolution. The transition from rigid to flexible electronic architectures has elevated polymer substrates from passive carriers to active enablers of device performance. Polyimide and polyester films, for instance, are no longer evaluated solely on mechanical flexibility; they are scrutinized for thermal endurance, coefficient of thermal expansion matching, and compatibility with lamination and etching processes. Meanwhile, newer thiol-based optical polymer films and engineered adhesives are addressing long-standing trade-offs between transparency, adhesion, and reworkability in display manufacturing. These material advances are not incremental; they are unlocking form factors that were previously uneconomical or technically unfeasible, particularly in ultra-thin wearable devices and foldable display panels.
Policy and regulatory frameworks are acting as a second, equally powerful driver. Environmental mandates are accelerating the redesign of both materials and processing pathways. Restrictions on certain solvents and heavy-metal plating compounds are pushing manufacturers toward water-based adhesives, low-volatile organic compound formulations, and alternative surface treatments. While compliance costs have risen, these regulations are also creating a structural advantage for firms that have already invested in cleaner process architectures. In regions where electronics waste directives and chemical safety standards are tightening, suppliers with verified environmental compliance are finding preferential access to premium contracts, particularly with multinational OEMs that face their own downstream reporting obligations.
Demand-side behavior is undergoing a parallel transformation. Consumer electronics manufacturers are racing to reduce device weight and thickness while maintaining durability, a push that directly increases the share of flexible printed circuits and OLED display applications within the substrate mix. Simultaneously, the expansion of photovoltaic installations and the electrification of automotive systems are driving requirements for substrates that can withstand UV exposure, moisture ingress, and thermal cycling over extended service lives. Medical device designers are adopting polymer films for imaging substrates, diagnostic patches, and sterilization-compatible housings, valuing their biocompatibility and dimensional stability. These application shifts are not isolated; they are converging on a common requirement set that favors materials with tunable mechanical properties, predictable dielectric behavior, and reliable supply continuity.
Supply chain and cost structure dynamics complete the driver set. Regional production footprints are being recalibrated as companies respond to freight volatility, tariff uncertainty, and the desire for shorter lead times. Price adjustments on engineered materials and polymer dispersions have become more frequent, reflecting both upstream feedstock conditions and the costs of maintaining compliance-ready facilities. In this environment, procurement strategies that once prioritized unit price are increasingly incorporating total cost of ownership metrics, including yield loss, rework rates, logistics resilience, and regulatory risk. Suppliers that can offer consistent lot-to-lot quality, transparent sourcing, and application engineering support are capturing disproportionate value, even when their headline pricing is higher.
Competitive Landscape and Leading Strategies
The competitive field is anchored by a mix of global materials giants, regional specialists, and application-focused innovators. DuPont continues to leverage its polyimide heritage, particularly its Kapton legacy, to serve flexible electronics, display, and high-temperature automotive applications. Its positioning emphasizes long-standing process knowledge, broad qualification history with major OEMs, and the ability to supply substrates that meet stringent thermal and mechanical specifications. 3M complements this profile with a focus on optical clarity, durability, and precision film engineering, targeting display and printed electronics applications where surface quality and dimensional consistency are decisive. Toray and Teijin, together with Sumitomo Chemical and Mitsubishi Chemical, form a strong Asian manufacturing core that combines polyester and polyimide expertise with deep integration into regional electronics and display supply chains. Their advantage lies in scale, proximity to panel and circuit manufacturers, and the ability to tailor film grades to specific lamination and etching workflows.
Beyond mainstream electronics, a distinct competitive cluster has emerged around security and currency substrates. Companies such as CCL Secure, De La Rue, Landqart, and Giesecke+Devrient have built specialized capabilities that combine biaxially oriented polymer films with integrated security features, authentication layers, and printing compatibility. De La Rue, for example, operates an integrated model that couples substrate production with security feature embedding and print readiness, reducing coordination friction for central bank issuance programs. The recent adoption of Q&T Hi-Tech Polymer's domestic PolySecure substrate in Vietnamese currency illustrates how regional producers can capture sovereign issuance cycles by offering localized supply, cost competitiveness, and alignment with national printing infrastructure. This segment demonstrates that polymer substrates are not a monolithic market; competitive advantage often comes from mastering a specific application's certification, security, and logistics requirements rather than competing purely on film thickness or polymer grade.
The market's evolution is being shaped by simultaneous consolidation and specialization. Larger materials groups are acquiring or partnering to secure feedstock access, expand high-performance film portfolios, and broaden regional coverage. At the same time, new entrants are carving out positions through targeted innovations such as thiol-based optical films, RF and microwave-grade substrates, and next-generation display-compatible architectures. Recent pricing actions by major producers highlight the tension in the current environment: several global manufacturers announced material price increases effective in early 2026, citing raw material and production costs. These adjustments are not merely tactical; they reflect a structural recalibration as firms protect margins amid feedstock volatility and compliance investment. Buyers are responding by diversifying supplier bases, locking in longer-term agreements with performance guarantees, and shifting certain certifications in-house to reduce dependency on single-source qualification cycles.
For strategists, the clearest signal is that differentiation is increasingly earned at the intersection of material science, regulatory readiness, and application engineering. Companies that can demonstrate measurable improvements in yield, thermal reliability, or processing speed are winning premium placements, while those competing solely on commodity pricing are facing progressive margin erosion.
Future Trends and Commercial Implications
Several trajectories are likely to define the next three to five years. The first is the continued migration of polymer substrates into higher-complexity electronic architectures. As foldable displays, wearable sensors, and advanced flexible circuits move from premium niches toward broader adoption, substrates will need to satisfy tighter tolerances for dimensional stability, dielectric uniformity, and long-term fatigue resistance. This trend will create opportunities for suppliers that offer co-engineered film systems, including adhesives, cover layers, and surface treatments optimized for specific assembly processes. Manufacturers that provide application engineering support and process validation will capture more value than those selling bare film alone.
Ceramic Substrate Market
A second trend is the deepening influence of regulatory and sustainability mandates on material selection. Chemical restrictions and emissions expectations are unlikely to plateau; they will expand in scope and enforcement intensity. This will favor substrates and processing routes that reduce solvent use, lower heavy-metal dependency, and improve recyclability or end-of-life handling. Companies that proactively redesign offerings around compliance-forward chemistries will gain preferential access to OEMs facing their own procurement standards and public reporting requirements. In parallel, procurement teams will increasingly evaluate suppliers on environmental documentation, traceability, and audit readiness, making these capabilities a commercial differentiator rather than a back-office function.
Worldwide Polished Substrates Market
A third trend is the regional reconfiguration of supply networks. Freight instability, lead-time sensitivity, and currency exposure are prompting buyers to diversify across geographies and to favor suppliers with local or near-local production capacity. This shift creates openings for regional specialists that can deliver reliable volume, faster response cycles, and lower logistics risk, even if they lack the global footprint of multinational incumbents. The resulting landscape will reward agility, transparent communication, and the ability to manage qualification and certification efficiently across multiple jurisdictions.
These trends carry both opportunity and uncertainty. Demand growth is likely to remain positive, but the distribution of value will tilt toward firms that can absorb feedstock and compliance risk without sacrificing performance consistency. Buyers who treat substrates as strategic components rather than commoditized inputs will be better positioned to manage cost volatility and technology transitions.
Actionable Guidance for Decision-Makers
Manufacturers should prioritize application-specific film development and process integration over broad commodity expansion. Investing in co-engineered substrate systems, qualification support, and consistent lot quality will strengthen customer retention and protect margins against price competition. Where feedstock exposure is significant, long-term sourcing agreements, hedging strategies, and alternative polymer pathways should be evaluated to reduce vulnerability to annual volatility swings.
Investors should focus on companies with defensible technical moats, regulatory readiness, and diversified application exposure across electronics, energy, security, and medical uses. Business models that combine material capability with service layers such as engineering support, certification assistance, and regional supply resilience are better positioned to sustain pricing power. Caution is warranted where growth depends primarily on volume throughput without corresponding differentiation in performance or compliance.
PW Consulting
Procurement and sourcing leaders should expand evaluation criteria beyond unit cost to include total cost of ownership, yield impact, lead-time reliability, and regulatory documentation. Multi-supplier strategies, paired with clear performance specifications and shared qualification data, can reduce single-point failures while maintaining competitive tension. Early engagement with suppliers on upcoming material or regulatory changes will also shorten adaptation cycles and lower the risk of production disruption.
For organizations seeking deeper segmentation data, company-level positioning detail, and customized scenario planning across regions and application verticals, the full research report provides expanded datasets and tailored analysis. The complete study maps growth trajectories by material type, application, and region, alongside competitive profiling and procurement risk frameworks, offering a practical reference for strategy development and investment prioritization.
For detailed analysis of this topic, please visit the official page: Worldwide Polymer Substrates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


