



Fresh Meat Packaging Market: How 5.12% CAGR and Plastic Dominance Are Redefining the $5.79B Landscape

The Fresh Meat Packaging Market: Strategic Trends and Commercial Opportunities Through 2032
Market Snapshot and Defining Challenges
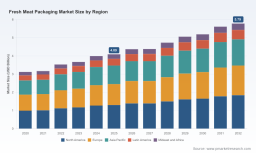
The global fresh meat packaging market has evolved from a commoditized segment into a strategically contested arena where material science, regulatory compliance, and supply chain resilience intersect. Historical trajectory from 2020 through 2025 demonstrates consistent expansion, anchored by steady volume growth in developed retail channels and accelerating modernization in emerging distribution networks. The baseline year value reached approximately 4.09 billion USD, representing a compound annual growth rate of 5.12 percent across the 2026 to 2032 forecast horizon. This trajectory projects revenue climbing toward 5.79 billion USD by 2032, signaling a market that is expanding at a measured but structurally significant pace.
Several structural headwinds define the current inflection point. First, the gap between conventional plastic-dependent formats and rapidly evolving recyclability mandates creates a compliance-cost squeeze. Processors and converters must balance shelf-life performance with design-for-recyclability requirements that increasingly dictate fee structures and market access. Second, raw material volatility has shifted from a cyclical nuisance to a persistent margin pressure. Limited availability of key polymer resins has elevated input costs for trays and films, pushing converters and brand owners to evaluate alternative material pathways that can maintain barrier properties while improving end-of-life outcomes. Third, retail and foodservice procurement models are fragmenting. Case-ready and centralized packaging specifications vary significantly across geographies and retailer tiers, forcing suppliers to navigate a maze of performance, sustainability, and footprint requirements simultaneously.
Vacuum Skin Packaging Market
These challenges are not isolated. They interact to reshape cost structures, dictate formulation and tooling investments, and influence where competitive advantage can be sustained. Companies that treat packaging as a performance and compliance layer rather than a disposable cost center are better positioned to navigate the transition ahead.
Core Drivers Reshaping the Market
Material and design innovation remains the primary engine of differentiation. Mono-material architectures and recyclable polymer structures are advancing rapidly, driven by the need to maintain oxygen and moisture barriers while simplifying downstream sorting and recycling streams. Vacuum skin packaging continues to evolve with tighter film tolerances and integrated equipment logic, enabling retailers to standardize display readiness while extending case life. The shift toward paper-based and fiber-reinforced formats is gaining commercial traction where fresh meat applications demand reduced plastic load and clearer recyclability claims. Innovations in heat-sealable membranes, die-cut lids, and preformed trays are narrowing the historical performance gap between conventional and sustainable formats, creating more options for processors seeking to balance cost, protection, and compliance.
Regulatory momentum is accelerating the pace of change. Extended producer responsibility frameworks are expanding across multiple jurisdictions, with several U.S. states now embedding recycled content and recyclability-based fee schedules that directly affect packaging economics. In parallel, European requirements are reinforcing design-for-recyclability expectations and minimum recycled content thresholds for plastic packaging. These mandates are not static footnotes; they alter the total cost of ownership for packaging portfolios and create financial incentives for early adopters of compliant materials and designs. Producer fees tied to recyclability performance are increasingly influencing sourcing decisions, particularly for high-volume formats such as trays and films used in beef, poultry, and seafood categories.
Pet Food Packaging Market
Demand-side behavior is reinforcing the material transition. Consumers continue to prioritize freshness visibility, portion clarity, and label legibility, while retailers are under growing pressure to demonstrate shelf-level sustainability credentials without compromising product integrity. Processors are responding by standardizing case-ready formats that reduce handling and improve throughput, while also aligning packaging specifications with retailer sustainability scorecards. The result is a more demanding specification environment where protection, presentation, and post-consumer outcomes must be optimized together rather than in sequence.
Cost and supply chain dynamics are reshaping sourcing strategies. Resin availability constraints have elevated film and tray costs, accelerating evaluation of recycled content and alternative materials. At the same time, processing-side efficiency opportunities are attracting attention; adjustments to slaughter line speeds and throughput logistics can unlock meaningful cost savings for meat operations over multi-year horizons, indirectly influencing the packaging specification conversation by altering the cost context in which packaging decisions are made. Companies are increasingly weighing packaging investments against broader operational levers, recognizing that packaging performance and processing efficiency are linked in total landed cost and service reliability.
Competitive Landscape and Leading Strategies
The competitive field is concentrated but diverse, with leaders differentiating through material portfolios, equipment integration, and regional manufacturing footprints. Amcor has built a position around responsible and recyclable flexible and rigid solutions, emphasizing mono-material films and trays tailored to fresh meat applications. Sealed Air maintains a strong presence through specialized vacuum skin packaging, preformed trays, and integrated automation that supports case-ready workflows for beef, pork, lamb, and poultry. Berry Global pursues next-generation vacuum skin and sustainable flexible solutions, focusing on shelf-life extension and improved recyclability profiles.
Regional and fiber-oriented players are expanding the strategic options available to buyers. Pactiv Evergreen continues to serve processors and retailers with foam trays, films, and case-ready solutions that prioritize display readiness and throughput. Huhtamaki emphasizes sustainable fiber-based and flexible packaging, aligning fresh meat applications with evolving recyclability expectations. Mondi has moved aggressively in paper-based mono-material and pulp solutions, pairing tray and film innovations with targeted partnerships and acquisitions that expand production capacity in key regions. Winpak rounds out the flexible segment with heat-sealable membranes, die-cut lids, and processing-focused flexible formats. Sonoco contributes paperboard trays, tubes, and composite packaging, while Coveris has expanded its portfolio across paper-based and flexible sustainable solutions, including dedicated fresh meat ranges and new vacuum skin packaging capacity. Edelmann rounds out the landscape with high-performance packaging solutions and facilities oriented toward fresh meat products.
Recent moves highlight how incumbents are translating strategy into capability. Mondi partnered with Scan Sverige to advance recyclable polypropylene-based mono-material food packaging for fresh meat, signaling a collaborative approach to compliance and performance. In parallel, Mondi completed the acquisition of a pulp mill in Alberta to strengthen sustainable paper-based packaging capacity for North America, illustrating how vertical capacity can be used to secure supply and regional relevance. Coveris introduced a fully recyclable paper-based flexible packaging range for fresh meat and expanded a vacuum skin packaging facility in the UK, reflecting coordinated investment in both material innovation and manufacturing scale. These actions suggest a market where differentiation is increasingly built on material architecture, regional capacity, and the ability to deliver compliant solutions without sacrificing barrier or presentation performance.
The landscape is evolving through both consolidation and specialization. Large converters are broadening portfolios to capture cross-category volume and compliance advantages, while focused players are carving out niches around fiber-based solutions, advanced vacuum skin systems, and regional case-ready formats. New entrants are likely to appear where material innovation intersects with recycling infrastructure readiness, but scale, tooling, and qualification timelines continue to favor established players with proven supply reliability and retail relationships. Concentration among the top firms remains notable, yet the diversity of material pathways and regional demand patterns creates room for differentiated positioning rather than pure price competition.
Forward-looking Trends to 2030 and Beyond
The first trend is the broadening commercial viability of mono-material and recyclable structures for fresh meat. As design-for-recyclability expectations become embedded in procurement and compliance frameworks, formats that simplify sorting and improve recovery outcomes will gain preference in high-volume channels. This favors suppliers that can deliver barrier performance in mono-material architectures, supported by film and tray designs that meet both protection and circularity criteria. The commercial opportunity lies in standardizing these formats across retail ready lines and processor specifications, reducing complexity while improving compliance economics.
A second trend is the growing role of fiber-based and paper-forward solutions in select applications where plastic reduction and recyclability communication provide commercial value. These formats are advancing in areas where presentation, protection, and end-of-life messaging align with retailer and consumer expectations. The opportunity is not universal replacement; it is targeted deployment where fiber-based trays, films, and flexible ranges can meet performance thresholds and simplify sustainability narratives without compromising shelf life or handling efficiency. Success will depend on matching format to application, ensuring that barrier and structural requirements are met while leveraging recyclability positioning where it truly matters.
A third trend is the tightening linkage between packaging strategy and regional compliance economics. Producer responsibility fees, recycled content mandates, and recyclability rules are increasingly shaping total cost profiles and market access. Companies that anticipate these shifts and align material choices with local regulatory trajectories can reduce future rework, avoid fee exposure, and secure preferential positioning with sustainability-conscious buyers. The risk is regulatory fragmentation, where differing requirements across regions complicate portfolio standardization and increase qualification overhead. Firms that manage this tension through modular material platforms and region-specific compliance mapping will navigate the transition more efficiently.
PW Consulting
Potential uncertainties include raw material availability, which can shift the economics of polymer-based versus alternative formats faster than expected, and processing-side changes that alter the cost context of packaging decisions. If resin constraints persist or intensify, the pace of migration toward paper and recycled content could accelerate, while in a more benign supply environment the transition may unfold more gradually. Retail specification volatility and regional recycling infrastructure readiness also remain variables, meaning that the timing and scale of adoption will differ by market and application.
Implications and Action Points for Decision Makers
For packaging manufacturers and converters, the priority is to build material and format flexibility that can absorb regulatory and cost shifts without disrupting supply. Invest in mono-material and recyclable film and tray architectures that maintain barrier performance, and develop modular designs that can be tuned to regional recyclability rules and retailer specifications. Strengthen regional production or sourcing options where compliance economics and resin availability are likely to diverge, and align equipment and lines with formats that reduce qualification friction for case-ready and retail-ready workflows. Validate performance claims with rigorous shelf-life, sealing, and handling data so that sustainability positioning is credible and defensible.
For investors and corporate strategists, the market rewards exposure to companies with clear material-transition roadmaps, credible compliance positioning, and the capacity to execute across regions. Assess portfolios for diversification across plastic, paper-based, and flexible formats, and evaluate the quality of recent partnerships and capacity investments that secure supply and regional relevance. Weigh concentration dynamics against the opportunity set created by material innovation and regional compliance divergence. Focus on players that demonstrate both technical performance and the operational discipline to scale compliant formats without sacrificing service reliability.
For procurement leaders and retail or foodservice buyers, the strategic task is to align specifications with total cost, compliance exposure, and shelf impact rather than unit price alone. Standardize where possible to reduce complexity, but maintain application-specific flexibility for formats where protection and presentation requirements differ. Incorporate recyclability and recycled content expectations into sourcing criteria early, and map those expectations to supplier capability and regional infrastructure readiness. Communicate specifications clearly to reduce rework and qualification delays, and coordinate with suppliers on pilot programs that validate performance and compliance before broad rollout.
The trajectory of the fresh meat packaging market will be shaped by how effectively companies integrate material innovation, compliance strategy, and supply chain resilience. Detailed segmentation, regional dynamics, and scenario-level cost modeling can sharpen these decisions further, and the full PW Consulting research report provides the granular data and tailored analysis needed to translate these trends into concrete plans for specific business contexts.
For detailed analysis of this topic, please visit the official page: Fresh Meat Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


