



LPO Market at 22.91% CAGR: What’s Really Driving the $125.85B Surge to 2032

The Legal Process Outsourcing Market: Strategic Shifts and Growth Horizons (2025–2032)
The legal process outsourcing (LPO) sector has transitioned from a cost-arbitrage experiment into a core operational function for corporations, law firms, and compliance teams worldwide. Over the past five years, the market has demonstrated consistent expansion, with revenues climbing from approximately 11.0 billion USD in 2020 to nearly 30 billion USD by 2025. The trajectory continues upward, with annual growth momentum expected to push the sector past 125 billion USD by 2032. At a compound annual growth rate of roughly 22.9 percent across the 2026–2032 forecast window, LPO is outpacing many adjacent professional services categories, reflecting a structural recalibration of how legal work is sourced, managed, and delivered.
This growth is not merely a function of volume expansion. It reflects a deeper transformation in how organizations approach legal capacity, regulatory complexity, and technology integration. For executives, investors, and procurement leaders, the LPO landscape now offers a mix of established scale players, specialized capability providers, and emerging technology-driven models. Navigating this environment requires a clear understanding of where value is being created, where operational friction persists, and which strategic moves are separating consistent performers from the rest of the field.
Healthcare BPO Market
Market Realities and Core Challenges
The LPO market has reached a scale where traditional outsourcing playbooks no longer apply uniformly. Organizations today are leveraging external legal operations for everything from high-volume document review to regulatory monitoring, contract lifecycle management, and specialized intellectual property support. The breadth of services has expanded significantly, and the revenue base now spans multiple service categories with varying maturity levels. Litigation support and e-discovery workflows remain a substantial portion of the service mix, while contract management, regulatory and compliance services, and legal research functions have grown in strategic importance as internal legal teams face increasing workloads and tighter budgets.
Despite the strong growth profile, the industry faces several structural challenges that will shape its next phase of development.
- Quality and consistency at scale. As volumes increase and service delivery crosses multiple jurisdictions, maintaining consistent quality standards becomes more difficult. Legal work is inherently high-stakes, and errors in contract review, compliance monitoring, or discovery processes can carry significant financial and reputational consequences. Vendors must balance speed and cost efficiency with rigorous quality controls, which often requires layered review processes, specialized training, and robust performance metrics.
- Data security, privacy, and cross-jurisdictional compliance. Legal outsourcing frequently involves transferring sensitive information across borders, which introduces regulatory complexity. Data protection requirements, industry-specific confidentiality obligations, and evolving cross-border data transfer rules create operational hurdles for providers and clients alike. Delivery models must be designed with security architecture, access controls, and compliance monitoring built in from the start rather than treated as add-ons.
- Talent availability and capability gaps. The LPO sector depends on a blend of legal knowledge, process discipline, and increasingly technical skills. Demand for professionals who can operate across legal workflows, data analytics, and AI-assisted tools is rising, but supply remains uneven across regions. Provider organizations that can develop, retain, and continuously upskill talent gain a meaningful advantage, while those relying on purely labor-cost arbitrage face growing pressure as automation absorbs more routine tasks.
These challenges are not static barriers; they are becoming strategic differentiators. Providers that design their operating models around quality assurance, secure data handling, and talent development are better positioned to capture higher-value work, while those that compete primarily on price are likely to face margin compression and client churn as buyers become more sophisticated.
Core Drivers Reshaping the Market
The expansion of the LPO sector is being driven by a combination of technological, regulatory, demand-side, and cost-structure forces. These drivers interact with one another, creating feedback loops that accelerate adoption in certain segments while reshaping competitive expectations across the broader market.
Technology Innovation as a Core Enabler
Artificial intelligence and automation are no longer peripheral tools in legal operations; they are increasingly embedded in how work is scoped, executed, and reviewed. Machine-assisted document review, contract analysis, legal research, and compliance monitoring are reducing turnaround times and allowing provider teams to focus on higher-judgment tasks. The shift is not simply about replacing manual effort. It is about re-architecting workflows so that technology handles the repetitive, high-volume components while human expertise is applied where nuance, interpretation, and client-specific context matter most.
Recent industry activity illustrates how seriously providers are investing in this direction. Several leading firms have moved to strengthen their AI-enabled service lines and data capabilities, integrating legal operations support with more advanced analytics, contract management platforms, and compliance workflows. In parallel, partnerships aimed at deploying end-to-end platforms with stronger security and compliance controls are becoming more common, particularly where cross-border data handling is involved. These moves signal that technology is now a competitive baseline rather than a differentiator reserved for a few early adopters.
Regulatory Complexity and Monitoring Demands
The regulatory environment for large corporations and regulated industries continues to become more demanding. Environmental, social, and governance expectations, data privacy regimes, sector-specific compliance obligations, and cross-border operational requirements have all increased the volume and urgency of legal and compliance work. This is pushing organizations to seek external support not only for episodic litigation or transaction work, but also for ongoing monitoring, reporting, and risk management.
A notable example is the introduction of managed services focused on ESG compliance, including real-time regulatory monitoring and reporting. Such offerings reflect a broader trend: clients increasingly want continuous, structured support rather than ad hoc project-based assistance. As regulatory expectations become more dynamic, providers that can combine legal knowledge with operational monitoring and reporting capabilities are well placed to capture recurring revenue streams.
Demand-Side Shifts in Legal Capacity and Procurement
Internal legal departments are under growing pressure to manage expanding workloads with constrained headcount and budgets. At the same time, corporate procurement and legal operations teams are becoming more deliberate about how they source external support. The conversation has evolved from simple cost reduction to total value, including speed, quality, predictability, security, and the ability to scale up or down as needs change. This has encouraged a shift toward managed services and longer-term partnerships rather than one-off engagements.
The result is a more diverse buyer profile. Some organizations are building hybrid models in which internal teams oversee strategy and high-judgment work while external providers handle volume-driven processes. Others are using LPO providers to fill capability gaps in specialized areas, such as multilingual litigation support, intellectual property analytics, or jurisdiction-specific compliance. In both cases, the common theme is flexibility: buyers want providers who can adapt to changing caseloads, regulatory demands, and internal priorities without sacrificing control or consistency.
Cost Structure and Delivery Model Evolution
Cost remains a foundational driver, but the way cost advantage is achieved is changing. Pure labor-cost arbitrage is increasingly insufficient in segments where quality, turnaround speed, and technology integration matter most. Providers are restructuring delivery around a blend of onshore, nearshore, and offshore locations, with secure facilities and specialized centers supporting specific legal domains or jurisdictional requirements. This geographic diversification helps manage cost while also addressing data residency, language, and legal system familiarity.
At the same time, operational efficiency is being improved through process standardization, workflow automation, and better portfolio management. Organizations that treat legal outsourcing as a managed operation—complete with governance, performance tracking, and continuous improvement—are more likely to realize durable savings and service reliability than those that rely on transactional, project-by-project purchasing.
Competitive Landscape and Leading Strategies
The LPO market remains moderately fragmented, with the top three providers accounting for a combined share in the high twenties and the top five reaching just over a third of total market revenue. This structure implies that while scale players have meaningful presence, there is still substantial room for specialization, regional strength, and capability-based differentiation. The competitive dynamic is less about a single dominant model and more about how providers combine scale, technology, domain expertise, and delivery footprint.
Strategic Positioning Among Key Players
Several established providers illustrate different pathways to competitive advantage.
- Integreon Managed Solutions has focused on AI-powered legal operations support spanning contract management, document review, legal research, and compliance services. Its recent strategic collaboration with PwC for legal managed services in the EMEA region, along with the opening of a new secure delivery center in Cape Town to support offshore outsourcing with an emphasis on English common law jurisdictions, reflects a strategy centered on both geographic expansion and partnership-driven scale.
- Elevate Services has positioned itself around AI-powered legal services that include litigation support, contract management, legal operations consulting, and managed services. Its acquisition of a specialist in Chinese, Japanese, and Korean language support for litigation, together with a legal data and AI consulting company, demonstrates a push to deepen multilingual capability and data/AI advisory strength in a single move.
- QuisLex has built its offering on managed services for document review, contract management, compliance, litigation support, and legal spend optimization. Its launch of a managed service focused on ESG compliance with real-time regulatory monitoring and reporting shows an effort to move beyond traditional litigation-support work into recurring, compliance-driven engagements.
- Epiq Global continues to emphasize technology-enabled legal and compliance services, including e-discovery, class actions, bankruptcy, and outsourcing for law firms and corporations. Its profile reflects the importance of scale infrastructure and specialized case-type expertise in high-volume, process-intensive work.
- Axiom Law has carved out a position around on-demand legal talent, secondments, and AI-enabled services supporting in-house legal teams and complex projects. This model highlights the value of flexible talent deployment and close integration with internal legal functions, especially for organizations that want external support without fully handing off operational control.
- UnitedLex has focused on data-driven legal and litigation support services, including e-discovery, patent analytics, and case management. Its strategic partnership with a major cloud provider to deploy an advanced end-to-end e-discovery platform with enhanced data security and cross-border compliance capabilities underscores the increasing importance of secure technology infrastructure in competitive positioning.
How the Landscape Is Evolving
Three patterns are evident in the current competitive environment.
- Capability-driven consolidation. M&A and strategic partnerships are being used to add multilingual capacity, data and AI consulting, and broader managed-service portfolios. This suggests a market in which buyers increasingly want integrated solutions rather than narrow point services.
- Geographic and jurisdictional specialization. Providers are expanding or refining delivery centers to align with common law frameworks, language requirements, and regional compliance expectations. This reflects a recognition that legal outsourcing is not a uniform global service; jurisdictional familiarity and data handling rules shape where and how work can be performed.
- Platform and security as competitive foundations. Partnerships and platform investments focused on secure, end-to-end processing are becoming more prominent, particularly for e-discovery and other data-sensitive workflows. In a market where information security and regulatory compliance are central concerns, technology infrastructure is increasingly part of the value proposition rather than a back-office utility.
For new entrants, the bar is rising. Pure cost-based entry is harder to sustain as automation reduces the advantage of low-cost labor alone, and buyers are more capable of evaluating quality, security, and service design. New players that can bring specialized domain expertise, strong technology integration, or a clear regional and jurisdictional fit have a more credible path than those offering only generalized volume services.
Forward Trends and Commercial Opportunities
Looking ahead across the next three to five years, several trends are likely to shape how the LPO market develops and where commercial opportunities emerge.
AI-Embedded Legal Operations Become Standard Configuration
The integration of AI and automation into legal workflows is expected to deepen, moving from selected use cases to broader operational baselines. Document review, contract abstraction, legal research, compliance monitoring, and matter management are all candidates for increased automation, with human reviewers focusing on exception handling, strategic judgment, and client-specific interpretation. For providers, this trend creates opportunities to redesign service offerings around technology-assisted efficiency, predictable turnaround times, and measurable quality outcomes. For buyers, it opens the possibility of scaling legal support without proportionally increasing headcount, provided vendor selection emphasizes workflow design and governance rather than tool presence alone.
Compliance and ESG-Linked Services Grow as Recurring Revenue Engines
As regulatory expectations continue to expand, managed services tied to regulatory monitoring, compliance reporting, and ESG-related obligations are likely to become more prominent. Unlike episodic litigation or transaction support, these engagements can create more predictable, recurring demand. Providers that can combine real-time monitoring, structured reporting, and cross-functional coordination with legal and compliance teams are well positioned to capture this demand. For enterprises, the opportunity lies in moving from reactive compliance support to continuous operational oversight, reducing the risk of late responses to regulatory changes and improving internal accountability.
Regional Rebalancing and Jurisdiction-Focused Delivery Models
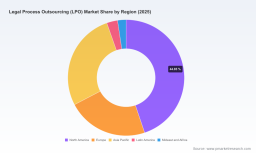
The geographic distribution of LPO activity is expected to remain dynamic. While some regions already account for a substantial share of market activity, others are positioned for faster growth during the forecast period as legal demand, regulatory complexity, and delivery infrastructure evolve. Western Europe, for example, is widely expected to emerge as one of the fastest-growing regions during the forecast window, reflecting expanding compliance needs and increasing adoption of external legal operations support. At the same time, Asia Pacific continues to hold a leading share, underscoring the region’s established role in global legal service delivery. For providers, this environment favors deliberate investment in regional capabilities, language coverage, and jurisdiction-specific expertise. For buyers, it creates options for aligning delivery location with legal framework familiarity, data residency requirements, and cost considerations.
Legal Practice Management Software Market
Risks and Uncertainties to Monitor
Despite the strong growth outlook, several uncertainties could affect the pace and shape of market development. Regulatory changes around data transfer, privacy, and cross-border operations may increase compliance costs and slow certain delivery models if requirements become more restrictive. Security incidents or quality failures in high-stakes legal work could also shift buyer caution and raise due-diligence requirements. In addition, rapid automation could compress margins for providers that have not reinvested in workflow redesign, talent development, or higher-value service capabilities. Finally, macroeconomic fluctuations may influence how aggressively organizations expand external legal support, even if the underlying structural drivers remain intact.
Implications for Decision-Makers
The current LPO environment rewards deliberate strategy over reactive purchasing. Executives, investors, and procurement leaders each face a distinct set of priorities, but all benefit from a clearer view of where the market is heading and how to position accordingly.
For Corporations and Legal Operations Leaders
- Move from project-based buying to managed service design. Where possible, structure engagements around governance, service-level expectations, quality metrics, and continuous improvement. This reduces variability and makes it easier to scale support as workload fluctuates.
- Define security and compliance requirements before sourcing. Data handling, jurisdiction, access controls, and reporting expectations should be part of the initial scoping process, not negotiated after the fact. Providers with built-in secure infrastructure and cross-border compliance capabilities will be easier to integrate into sensitive workflows.
- Use external support to build capability, not just capacity. The most valuable engagements often combine volume handling with knowledge transfer, process improvement, and access to specialized expertise. This helps internal teams evolve while maintaining strategic control over high-judgment work.
For Investors and Strategic Allocators
- Focus on models with durable differentiation. Sustainable advantage is increasingly tied to technology integration, quality systems, multilingual and jurisdiction-specific capability, and recurring compliance-oriented services rather than labor-cost advantage alone.
- Watch consolidation and partnership activity as signals. Acquisitions and collaborations that add language coverage, data and AI advisory strength, or platform security capabilities often indicate where the market is heading and which capability gaps are being closed.
- Evaluate exposure to regulatory-driven demand. Segments tied to ongoing compliance monitoring, ESG reporting, and data-sensitive discovery workflows may offer more predictable demand profiles, though they also carry higher expectations for security, accuracy, and operational discipline.
For Procurement and Sourcing Professionals
- Evaluate total value, not just unit cost. Speed, quality, security, scalability, and the ability to manage changing requirements can matter as much as price, especially in complex or high-volume legal work.
- Build vendor portfolios by capability, not by brand alone. Different providers are stronger in different areas, such as litigation support, contract management, IP analytics, or compliance monitoring. A diversified sourcing approach can match work types to the most suitable providers.
- Embed performance management into ongoing relationships. Regular review of quality, turnaround, cost predictability, and security compliance helps maintain alignment and reduces the risk of service drift over time.
Conclusion
The legal process outsourcing market is entering a phase defined by greater technological integration, more demanding compliance expectations, and a growing preference for managed, scalable service models. Growth momentum remains strong, but the competitive edge is shifting toward providers that can combine secure infrastructure, quality assurance, jurisdictional awareness, and AI-enabled workflows with the ability to support recurring legal and compliance needs. For organizations seeking to use LPO strategically, the priority is no longer simply finding lower-cost support. It is selecting partners and service designs that improve speed, control, and resilience while allowing internal teams to focus on the work that most requires judgment and accountability.
PW Consulting
For decision-makers needing a more detailed view of service-line dynamics, regional trajectories, competitive positioning, and custom sourcing implications, the full research report provides a deeper breakdown of market segments, company-level developments, and forward scenarios. It is designed to support more granular planning, from service portfolio design and vendor evaluation to investment prioritization and risk assessment.
For detailed analysis of this topic, please visit the official page: Legal Process Outsourcing (LPO) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


