



Lab Glassware Market 2026: The 4.7% CAGR Trajectory and What It Reveals

Navigating the Laboratory Glassware Market: Strategic Trends and Commercial Imperatives
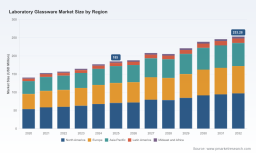
The laboratory glassware market is entering a phase of structural transformation, driven by technological refinement, evolving regulatory expectations, and shifting procurement behaviors across end-user segments. Valued at approximately USD 185.0 million in 2025, the market has expanded from USD 140.5 million in 2020, reflecting steady compounding growth over the post-pandemic period. Forward projections indicate a trajectory toward USD 253.28 million by 2032, with a compound annual growth rate of 4.7 percent across the forecast horizon. This expansion is not merely incremental; it reflects a market responding to heightened precision requirements, supply chain recalibration, and the integration of traceability and standardization into routine laboratory operations. For executives, investors, and procurement leaders, the window to align product portfolios, capital allocation, and sourcing strategies with these underlying shifts is opening now.
Market Snapshot: Growth Trajectory and Structural Realities
The market’s historical performance from 2020 through 2025 demonstrates a consistent upward curve, with annual revenue crossing the USD 160 million threshold in 2022 and accelerating into the USD 170–185 million range by mid-decade. The forecast period from 2026 to 2032 projects continued expansion, though the growth path is not uniform. The transition from USD 185.0 million in 2025 to the projected USD 253.28 million in 2032 implies that demand generation will increasingly depend on application-specific precision, regulatory compliance, and regional capacity dynamics rather than broad volume expansion alone.
At the structural level, the market operates with moderate concentration. The top three participants collectively command roughly 45 percent of total revenue, while the top five extend that share to approximately 60 percent. This concentration pattern indicates that established manufacturers retain meaningful pricing power and distribution leverage, yet the remaining 40 percent of the market remains fragmented across regional players, specialty suppliers, and cost-focused producers. Such a landscape creates both defensive moats for incumbents and entry points for well-positioned challengers, particularly where customization, compliance documentation, or supply chain reliability becomes a differentiating factor rather than a baseline expectation.
The market is also characterized by a clear hierarchy of product and application relevance. Volumetric measurement tools and general containment vessels continue to anchor demand, while pipettes and precision dispensing instruments represent a growing precision segment. In application terms, pharmaceutical and biotechnology workflows consume the largest share of glassware volumes, followed by academic and research environments, clinical diagnostic settings, and ancillary use cases. This distribution indicates that demand is increasingly tied to regulated, high-throughput, or quality-sensitive environments where measurement accuracy, material consistency, and documentation traceability carry direct operational and compliance implications.
Defining Challenges and Inflection Points
Despite the favorable growth baseline, the industry faces several interconnected challenges that will shape competitive outcomes over the next three to five years.
Precision Standards and Calibration Expectations
The laboratory glassware sector is moving toward tighter standardization for measurement-critical items, particularly in one-mark volumetric instruments. Updated international requirements are reinforcing calibration consistency, marking accuracy, and manufacturing repeatability. For producers, this translates into higher compliance costs, more rigorous quality control protocols, and the need to align product specifications with evolving normative references. Laboratories and procurement teams, in turn, are placing greater weight on certification documentation and conformance assurance, raising the barrier for sellers that cannot demonstrate consistent specification integrity across batches.
Material Consistency and Thermal Performance Requirements
Borosilicate glass remains the dominant material foundation because of its thermal shock resistance and chemical durability. While this dominance provides stability, it also constrains rapid material substitution and heightens sensitivity to raw material quality, melting consistency, and forming precision. Variability in feedstock composition or furnace control can affect wall thickness uniformity, dimensional tolerance, and long-term reliability in temperature-cycling applications. Manufacturers that treat material consistency as a core process capability rather than a commodity input will be better positioned to capture demand from environments where thermal stress and chemical exposure are routine.
Traceability, Documentation, and Procurement Digitalization
A quiet but consequential shift is underway in how laboratories track, verify, and manage glassware inventory. The introduction of QR-coded product items, enhanced batch traceability, and digital catalog integration reflects growing demand for item-level identification and audit-ready documentation. This trend is especially relevant in regulated environments where lot traceability, usage history, and replacement scheduling influence both operational efficiency and compliance reviews. Suppliers that enable faster verification, clearer product identification, and smoother integration with laboratory inventory systems can reduce friction in the procurement cycle while strengthening supplier-of-choice positioning.
Core Drivers Reshaping the Market
Regulatory Alignment and Standardization Momentum
The push toward harmonized international standards is one of the most consequential forces in the market. Updated normative references for one-mark volumetric flasks are establishing clearer expectations for dimensional accuracy, marking, and conformity testing. Rather than treating standards as static compliance checkboxes, leading manufacturers are using them as product development anchors, aligning tooling, inspection routines, and documentation with anticipated certification expectations. For buyers, the practical implication is that specification sheets and conformity evidence are becoming more comparable across suppliers, which can compress differentiation based solely on branding and shift attention toward reliability, lead-time consistency, and technical support.
Innovation in Safety and Durability Features
Product-level innovation is increasingly focused on reducing breakage risk, improving handling safety, and extending service life in demanding workflows. Coated laboratory bottles with enhanced shatter protection illustrate this direction, addressing both workplace safety and total cost of ownership concerns. In settings where glassware is handled frequently, moved across benches, or used in environments with vibration, temperature variation, or incidental impact, safety-oriented design features can differentiate a product line and influence purchasing decisions beyond base price comparisons. Innovation is also extending to interchangeability, filtration-compatible configurations, and specialized vessel geometries that reduce workflow adaptation time.
Demand-Side Shifts in Regulated and Research Workflows
End-user behavior is evolving as laboratory workflows become more standardized, auditable, and throughput-sensitive. Pharmaceutical and biotechnology environments continue to absorb the largest share of demand because measurement precision, contamination control, and reproducibility carry direct implications for development timelines and quality outcomes. Academic and research institutions remain a substantial demand base, but their procurement patterns are increasingly influenced by budget cycles, shared instrumentation models, and the need for broad compatibility across teaching and research labs. Clinical diagnostic settings add another layer of complexity, where glassware usage is tied to laboratory service delivery and reimbursement frameworks that do not always map cleanly onto individual product codes. This fragmentation in reimbursement and procurement pathways means that suppliers must navigate both technical specifications and institutional purchasing logic.
Supply Chain and Cost Structure Pressures
Cost dynamics in the market are influenced by raw material availability, energy intensity in glass melting and forming, and logistics complexity across regions. Borosilicate glass production requires controlled high-temperature processing, which makes energy pricing and furnace utilization relevant to cost structure. At the same time, regional demand patterns are reshaping sourcing strategies. North American and European markets maintain substantial demand bases, while Asia Pacific represents a growing volume center supported by expanding research infrastructure, manufacturing capacity, and domestic consumption. The result is a supply environment in which regional presence, export capability, and inventory positioning increasingly matter for competitive responsiveness. Companies that can combine consistent production output with dependable distribution and clear compliance documentation are gaining an advantage in tenders and recurring procurement programs.
Competitive Landscape and Strategic Positioning
The competitive environment blends incumbent scale, regional manufacturing strength, and niche specialization. Companies with established brand portfolios and broad product ranges are using brand trust, specification consistency, and application coverage to defend share. At the same time, regional manufacturers are gaining relevance by offering competitive cost profiles, adaptable production runs, and growing conformity to local certification expectations. This dual dynamic creates a market where scale and reputation matter, but they no longer guarantee automatic preference if a competitor can match specifications and improve traceability, lead time, or safety features.
Differentiation Patterns Among Leading Players
Several strategic positioning patterns are evident across the competitive set.
-
Brand-led premium positioning: Multi-brand manufacturers leverage well-known product lines and long-standing laboratory recognition to anchor trust in precision measurement and material quality. Their differentiation often rests on specification consistency, broad application coverage, and established distribution relationships.
-
Customization and specialty systems: Some suppliers emphasize custom configurations, reaction systems, and application-specific geometries. This approach is particularly relevant for research environments that require non-standard vessel dimensions, specialized port configurations, or integrated handling solutions.
-
Standards-aligned volume manufacturing: Regional producers focus on USP, ASTM, and local certification alignment, offering general laboratory glassware and consumables at competitive cost points. Their relevance grows where procurement teams prioritize specification compliance, batch consistency, and pricing predictability.
Glassware Market -
Traceability and catalog modernization: Suppliers introducing QR-coded items, updated catalogs, and improved identification systems are reducing friction in inventory verification and lot tracking. This is becoming a practical value-add, especially for repeat purchasers managing large SKU counts or regulated usage environments.
-
Safety-enhanced product extensions: Manufacturers introducing shatter-protection coatings, coated bottles, and handling-safety features are targeting total cost of ownership and workplace risk reduction. This positioning resonates in environments where breakage-related disruptions, cleanup, and replacement frequency influence operating costs.
PW Consulting
Evolution of the Competitive Structure
The market is unlikely to consolidate into a single dominant configuration over the near term. Instead, the structure appears to be evolving through selective integration, regional capacity expansion, and specialization by workflow. Incumbents are defending core positions by strengthening product reliability, demonstration value at major industry events, and application-aligned product launches. Regional producers are expanding relevance by combining cost efficiency with growing conformity to certification and standards expectations. At the same time, new entrants and expanders can gain traction by addressing unmet needs in traceability, safety, specialized geometries, or regional service responsiveness. The practical outcome is a landscape where competitive advantage is increasingly defined by the intersection of specification integrity, documentation readiness, and operational convenience rather than by brand alone.
Forward Outlook: Three Trends Shaping the Next Three to Five Years
Trend 1: Standards-Driven Harmonization of Precision Glassware
Over the next several years, the emphasis on harmonized requirements for measurement-critical items is likely to intensify. One-mark volumetric instruments will continue to serve as a focal point for calibration discipline, and suppliers that proactively align manufacturing controls, inspection protocols, and documentation with evolving normative expectations will face fewer friction points in regulated procurement. The commercial implication is that quality documentation and specification consistency will become more central to supplier selection, and companies that treat conformance as a design and process priority rather than an after-the-fact certification activity will be better positioned for repeat business in quality-sensitive environments.
Trend 2: Safety, Durability, and Total-Cost-of-Ownership Framing
Demand for safety-enhanced and durability-oriented products is expected to grow as laboratories and procurement teams evaluate glassware not only by unit price but by handling risk, breakage frequency, replacement cycles, and workflow interruption. Coated bottles, protective designs, and improved handling characteristics can shift purchasing conversations toward operational outcomes. This trend creates opportunity for manufacturers that can demonstrate measurable benefits in safety and lifecycle performance, especially where laboratory staffing constraints, training variability, or high-throughput handling increase exposure to breakage and handling errors.
Trend 3: Digital Traceability and Procurement System Integration
QR-enabled identification, updated product catalogs, and improved traceability are early indicators of a broader move toward inventory digitization and audit-readiness. As laboratories seek faster verification, clearer lot history, and easier integration with procurement and inventory systems, suppliers that provide machine-readable identification and well-structured product data will reduce administrative burden and improve buyer confidence. This trend is particularly relevant for recurring procurement programs, multi-site institutions, and regulated settings where documentation continuity matters. The opportunity lies not only in labeling, but in supporting buyers with data consistency, clear product hierarchy, and compatibility with modern procurement workflows.
Risks and Uncertainties to Monitor
Several risks could temper or redirect these trends. Regulatory and standards implementation can vary by region and by procurement cycle, creating uneven adoption timelines. Raw material and energy cost volatility may pressure margins, particularly for producers with limited pricing flexibility or high exposure to energy-intensive forming processes. Reimbursement and procurement structures in diagnostic and clinical service settings remain complex, which can obscure demand signals and slow purchasing decisions. In addition, the fragmented portion of the market can intensify price competition, especially where differentiation is limited to specification parity and brand recognition. Companies that fail to strengthen traceability, documentation, and safety value propositions may find themselves competing primarily on price in an increasingly demanding specifications environment.
Actionable Guidance for Decision-Makers
For Manufacturers and Brand Owners
Strengthen the link between product design and compliance readiness. Where measurement-critical items are concerned, investment in process control, inspection discipline, and conformity documentation can reduce friction in regulated procurement and improve repeat-order reliability. Equally important is the differentiation path beyond base specifications: safety coatings, handling improvements, traceability features, and application-specific geometries can shift purchasing conversations toward operational value. Manufacturers should also evaluate regional certification expectations and determine where local compliance, service responsiveness, or cost-positioning can open access to growing demand centers. Participation in major industry exhibitions and consistent product demonstration can reinforce visibility, but the durable advantage will come from repeatable conformance, clear documentation, and the ability to reduce buyer risk across the ordering and use cycle.
For Investors and Strategic Allocators
Evaluate exposure through the lens of specification integrity, regional capacity, and value-added differentiation rather than aggregate volume alone. Segments tied to precision measurement, safety-enhanced products, and traceability-enabled catalog systems are likely to see stronger demand resilience because they address compliance, handling risk, and procurement efficiency. It is also important to assess the regional balance of demand and production capacity, since energy intensity, raw material access, and logistics can shape margin durability. Companies that combine stable production quality with clear documentation and differentiated product features may offer more defensible positioning than those reliant on undifferentiated commodity supply. In addition, investors should monitor how reimbursement and procurement structures evolve in diagnostic-linked settings, since those frameworks influence demand timing even when the product itself is not directly coded.
For Procurement Leaders and Laboratory Operators
Expand evaluation criteria beyond unit price to include specification conformance, documentation completeness, handling safety, and traceability support. In precision-sensitive workflows, the cost of measurement uncertainty, replacement delays, and compliance friction can outweigh small differences in list price. Suppliers that provide clearer product identification, reliable conformity evidence, and efficient replenishment processes can reduce administrative burden and improve continuity. Procurement teams should also consider total cost of ownership when breakage, handling risk, and replacement frequency are material, since safety-enhanced options may lower downstream disruptions even if upfront pricing differs. Where multi-site or regulated environments are involved, standardized product data and traceable lot management can simplify audit preparation and inventory control.
From Insight to Execution
The laboratory glassware market is moving from a period of steady expansion to one where differentiation is increasingly determined by precision discipline, safety enhancement, traceability readiness, and regional execution. The baseline growth trajectory remains constructive, but the more valuable question for decision-makers is not whether the market will continue to grow, but which capabilities will earn preference as specifications tighten and procurement becomes more documentation-driven. Manufacturers that align product development with standards expectations, reinforce material and process consistency, and reduce operational friction for buyers can convert market-wide growth into share gains. Investors and procurement leaders, meanwhile, can use these signals to prioritize exposure, negotiate with clearer evaluation criteria, and reduce hidden cost risks in precision-sensitive workflows.
Worldwide Laboratory Glass Container Market
For organizations that need a granular view of regional demand splits, product-type dynamics, application-level consumption patterns, and company-specific competitive positioning, a more detailed research view can help translate these high-level trends into segment-specific strategy. Access to the full breakdown supports scenario planning, sourcing decisions, and portfolio prioritization with finer granularity than is possible in a market overview alone.
For detailed analysis of this topic, please visit the official page: Laboratory Glassware Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


