



Polyphenylene Sulfide Fibers Market: How 4.7% CAGR and Filtration Demand Reshape 2032

The Polyphenylene Sulfide Fibers Market: Strategic Trends and Commercial Opportunities in a High-Performance Materials Landscape
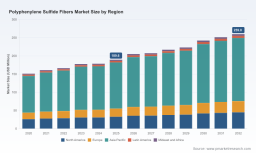
The global market for polyphenylene sulfide fibers has entered a phase of steady, value-driven expansion. Valued at approximately 151.2 million USD in 2020 and reaching roughly 189.6 million USD by 2025, the market is projected to grow to around 259.8 million USD by 2032, reflecting a compound annual growth rate of 4.7 percent over the forecast period. This trajectory signals a mature yet resilient industry where demand is increasingly tied to high-performance applications rather than volume-led commoditization. For executives, investors, and procurement leaders, the question is no longer whether PPS fibers will grow, but how the competitive landscape, cost structure, and regulatory environment will reshape who captures value in the next cycle.
Despite the consistent growth profile, the market is navigating several structural inflection points. First, margin compression is becoming a reality as energy-intensive production collides with tightening environmental controls and rising utility costs. Second, geopolitical and trade dynamics are introducing uncertainty around cross-border sourcing, particularly as major economies reassess anti-dumping frameworks and regional supply dependencies. Third, demand is shifting from generic filtration uses toward more specialized, specification-driven applications that reward technical differentiation and consistent quality. These forces are redefining the baseline for competitive performance and forcing companies to rethink scale, innovation, and supply chain architecture.
Innovation at the Fiber Level: Performance Trumps Volume
Technical advancement remains the most powerful growth lever in this market. The industry is moving beyond baseline heat and chemical resistance toward engineered fiber architectures that solve specific operational pain points. Trilobal cross-section designs, for example, have demonstrated measurable improvements in dust collection efficiency for filtration systems, while new flame-retardant grades are opening pathways into high-voltage electrical insulation where safety margins are non-negotiable. Simultaneously, bio-based feedstock initiatives are beginning to reshape the sustainability narrative, offering a credible route for buyers under pressure to reduce embodied carbon without sacrificing performance. These innovations are not incremental tweaks; they are creating application-specific value pools that command pricing resilience and longer-term customer lock-in.
Regulatory Realignment and the Trade Policy Variable
Policy and regulatory shifts are becoming a decisive factor in sourcing strategy. Environmental controls in key production regions have already influenced raw material pricing, with p-dichlorobenzene costs rising sharply in 2024 as tightened standards constrained supply. At the same time, trade policy dynamics are entering a new phase. The initiation of a sunset review investigation into anti-dumping measures on imports of polyphenylene sulfide from Japan and other countries signals that tariff and duty environments may be recalibrated in the near term. For multinational buyers and producers alike, this creates a dual challenge: maintaining supply continuity while preparing for potential cost volatility and redirected logistics. Companies that treat compliance and trade exposure as strategic variables rather than administrative hurdles will be better positioned to navigate procurement disruptions.
Demand-Side Transformation: From Filtration Dominance to High-Performance Diversification
End-use demand continues to be anchored by filtration applications, which remain the largest consumption segment. Bag filters in industrial dust collection and emission control systems represent a core demand driver, supported by stricter air quality standards and the need for durable, high-temperature-resistant media. However, the most notable shift is the growing interest in insulation materials and engineering applications where PPS fibers are being evaluated for thermal stability, chemical resistance, and long service life. Procurement behavior is also evolving: buyers are increasingly specification-driven, evaluating total cost of ownership rather than unit price alone. This change rewards suppliers that can demonstrate consistent grade quality, technical support, and application engineering capability. It also creates an opening for fiber producers to expand into adjacent high-performance segments where differentiation is achievable.
Cost Structure and Supply Chain Pressure
The economics of PPS fiber production are increasingly sensitive to energy intensity and raw material availability. Producing one metric ton of PPS requires approximately 3,200 kWh of electricity, which places a premium on regional energy tariffs and grid reliability. In markets with high or volatile electricity costs, this translates directly into margin pressure and can influence plant location decisions, capacity timing, and pricing strategies. At the same time, the supply chain is experiencing selective consolidation and regional rebalancing. Capacity expansions and targeted acquisitions are being used to strengthen local market access and reduce exposure to long logistics chains. These moves reflect a broader industry recognition that resilience and proximity to key end markets are becoming as important as scale alone.
Competitive Landscape and Strategic Positioning
The market is moderately concentrated, with the top three players accounting for roughly 35.8 percent of share and the top five reaching approximately 42.6 percent. This concentration suggests a landscape where scale and brand recognition matter, yet enough fragmentation remains to allow differentiated entrants to compete on technical performance, regional presence, or application specialization. Leadership in this market is increasingly defined by how effectively a company aligns product architecture, capacity strategy, and regional access with the evolving needs of specification-driven buyers.
Japanese and European Incumbents: Engineering Heritage and Application Depth
Several established manufacturers have built strong positions by emphasizing application-specific fiber grades and long-standing technical credibility. Leading PPS fiber producers have focused on high-temperature and chemical-resistant grades tailored for bag filters and insulation, reinforcing their relevance in industrial filtration and demanding engineering environments. Other major players offer PPS fiber variants with superior heat, chemical, and hydrolysis resistance across yarn, fabric, and non-woven formats, broadening their reach into both filtration and high-performance industrial uses. A notable differentiator in the market has been the development of trilobal cross-section fibers designed specifically to improve dust collection efficiency, a clear example of structural innovation translating into measurable performance gains. European suppliers have also maintained a presence with fiber grades suitable for monofilament and multifilament extrusion in high-performance engineering applications, positioning themselves in niches where precision and consistency are critical.
Phosphorus Pentasulfide Market
Regional Expansion and Capacity Strategy
Capacity and supply chain strategy are becoming central to competitive positioning. Recent activity includes the completion of an acquisition of a regional PPS fiber manufacturing plant in Southeast Asia, a move aimed at strengthening supply chain resilience and improving market access. In parallel, capacity expansions by major producers in China are signaling a continued push to serve both industrial and automotive-adjacent demand more efficiently. These developments point to a market that is not only growing but also reconfiguring its geographic footprint. For buyers and investors, regional capacity additions can reduce lead times and logistics risk, but they also intensify local competition and may pressure margins in oversupplied segments.
Product Innovation as a Competitive Moat
Recent product launches illustrate how innovation is being used to defend and extend market position. One major Japanese manufacturer introduced a new flame-retardant PPS fiber grade specifically designed for high-voltage electrical insulation, targeting an application space where reliability and safety certification create strong barriers to entry. Meanwhile, a European supplier announced an eco-friendly PPS fiber line using bio-based feedstocks, aligning product development with sustainability goals in markets where procurement teams face increasing pressure to document lifecycle impacts. In a related high-performance direction, a partnership between a global chemical company and an aerospace OEM has focused on co-developing ultra-high-performance nanocomposite PPS fibers, suggesting that the upper end of the market is moving toward tailored, application-engineered materials rather than standardized grades.
PPS Resin Market
Market Structure Evolution: Consolidation, Differentiation, and New Entrants
The competitive trajectory appears to be moving toward a hybrid structure. On one side, consolidation and capacity acquisitions are strengthening the scale and regional reach of incumbents. On the other, product differentiation and application specialization are enabling companies to compete without relying solely on volume. New and expanding entrants, particularly in China, are increasing production capacity for filtration and industrial uses, which broadens available supply but also raises the importance of quality consistency and technical support. Over the next few years, the market is likely to reward players that can combine reliable scale with clear application advantages, while those competing primarily on price in commoditized segments may face intensifying pressure.
Forward Outlook: Three Trends Shaping the Next Three to Five Years
The next phase of growth will be shaped by the interaction of technical differentiation, cost resilience, and regulatory uncertainty. Three trends stand out as particularly consequential for commercial strategy.
PW Consulting
Trend 1: Application-Specific Value Pools Will Outperform Generic Segments
As buyers increasingly prioritize total cost of ownership and performance reliability, specification-driven applications are expected to capture a disproportionate share of margin growth. High-voltage insulation, advanced filtration media, and engineered industrial textiles are likely to see stronger demand for premium grades that solve clear operational problems. This trend favors producers with strong application engineering capabilities and consistent grade control, and it creates opportunities for companies that can demonstrate measurable performance advantages in targeted use cases. The broader implication is that growth will be less about expanding volume across all segments and more about winning in high-value niches where customers are willing to pay for proven performance.
Trend 2: Cost and Energy Dynamics Will Drive Regional Strategy Decisions
Given the electricity intensity of PPS production and ongoing raw material price volatility, regional cost structures will increasingly influence where capacity is added, how production is scheduled, and which suppliers are preferred in tender processes. Producers in regions with stable, cost-competitive energy and efficient logistics may gain a structural advantage, while high-energy-cost regions could see margin pressure unless offset by premium product positioning or local demand strength. For downstream buyers, this trend underscores the importance of multi-region sourcing strategies and scenario planning for energy and input cost fluctuations. It also suggests that near-market capacity expansions could become a differentiator for suppliers seeking to reduce lead times and improve supply assurance.
Trend 3: Sustainability and Regulatory Compliance Will Become Commercial Inputs
Sustainability is transitioning from a reputational consideration to a procurement requirement in several end markets. Bio-based feedstock development and other eco-aligned product initiatives are likely to gain traction among buyers who need to document environmental performance across their supply chains. At the same time, trade and regulatory reviews will continue to shape cross-border sourcing, potentially altering duty exposure and supply routes. The commercial implication is clear: sustainability claims and regulatory readiness will increasingly influence supplier selection, especially in sectors where compliance, safety, and lifecycle documentation carry operational weight. Companies that can provide credible, verifiable product attributes and maintain agile sourcing options will be better positioned to retain and expand share.
Risks and Uncertainties to Monitor
Despite the constructive growth outlook, several risks warrant attention. Continued raw material price volatility, especially for key precursors, could compress margins if not managed through pricing strategy or supply contracts. Energy cost escalation in certain regions may affect production economics and plant utilization decisions. Trade policy reviews and potential duty adjustments could introduce short-term sourcing disruption and pricing uncertainty. Finally, the risk of overcapacity in specific regional segments could intensify price competition, particularly in more commoditized filtration applications. Navigating these risks will require a combination of technical differentiation, flexible sourcing, and disciplined capacity planning.
Strategic Implications for Decision-Makers
For manufacturers, the priority is to align product development with the applications that command the strongest performance requirements and willingness to pay. Investing in grade consistency, application-specific fiber architectures, and credible sustainability attributes can create meaningful differentiation. At the same time, capacity and energy strategy should be evaluated in the context of regional cost structures and customer proximity, rather than scale alone. Companies that can combine reliable supply with clear technical advantage will be best placed to defend pricing and expand into higher-value segments.
For investors, the market offers a profile of steady growth with pockets of higher-margin opportunity in specialized applications. Due diligence should focus on the durability of product differentiation, the exposure of production costs to energy and raw materials, and the ability of target companies to navigate trade and regulatory shifts. Regional capacity moves and acquisitions may improve supply chain resilience, but they also require scrutiny around utilization, local competition, and end-market demand quality. Selective exposure to engineered fiber segments and application-led growth appears more attractive than undifferentiated volume plays.
For procurement and supply chain leaders, the strategic task is to reduce exposure to single-source dependency and price-only purchasing logic. Evaluating suppliers on the basis of grade consistency, technical support, energy and regulatory resilience, and sustainability documentation can lower total risk and improve long-term cost stability. Building multi-region sourcing options and maintaining visibility into trade policy developments will help mitigate disruption if duty environments or input costs shift. In practice, procurement strategies that treat PPS fibers as a performance-critical input rather than a commodity are more likely to secure reliable supply and better commercial outcomes.
The market is entering a period where technical value, cost resilience, and regulatory readiness will separate durable participants from price-takers. For decision-makers seeking a deeper, segment-level view of demand dynamics, competitive positioning, and scenario-based planning parameters, a more detailed research compendium can provide the granularity needed to translate these strategic trends into specific operational choices.
For detailed analysis of this topic, please visit the official page: Polyphenylene Sulfide Fibers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


