



Fibrinogen Concentrates Market: Why a 5.96% CAGR Reshapes the $704.96M Outlook by 2032

Strategic Trends and Commercial Opportunities in the Fibrinogen Concentrates Market
The global fibrinogen concentrates market has evolved from a specialized niche into a strategically significant segment within the broader plasma-derived therapeutics landscape. Market valuation reached approximately USD 468.38 million in 2025, reflecting a compound annual growth rate of 5.96 percent over the historical evaluation period and positioning the sector for continued expansion through 2032, when projected revenues approach USD 705 million. This trajectory is not merely a function of demographic demand or clinical adoption; it reflects structural shifts in surgical standards, regulatory pathways, manufacturing efficiency, and the economics of hemostatic care. For executives navigating biologics markets, fibrinogen concentrates present a case study in how concentrated therapeutic classes can scale while navigating plasma supply constraints, reimbursement complexity, and competitive differentiation.
PW Consulting
At the same time, the market is not without friction. Growth trajectories must be weighed against manufacturing bottlenecks, cost barriers for end users, and the evolving reimbursement environment that determines real-world utilization. Understanding where value is being created, which strategic moves are compounding advantage, and where uncertainty remains is essential for companies allocating capital, shaping product roadmaps, or evaluating partnership and acquisition targets in hemostasis and plasma-derived therapies.
Market Dynamics and Core Challenges
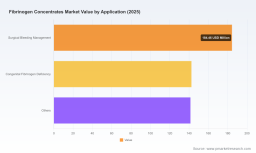
The current market structure reflects a mature but still expanding therapeutic category. Demand is distributed across surgical bleeding management, congenital fibrinogen deficiency, and a broad set of acquired and specialized applications. The product mix continues to favor powdered formulations, while liquid presentations are gaining incremental traction as reconstitution and storage considerations are addressed through formulation innovation. Geographically, developed markets continue to anchor the largest revenue shares, but the growth profile increasingly depends on expanded access in regions where hemophilia and bleeding disorder infrastructure is maturing.
Human Fibrinogen Market
Several forces are converging to define the near-term inflection points for the industry:
- Plasma supply and fractionation economics remain the dominant cost constraint. Fibrinogen-rich plasma inputs account for more than half of total production costs, which means that supply chain resilience, yield optimization, and donor plasma economics directly influence pricing power and margin stability.
- Reimbursement and coding frameworks are evolving rapidly in key markets. Recent HCPCS designations and expanding clinical approvals are reshaping the administrative and financial pathways that hospitals and payers use to authorize fibrinogen concentrate use, influencing both volume and substitution patterns.
- Clinical adoption is expanding beyond congenital indications into acquired fibrinogen deficiency and acute bleeding settings, but evidence requirements, institutional protocols, and cost consciousness create uneven adoption curves across health systems.
These dynamics create a market that rewards operators who can align product formulation, regulatory strategy, and market access planning rather than treating each as a separate silo. The ability to navigate plasma cost volatility while securing reimbursement clarity is becoming a competitive differentiator rather than a baseline expectation.
Key Drivers Shaping the Market
Technological Innovation and Formulary Differentiation
Innovation in fibrinogen concentrates is increasingly centered on presentation formats, viral inactivation robustness, reconstitution convenience, and indication expansion. Manufacturers are advancing refined purification and pathogen reduction processes that support confidence in efficacy and safety, while new packaging options are designed to meet the operational needs of surgical theaters and emergency settings. The introduction of specialized gram-level presentations reflects a broader trend toward tailoring product formats to clinical workflows and dosing requirements. These advances are not cosmetic; they affect procurement decisions, storage logistics, dosing precision, and the speed with which fibrinogen can be deployed in time-sensitive bleeding scenarios.
From a commercial standpoint, formulation and presentation strategy has become a lever for market access. Products that reduce handling complexity, improve dosing flexibility, or support specific patient populations can gain preference even in a category where therapeutic class equivalence is often assumed. The practical implication is that innovation must be paired with evidence generation and reimbursement alignment to translate clinical value into market share.
Regulatory and Reimbursement Dynamics
Regulatory progress continues to expand the addressable patient population. Recent approvals in the United States have broadened the use of fibrinogen concentrates for acquired fibrinogen deficiency and acute bleeding episodes, while separate regulatory actions have reinforced product-specific coding pathways. These developments matter because they influence prescribing confidence, hospital procurement policies, and payer coverage decisions. A product that moves from a narrower congenital indication into acquired and acute bleeding settings can unlock substantially larger utilization, provided the supporting evidence and coding environment enable consistent reimbursement.
The same regulatory environment introduces complexity. Stringent plasma collection, testing, and fractionation requirements raise the barrier to entry and increase the operational burden for manufacturers. Simultaneously, payers and health systems are scrutinizing cost-effectiveness, dosing efficiency, and the relationship between fibrinogen concentrate use and broader hemostatic management protocols. Companies that proactively shape clinical evidence, real-world utilization data, and coding narratives are better positioned to mitigate reimbursement friction and sustain volume growth.
Demand-Side Transformation in Surgical and Bleeding Care
Demand for fibrinogen concentrates is being shaped by several interrelated clinical and institutional trends. Surgical bleeding management remains a central application, supported by growing recognition of fibrinogen’s role in perioperative hemostasis and the desire to reduce transfusion-related risks and complications. At the same time, congenital fibrinogen deficiency continues to anchor a consistent base of demand, while acquired fibrinogen deficiency is emerging as an area of expanding clinical interest across trauma, cardiac, obstetric, and critical care settings.
Hospital procurement behavior is also shifting. Procurement teams are increasingly balancing clinical efficacy, supply reliability, presentation convenience, and total cost of care. In many institutions, formulary decisions are not made solely on price per gram; they incorporate workflow fit, stability, reconstitution requirements, and the availability of dosing options that match patient weight and bleeding severity. This suggests that demand growth will not be uniform across products or settings. Instead, adoption will favor manufacturers who can demonstrate clinical reliability, practical usability, and a clear value proposition relative to alternatives in the hemostatic toolkit.
Supply Chain and Cost Structure Pressures
Cost structure remains a defining feature of the market. The economics of plasma fractionation mean that plasma acquisition and processing represent the largest share of manufacturing cost, with fibrinogen-rich materials contributing a substantial portion of total expense. This creates sensitivity to plasma supply variability, donor availability, fractionation yields, and overhead associated with compliance and testing. For manufacturers, the challenge is not simply reducing unit cost; it is managing a cost stack that is partially exposed to external supply dynamics while maintaining consistent product availability and quality.
The cost implication for end users is equally important. At typical dosing levels, fibrinogen concentrate therapy can represent a meaningful expense for hospitals, particularly in lower-income regions or resource-constrained settings. That pricing pressure does not eliminate demand, but it shapes substitution decisions, protocol design, and the pace at which fibrinogen concentrate use expands beyond well-resourced centers. Commercial strategies that account for tiered access, presentation efficiency, and strong pharmacoeconomic justification are more likely to sustain growth across diverse market conditions.
Competitive Landscape and Leading Strategies
The market is characterized by a concentrated group of established plasma-derived biologics manufacturers alongside regional players seeking to establish or expand fibrinogen concentrate offerings. Leading organizations differentiate themselves through combinations of indication breadth, presentation options, regulatory milestones, manufacturing scale, and market access positioning. Rather than competing on a single dimension, successful players are aligning product portfolios with clinical workflows and reimbursement realities.
Several strategic positions are evident in the current landscape:
- Indication expansion as a growth lever. Companies that secure approvals for acquired fibrinogen deficiency or acute bleeding episodes broaden the clinical contexts in which their products can be used, increasing the addressable volume beyond congenital deficiency alone.
- Presentation flexibility as an operational advantage. Introducing dosing options and formulations tailored to specific settings can reduce friction in procurement, compounding, and bedside administration, strengthening hospital preference and formulary retention.
- Regulatory and coding alignment as a commercial enabler. Clear coding pathways and reimbursement language can reduce administrative barriers and accelerate institutional adoption, especially when paired with clinical evidence that supports appropriate use.
- Plasma-derived manufacturing credibility and supply resilience. Established fractionation capabilities and robust quality systems matter in a category where consistency, safety, and supply continuity are paramount for both clinicians and purchasers.
Recent developments illustrate how regulatory and product-level moves are reshaping competitive positioning. In late 2025, a major plasma therapeutics company secured FDA approval for a fibrinogen concentrate in acute bleeding episodes for pediatric and adult patients with congenital fibrinogen deficiency. Shortly thereafter, in early 2026, another key player gained FDA approval for a new 2-gram presentation of its fibrinogen concentrate for bleeding patients with acquired fibrinogen deficiency, building on earlier expanded approval activity in the prior year. These milestones are not isolated product events; they signal a broader shift toward wider clinical use, more flexible dosing formats, and increased competitive intensity around indication coverage and market access.
The market concentration profile suggests that scale and regulatory experience still matter, with a relatively concentrated share structure among leading participants. However, the landscape is also evolving through targeted launches, indication-specific differentiation, and regional capacity development. New entrants and regional manufacturers can compete by focusing on specific geographies, cost-efficient presentations, or locally relevant indications, particularly where access gaps remain or where procurement dynamics favor regional supply resilience. Consolidation may continue over time as larger players seek to strengthen portfolio depth and manufacturing reach, but differentiation through formulation, indication strategy, and market access capability will remain central to winning share.
Future Trends and Commercial Implications
Broader Clinical Use Will Drive Volume, but Distribution Will Be Uneven
Over the next three to five years, the most consequential trend is likely to be the continued migration of fibrinogen concentrate use beyond narrowly defined congenital indications into acquired deficiency and acute bleeding management. This broadening reflects both regulatory momentum and clinical interest in targeted fibrinogen replacement. The commercial implication is that total volume potential increases, but adoption will depend on local protocols, evidence dissemination, and reimbursement clarity. Markets with mature bleeding disorder infrastructure and established surgical hemostasis pathways are likely to absorb new indications faster, while regions where plasma-derived therapy access remains constrained will see more gradual uptake. Companies that invest in clinical education, guideline engagement, and site-level implementation support can convert indication expansion into sustained utilization more effectively than those relying on label expansion alone.
Presentation Innovation and Workflow Fit Will Influence Preference
As the category matures, product format will increasingly serve as a differentiator. Liquid formulations, specialized gram presentations, and packaging designed for rapid deployment in surgical and emergency settings can reduce logistical friction and improve fit within institutional workflows. This does not eliminate the importance of clinical efficacy and safety, but it adds a practical layer to procurement and formulary decisions. The trend favors manufacturers that treat product design as part of the value proposition, aligning presentation choices with real-world usage patterns. For hospitals and health systems, the opportunity lies in standardizing fibrinogen concentrate use in a way that supports both clinical outcomes and operational efficiency.
Cost, Access, and Reimbursement Will Remain Strategic Variables
Cost pressures are unlikely to disappear. Plasma-dependent manufacturing economics will continue to expose the category to input cost volatility, while high per-dose treatment costs will keep affordability and pharmacoeconomic justification in focus for payers and hospital administrators. The trend here is not a simple price war; it is a more sophisticated market access environment in which coding, coverage, evidence, and total cost of care arguments influence adoption. For manufacturers, the strategic response should include robust health economics support, dosing efficiency narratives, and proactive engagement with reimbursement frameworks. For investors, the durability of margins will depend on yield management, supply resilience, and the ability to secure favorable access arrangements rather than on volume growth alone.
Hemodialysis Concentrates Market
Potential Risks and Uncertainties
Several uncertainties could alter the pace or shape of growth. Plasma supply disruptions, donor availability constraints, or fractionation bottlenecks can affect availability and cost. Reimbursement changes, stricter utilization management, or shifts in payer policy could slow expansion in specific settings. Competitive intensity may increase as new presentations, regional entrants, or alternative hemostatic therapies influence treatment choices. In addition, clinical evidence expectations may evolve, requiring more robust real-world data to support use outside traditional indications. These risks do not negate the growth outlook, but they highlight the need for contingency planning around supply, access, and evidence strategy.
Actionable Guidance for Decision Makers
The fibrinogen concentrates market rewards strategic discipline across product, regulatory, and access dimensions. For executives and investors, four priorities stand out.
- For manufacturers, align formulation innovation with indication strategy and reimbursement planning. Product launches should be built around clinical workflow fit, dosing flexibility, and a credible market access narrative, not solely around regulatory milestones.
- For investors, focus on supply resilience, fractionation efficiency, and access-enabled growth. Companies that can manage plasma cost exposure, maintain consistent availability, and convert indication expansion into reimbursed utilization are better positioned for durable value creation.
- For procurement and clinical leaders, evaluate fibrinogen concentrate options based on total workflow impact and total cost of care, including presentation efficiency, dosing suitability, and evidence supporting appropriate use in relevant patient populations.
- For all stakeholders, treat market access and evidence development as ongoing capabilities. Reimbursement pathways, coding frameworks, and clinical adoption patterns are shifting quickly, and timely intelligence can reduce execution risk and improve planning accuracy.
Given the pace of regulatory updates, presentation innovation, and reimbursement evolution, decisions made on incomplete market intelligence carry avoidable risk. For organizations that need deeper segmentation, pricing and reimbursement detail, competitive benchmarks, and scenario planning across regions and indications, more granular analysis can help translate these trends into actionable plans. Detailed data sets, company-specific evaluations, and tailored commercial scenarios are available through PW Consulting’s full Fibrinogen Concentrates Market report, which provides the structured intelligence needed to support product strategy, investment decisions, and procurement planning with greater precision.
For detailed analysis of this topic, please visit the official page: Fibrinogen Concentrates Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


