



Insect Feed Market: How 16.4% CAGR and Aquaculture Demand Reshape 2032 Outlook

The Insect Feed Market: Strategic Trends and Commercial Opportunities Through 2032
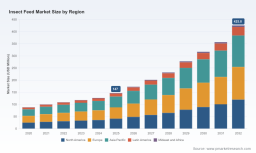
The insect feed sector is transitioning from niche sustainability play to mainstream protein infrastructure. With the global market valued at approximately $147 million in 2025 and projected to reach $425.8 million by 2032, the sector is expanding at a compound annual growth rate of 16.4 percent. This trajectory reflects more than incremental demand growth. It signals a structural recalibration of animal nutrition supply chains, driven by regulatory opening, substrate economics, and the scaling of bioconversion technology. For executives and investors, the question has shifted from whether insect protein will gain traction to how capital, capability, and partnerships will be allocated as the market matures.
Market Landscape and Core Challenges
The revenue arc over the past half-decade illustrates steady acceleration, with growth compounding as production capacity converts from pilot scale to commercial throughput. By the close of the forecast window, the market is on a path toward nearly triple its 2025 baseline. That expansion is uneven rather than uniform, shaped by regional regulatory readiness, feed formulation economics, and the pace at which manufacturing networks achieve cost parity with conventional protein sources. Understanding where the market is heading requires looking past headline figures to the structural constraints that will determine which players capture value.
Navigating Structural Constraints
Several inflection points are shaping the operational reality of the industry. First, substrate sourcing and waste-stream consistency remain foundational bottlenecks. Insect feed production depends on upcycled organic inputs such as food processing byproducts, and the economics of collection, pretreatment, and contamination control vary widely by geography and season. While this model can reduce material costs substantially relative to conventional protein sourcing, the operational discipline required to maintain consistent substrate quality across multiple intake streams is non-trivial. Facilities that fail to standardize input quality encounter downstream variability in yield, nutrient profiles, and regulatory compliance.
Second, regulatory adoption is advancing but remains fragmented. In the European Union, rules governing insect protein in aquaculture are established, and approval pathways for poultry and swine applications have progressed under updated feed frameworks. In the United States, regulatory clearances have extended for select insect proteins in poultry and pet food categories. The pace and scope of these approvals differ by jurisdiction and protein type, creating uneven commercialization timelines. Companies that can navigate multiple regulatory regimes simultaneously, or that align product development with the fastest-opening categories, gain a meaningful time advantage.
Aqua Feed Market
Third, scaling biology is as much an engineering challenge as a biological one. Temperature control, humidity management, disease mitigation, and harvesting logistics all influence yield stability and unit economics. Early-stage producers often underestimate the capex intensity of climate-controlled environments and the operational complexity of continuous rearing systems. As the market moves toward larger facilities, the gap between companies with proven process control and those still refining biological workflows will become more visible in margin performance and supply reliability.
Key Drivers Reshaping the Sector
Several forces are converging to accelerate adoption and reshape competitive dynamics. These drivers are not isolated; they reinforce each other and create a clearer line of sight to commercial scale for operators who align technology, compliance, and customer demand.
Bioconversion and Process Technology
The most consequential technical progress lies in improving rearing efficiency, feedstock flexibility, and downstream processing consistency. Proprietary rearing systems, automation in harvesting and separation, and process controls that stabilize larval growth cycles are reducing variability in protein and lipid outputs. This matters because feed formulators require repeatable nutrient profiles, contamination thresholds, and functional properties. Companies that treat insect production as a manufacturing process rather than an agricultural experiment are gaining credibility with B2B buyers who evaluate suppliers on reliability as much as sustainability credentials.
The commercial significance of this shift is clear when viewed alongside recent market activity. Innovafeed has expanded its operational footprint with a U.S. facility in Decatur, Illinois, marking a step toward localized production in a market where feedstock availability and regulatory timing support scale-up. This move illustrates how technology-enabled producers are positioning themselves closer to end markets in order to reduce logistics friction and respond more quickly to regional demand signals.
Regulatory Opening and Category Expansion
Regulation remains the central gatekeeper for category expansion. Approvals for aquaculture have already enabled commercial use of insect proteins in fish feed, while newer regulatory movements in the EU and U.S. have extended possibilities into poultry and swine nutrition and, in certain contexts, pet food. These changes do not merely open new addressable segments; they reshape feed formulation economics by creating alternatives to soy and fishmeal in categories where substitution pressure is strongest.
The regulatory trajectory also influences procurement behavior. Feed manufacturers and integrators that have been waiting for regulatory clarity are now beginning to test inclusion rates, evaluate supply continuity, and negotiate multi-year arrangements. Protix, for example, signed a multi-year supply agreement with Skretting for black soldier fly meal in salmon feed formulations, a move that signals how regulatory maturity is translating into committed offtake and category-specific product development.
Demand-Side Shifts in Animal Nutrition and Pet Care
Demand is being pulled by multiple end-use pressures. In aquaculture, the need for sustainable protein inputs continues to intensify as marine ingredient supply faces volatility and environmental scrutiny. In poultry and swine nutrition, producers are exploring insect protein not only for sustainability positioning but also for functional benefits and supply diversification. In pet food, consumer interest in novel protein sources and premium formulation is expanding the addressable market for insect-based ingredients, particularly where regulatory clearance and brand acceptance progress together.
This diversification matters strategically because it reduces dependence on any single category’s adoption cycle. Companies with portfolios that span aquaculture, livestock nutrition, and pet food can shift commercialization emphasis as regulatory timing and customer readiness vary by region. The effect is a more resilient demand base and a stronger foundation for long-term contract structures.
Cost Structure and Substrate Economics
The economic case for insect feed is closely tied to substrate cost and plant efficiency. Because insect production can utilize upcycled organic waste streams, input costs can be materially lower than those of conventional protein sources when collection and pretreatment are managed effectively. Life cycle assessments comparing insect-based inputs with soy or fishmeal indicate substantial differences in land and water requirements and lower associated greenhouse gas emissions, reinforcing the sustainability narrative that supports procurement decisions.
However, cost advantage is not automatic. It depends on logistics networks, preprocessing capability, and the ability to maintain consistent substrate composition at scale. Facilities that integrate substrate procurement, pretreatment, and rearing into a coordinated operational model are better positioned to protect margins as volumes increase. This is where competitive differentiation increasingly emerges: not simply in the insect species used, but in the industrial design of the entire value chain.
Competitive Landscape and Leading Strategies
The market remains moderately concentrated, with a small group of established producers accounting for a meaningful share of revenue and an expanding set of regional and specialized entrants competing on niche formulations, geography, or substrate strategies. The strategic posture of leading companies reveals how value is being captured in a market still defining its standards.
Differentiation Through Scale, Technology, and Of ftake
Several patterns distinguish the more advanced players. Protix has built a profile around high-quality insect solutions spanning feed, pet food, aquaculture, and plant care, with a focus on black soldier fly larvae and broad application coverage. Its multi-year agreement with Skretting illustrates a strategy centered on committed customer relationships and category-specific formulation support, which helps stabilize demand and fund capacity expansion.
Innovafeed has emphasized proprietary rearing technology and geographic expansion, including its U.S. facility in Illinois. This reflects a strategy of combining technical differentiation with direct market access, reducing reliance on export logistics and positioning closer to large North American feed markets. Entobel has pursued a similar operational discipline, with long-standing production in Vietnam and a recent certification milestone that reinforces its positioning around sustainability and governance as commercial signals for B2B buyers.
Pet Food Insect Protein Market
Other companies are carving distinct lanes. Beta Hatch has focused on mealworm-based production within a regenerative agriculture framing, highlighting a different species and system design from the black soldier fly-dominant core of the market. Nutrition Technologies, now operating under the Sentara Group name following expansion, has continued to build around black soldier fly ingredients for aquaculture, agriculture, and animal feed, illustrating how rebranding and organizational scaling can accompany capacity growth. Hexafly and nextProtein have emphasized the bioconversion of food waste into protein, oil, and fertilizer, aligning product portfolios with circular-economy value propositions that appeal to customers seeking integrated sustainability outcomes.
Market Evolution: Consolidation, Specialization, and New Entry
The competitive landscape is evolving along several axes. Scale industrialization is concentrating production among companies able to fund large facilities, standardize processes, and secure stable substrate supply. At the same time, specialization remains viable in niches such as pet food formulations, functional ingredients, plant care products, and regional supply arrangements where logistics and regulatory timing favor local production.
New entry continues, but the bar is rising. Early entrants could often compete on concept and pilot output; newer entrants must demonstrate process reliability, regulatory compliance, cost control, and defensible customer relationships. This dynamic is likely to reward operators that combine biological capability with manufacturing discipline and commercial execution. It also suggests that partnerships, offtake agreements, and integration with existing feed supply chains will become more important than standalone brand positioning.
Forward Outlook: Three Strategic Trends for 2026–2032
Looking ahead, several trends are likely to define how value accrues in the insect feed market over the next several years.
Trend 1: Regional Production Clusters and Feedstock-Proximity Manufacturing
Production is likely to consolidate around feedstock availability, regulatory readiness, and end-market demand rather than forming a single global center of gravity. Regions with strong waste-stream infrastructure, supportive feed regulations, and large aquaculture or livestock sectors will attract capacity. This has direct commercial implications: companies that align facility siting with substrate economics and customer proximity will lower logistics costs and improve supply reliability, while those dependent on long-distance substrate or product movement may face margin pressure as the market scales.
Trend 2: Formulation Integration and Category-Specific Product Design
Insect ingredients will increasingly be valued not simply as generic protein but as formulated inputs tailored to specific species, life stages, and functional requirements. As feed manufacturers gain experience with inclusion rates and nutrient performance, demand will shift toward consistent specifications, traceability, and technical support. The commercial opportunity lies in building product architectures around customer formulations rather than selling undifferentiated bulk ingredients. Suppliers that invest in application engineering and quality assurance will be better positioned to defend pricing and deepen relationships.
Trend 3: Regulatory Normalization and Procurement Mainstreaming
As approvals expand and standards mature, insect protein is likely to move from special-case procurement to routine supplier evaluation. That transition will favor operators with established compliance records, auditable quality systems, and supply continuity. It also introduces risk: regulatory timing can shift, inclusion limits can change, and category approvals may not proceed uniformly. Companies that assume a linear regulatory path without scenario planning may misallocate capacity or overcommit to segments that open more slowly than expected.
Associated uncertainties include substrate consistency at scale, biological process control during rapid expansion, and the risk that sustainability narratives alone will not sustain procurement decisions if cost or performance gaps remain. The market’s trajectory is strong, but execution quality will determine which participants convert growth into durable margins.
Implications and Actions for Decision Makers
For executives and investors evaluating the insect feed market, the strategic task is to match ambition with operational readiness and to prioritize the decisions that convert market momentum into competitive advantage.
PW Consulting Health Care Research Center
For Producers and Technology Developers
- Prioritize process control and substrate logistics as the foundation of scale-up. Consistent quality and cost stability matter more to B2B buyers than incremental sustainability claims, so investment should flow toward rearing consistency, harvesting efficiency, and integrated feedstock management.
- Align capacity deployment with regional regulatory timing and customer demand. Expanding too quickly into segments with uncertain approval pathways can create underutilized assets, while sequencing expansion around opening categories supports revenue absorption and learning-curve gains.
- Build formulation support and application data. As customers move from trial to routine use, technical service capability becomes a differentiator. Developing species-specific and application-specific evidence strengthens customer retention and pricing power.
For Investors and Capital Allocators
- Evaluate biological capability alongside manufacturing discipline. The most attractive opportunities are likely to be with teams that can demonstrate repeatable yield, contamination control, and cost trajectory rather than concept-level promise.
- Assess demand visibility through offtake structure and customer diversification. Contracts, pilot-to-commercial conversion rates, and exposure across aquaculture, livestock, and pet food can indicate resilience if one category’s adoption slows.
- Model regulatory and substrate scenarios, not just base-case growth. Because approvals, inclusion limits, and feedstock availability can vary by region, sensitivity analysis around timing and input costs is essential for realistic return expectations.
For Procurement and Feed Formulators
- Treat insect ingredients as part of a supply diversification and sustainability strategy, but validate them through performance trials and supply reliability assessment. The strategic value lies in reducing exposure to conventional ingredient volatility while maintaining nutrient specification and consistency.
- Engage early with suppliers on specification design and traceability. Collaboration on inclusion rates, quality parameters, and auditability can accelerate integration and reduce reformulation risk.
- Structure sourcing with regulatory awareness. Procurement plans should account for category-specific approvals and potential changes in inclusion limits so that supply commitments align with regulatory reality in each market.
Closing Perspective
The insect feed market is entering a phase where growth is increasingly determined by execution rather than narrative. The revenue trajectory through 2032 points to a substantial expansion in addressable demand, but the distribution of value will depend on how effectively companies manage substrate economics, regulatory complexity, process control, and customer integration. For organizations building, funding, or sourcing from this sector, the opportunity is not simply to participate in a high-growth category but to shape a supply chain that can deliver consistent quality at competitive cost while meeting the sustainability expectations of modern animal nutrition. Detailed segmentation, regional dynamics, and company-level benchmarking can sharpen these decisions further, and a full research report can provide the supporting data and structured frameworks needed for planning at the segment and facility level.
For detailed analysis of this topic, please visit the official page: Insect Feed Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


