



Chemotherapy Induced Peripheral Neuropathy Treatment Market: 6.5% CAGR from 2026-2032

Chemotherapy-Induced Peripheral Neuropathy Treatment Market: Strategic Trends and Commercial Opportunities
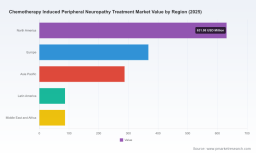
The chemotherapy-induced peripheral neuropathy (CIPN) treatment market has reached a critical inflection point. With a total market value of approximately $1.46 billion in 2025 and a projected trajectory to exceed $2.28 billion by 2032, the sector reflects a compound annual growth rate of 6.5 percent over the 2026-2032 period. This expansion is not merely a function of rising oncology volumes. It represents a structural shift in how the pharmaceutical industry approaches symptom management, neurological preservation, and quality-of-life endpoints in cancer care. Chemotherapy remains one of the most widely deployed modalities in oncology, and neuropathy stands among its most persistent and debilitating side effects. Patients receiving platinum-based agents, taxanes, and vinca alkaloids frequently experience progressive sensory loss, pain, balance impairment, and treatment-limiting dose reductions. The market for interventions addressing these outcomes has evolved from a fragmented landscape of off-label symptomatic therapies into a structured pipeline of mechanism-targeted candidates, increasingly shaped by regulatory guidance and clinical evidence standards.
Yet the scale of opportunity is matched by complexity. Stakeholders approaching this space must navigate a market where clinical differentiation, regulatory pathways, pricing dynamics, and oncology practice patterns intersect in non-linear ways. The next phase of growth will likely reward players who can translate mechanism plausibility into robust trial design, align with evolving oncology workflows, and articulate value propositions that resonate beyond symptom relief alone. Understanding where the market stands today, what forces are reshaping it, how competitors are positioning themselves, and where strategic opportunities are likely to emerge provides a necessary foundation for informed decision-making.
Market Landscape and Core Challenges
The CIPN treatment space is characterized by moderate market concentration and a therapeutic mix that still leans heavily on existing symptomatic classes, particularly antidepressants and anticonvulsants, alongside a smaller but strategically important segment of narcotics and emerging alternatives. This composition reflects both historical prescribing habits and the limited number of approved, mechanism-specific interventions. While the broader market size demonstrates steady expansion, the underlying structure reveals a sector that is simultaneously mature in its standard-of-care elements and early-stage in its innovation pipeline. That duality creates both stability and uncertainty, as legacy therapies continue to anchor clinical practice while newer candidates attempt to redefine therapeutic expectations.
A first challenge lies in clinical endpoint definition and trial design. CIPN presents across a spectrum of sensory, motor, and autonomic symptoms, and the field has historically struggled to standardize how improvement, stabilization, or prevention should be measured. Different chemotherapy regimens, cumulative dosing patterns, and patient baseline risk profiles complicate the creation of uniform trial populations. Sponsors that rely on broad symptom scales without mechanistic alignment or clearly defined responder thresholds risk generating data that is difficult to position clinically or commercially. The challenge is not simply demonstrating statistical change. It is demonstrating clinically meaningful change that oncologists, neurologists, and payers can act upon.
A second challenge is the persistent alignment gap between existing symptomatic classes and the underlying neurobiology of nerve injury. Current treatments often address perceived symptom pathways without directly interrupting axonal degeneration, ion channel dysfunction, or inflammatory signaling associated with specific chemotherapeutic agents. As understanding of CIPN mechanisms matures, therapies that are not linked to a plausible biological rationale may face growing pressure in clinical discussion and formulary positioning. This does not render all symptomatic options obsolete, but it does raise the bar for differentiation. The market increasingly favors interventions that can articulate not only what they treat, but why they should work in a particular chemotherapy context.
PW Consulting Health Care Research Center
A third challenge involves the oncology treatment environment itself. Dose adjustments, regimen substitutions, and individualized risk-benefit calculations can influence both the incidence of neuropathy and the perceived value of adjunctive interventions. In practice, neuropathy management does not exist in isolation. It competes for attention alongside tumor response, survival endpoints, and other supportive care priorities. Treatments that can integrate into existing oncology workflows, offer predictable safety profiles, and demonstrate a credible link to preserving chemotherapy delivery are more likely to gain adoption than those positioned as standalone neurological interventions with limited integration into cancer care pathways.
Key Drivers Shaping the Market
Several interconnected factors are accelerating momentum in the CIPN treatment market, and their influence is likely to intensify over the next several years. Rather than acting independently, these forces are reinforcing one another, reshaping both pipeline priorities and commercial expectations.
One of the most consequential drivers is the shift toward mechanistic and targeted approaches. A growing portion of the pipeline is focused on molecular pathways with clearer links to nerve injury, signaling dysregulation, or peripheral nerve repair. Candidates addressing specific ion channels, receptor-mediated protective pathways, and topical delivery strategies reflect an effort to move beyond nonspecific symptom modulation. This trend matters commercially because it creates opportunities for sharper messaging, more defensible clinical narratives, and potential differentiation in a crowded supportive care environment. At the same time, it raises the technical requirement for biomarker strategy, subgroup definition, and endpoint clarity. Sponsors that can connect a mechanism to a meaningful clinical readout are better positioned to justify investment and partnership interest.
Regulatory guidance and pathway signals are a second major driver. The issuance of FDA draft guidance for developing drug and biological products for the prevention and treatment of CIPN has helped establish a more explicit framework for expectations around trial design, population definition, and outcome measurement. Complementary regulatory actions, including Fast Track designations and IND clearances for candidates targeting CIPN, indicate that the agency is engaging with the area more actively. This environment reduces some ambiguity for developers and can improve the perceived credibility of programs that are designed with regulatory expectations in mind. For commercial stakeholders, the implication is that programs aligned early with guidance are more likely to navigate development with fewer late-stage surprises and clearer dialogue with regulators.
A third driver is the changing demand profile within oncology. As cancer therapies improve and patients live longer, the burden of chronic treatment-related effects is becoming more visible. Neuropathy that persists beyond active chemotherapy or limits future treatment options carries significant downstream implications for physical function, independence, and quality of life. This has increased attention to interventions that can prevent symptomatic progression, reduce dose-limiting toxicity, or support patients through longer treatment courses. Demand is not only coming from patient advocacy and clinician concern. It is also being shaped by the broader oncology goal of preserving treatment continuity and minimizing long-term functional impairment.
Supply-side and reimbursement dynamics also play a role, though often in less visible ways. The relative availability of generic symptomatic therapies exerts competitive pressure on pricing and adoption for newer agents, while reimbursement expectations increasingly favor evidence that connects treatment to functional outcomes, reduced downstream costs, or maintained chemotherapy delivery. Cost structures are therefore influenced by both the competitive shadow of established options and the evidentiary requirements of payers and health systems. Programs that can demonstrate practical value in real-world oncology settings are more likely to achieve sustainable market positioning than those relying solely on clinical signals without integration into care economics.
Competitive Landscape and Leading Strategies
The competitive environment reflects a spectrum of developmental maturity and strategic focus. Some companies are advancing candidates with clearer regulatory momentum or later-stage clinical activity, while others are operating in earlier phases or have paused further development after earlier signals. What distinguishes the more strategically positioned players is not only the stage of their programs, but the coherence of their therapeutic rationale, the alignment of their trial design with oncology context, and their ability to use regulatory or partnership leverage to accelerate confidence in their approach.
Dogwood Therapeutics illustrates a company building momentum through a combination of clinical progress and strategic licensing activity. The Halneuron program has moved forward in Phase 2b with reported interim findings and substantial enrollment progress, while the SP16 program has advanced through licensing from Serpin Pharma with IND clearance and planned Phase 1b activity. This dual-track structure suggests an emphasis on diversifying mechanism exposure while maintaining forward progress in a lead candidate. From a strategic standpoint, the company appears to be positioning around both clinical data generation and partnership-enabled capability expansion, which can be valuable in a market where single-asset dependence carries execution risk.
Asahi Kasei Pharma’s ART-123 program takes a prevention-oriented approach in a defined oncology population, focusing on sensory symptom prevention in colorectal cancer patients receiving oxaliplatin. This positioning is strategically notable because prevention can be harder to demonstrate than treatment, but it may also offer stronger clinical integration if the evidence supports a clear reduction in neuropathy burden within a specific chemotherapy context. Targeting a well-defined regimen and patient group can reduce some of the heterogeneity challenges that complicate broader CIPN studies, though it also narrows the initial commercial footprint.
Neuropathy Pain Treatment Market
Sironax’s SIR2501 program has drawn attention through Fast Track designation, signaling regulatory recognition of potential unmet need and development efficiency value. In a market where endpoint complexity can slow progress, regulatory designations can provide useful leverage for development planning, clinical engagement, and partnership conversations. WinSanTor’s topical pirenzepine program, meanwhile, reflects an alternative delivery strategy and a broader peripheral neuropathy focus, with ongoing work extending beyond CIPN. Topical approaches may be attractive if they can reduce systemic exposure or offer localized benefit, but adoption will depend on evidence that supports clinical differentiation and practical usability.
Serpin Pharma’s SP16 program reinforces the growing importance of early-stage financing and academic or institutional support in shaping pipeline viability. The receipt of grant funding to support a Phase 1b trial highlights how non-dilutive resources can help earlier programs reach critical developmental checkpoints. For investors and partners, this is a reminder that the CIPN market includes meaningful activity not only from large-scale commercial developers, but also from smaller, mechanism-focused groups whose evolution may influence future licensing and acquisition dynamics.
Across these players, a few competitive themes emerge. First, there is a clear trend toward programs that are more tightly tied to specific mechanisms or delivery modalities, with the intent of differentiating from nonspecific symptom management. Second, regulatory engagement and guidance alignment are increasingly part of strategic positioning, particularly for companies looking to reduce development risk or improve the credibility of their programs in clinical and investor discussions. Third, the landscape remains open enough for new entrants to find niches, but crowded enough that differentiation must be supported by more than mechanistic plausibility. Credible clinical design, context-specific positioning, and practical integration into oncology care will likely determine which programs translate into durable commercial advantage rather than short-term pipeline interest.
Forward-Looking Trends and Commercial Implications
Over the next three to five years, several trends are likely to shape the direction of the CIPN treatment market. These are not mutually exclusive, and each carries distinct commercial implications.
One likely trend is a sharper separation between prevention-focused and treatment-focused interventions. As clinical programs mature, stakeholders may increasingly differentiate between agents intended to reduce the onset or progression of neuropathy during chemotherapy and those intended to manage established symptoms. This distinction matters for trial design, regulatory positioning, and clinical adoption. Prevention programs may target specific regimens or high-risk populations, while treatment programs may need to demonstrate meaningful benefit in patients with existing neurological impairment. The commercial implication is that value propositions will need to be tailored more precisely to the clinical context in which the intervention is used. Broad, undifferentiated claims may be less effective than narrowly supported, use-case-specific positioning.
A second trend is the increasing importance of topical and targeted delivery approaches alongside systemic therapies. Topical strategies may gain attention if they can offer focused benefit with favorable tolerability or reduced systemic exposure, especially in a population where polypharmacy and cumulative toxicity are concerns. However, clinical adoption will depend on whether these approaches can demonstrate consistent efficacy, ease of use, and integration into oncology supportive care routines. The commercial opportunity is not just in developing a new formulation. It is in proving that the delivery method creates meaningful clinical or operational advantages that clinicians and patients will accept in practice.
A third trend is growing pressure to connect CIPN interventions with functional and care-continuity outcomes. As payer and health system expectations evolve, evidence that goes beyond symptom scores may become more important. Demonstrating associations with maintained chemotherapy dosing, reduced supportive care utilization, or improved day-to-day function could strengthen commercial viability for certain programs. The risk is that companies relying solely on conventional symptom endpoints without a clear link to broader outcomes may find adoption more difficult or reimbursement discussions more complex. This creates a strategic imperative to design evidence generation around the full clinical and economic context of use.
At the same time, uncertainty remains. Trial results may vary by chemotherapy class, baseline risk, and endpoint definition, and not every mechanistic hypothesis will translate into durable clinical benefit. Competitive dynamics may also shift through partnerships, licensing, or consolidation, particularly as earlier-stage programs reach pivotal milestones. Stakeholders should therefore plan for a market that is growing but fragmented in credibility, where selection of partners, programs, or investment targets requires careful assessment of trial design, intended use case, and alignment with oncology practice.
Strategic Recommendations for Decision-Makers
For manufacturers and developers, the priority is to design programs with clear clinical context and regulatory alignment from the outset. This includes defining the intended chemotherapy setting, the relevant patient population, and the endpoint strategy in a way that supports both clinical credibility and commercialization. Mechanism-based differentiation is valuable, but it must be paired with evidence that can withstand scrutiny in real-world oncology settings. Developers should also consider how they will position their intervention relative to existing symptomatic options and whether they can articulate a distinct value proposition around tolerability, delivery, or care integration.
For investors, the opportunity lies in distinguishing programs with defensible execution roadmaps from those that depend primarily on early enthusiasm. Attention should be paid to enrollment feasibility, endpoint clarity, regulatory engagement, and the strength of clinical rationale within a specific chemotherapy context. Programs that combine mechanism interest with sound trial design and credible milestones may offer stronger risk-adjusted prospects than those that emphasize scientific promise without a clear path to clinically actionable evidence. Early-stage licensing and partnership activity may also create optionality, particularly if it enables better-capitalized or more operationally experienced groups to accelerate development.
For procurement and formulary decision-makers, the focus should be on evidence that supports practical adoption and value relative to current care patterns. This means evaluating not only efficacy signals but also safety, ease of integration, and any demonstrated impact on treatment continuity or functional outcomes. As new agents emerge, structured assessment frameworks can help determine which interventions warrant adoption, under what conditions, and where further evidence is needed before broader use. The availability of more standardized guidance and maturing clinical data should support more disciplined evaluation over time.
Worldwide Advanced Cancer Pain Management Market
In a market expanding toward $2.28 billion by 2032, the strategic question is not whether demand for effective CIPN intervention will continue to grow, but which programs, partnerships, and evidence strategies will separate durable value creation from transient pipeline interest. Detailed segmentation data, pipeline benchmarking, and scenario analysis can help organizations move from general market awareness to specific, actionable decisions. Readers interested in deeper breakdowns of market segments, competitive benchmarks, and customized strategic implications can explore the full report available through PW Consulting for more detailed segmentation data and tailored guidance.
For detailed analysis of this topic, please visit the official page: Chemotherapy Induced Peripheral Neuropathy Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


