



ESP Market 2026–2032: Why 6.4% CAGR and Power Generation Dominance Redefine Strategy

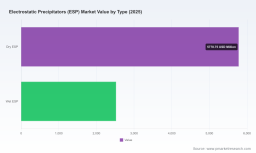
Navigating the Electrostatic Precipitators Market: Strategic Trends and Commercial Opportunities Through 2032
The electrostatic precipitator (ESP) market is entering a phase of measured but meaningful expansion, driven by tightening emissions standards, aging infrastructure demands, and incremental technological upgrades. Between 2020 and 2025, the global market grew from 6,500.0 million USD to 8,300.0 million USD, reflecting steady demand across utility and industrial sectors. Looking ahead to the 2026-2032 forecast period, the trajectory points toward a compound annual growth rate of 6.4%, with revenue projected to reach 12,790.0 million USD by 2032. This growth is not uniform. It is concentrated among a handful of established players, as reflected in a CR3 of 38.2% and CR5 of 55.0%, indicating that scale, technical expertise, and long-term service relationships continue to shape competitive dynamics. The market’s structure favors firms that can deliver not only hardware but also lifecycle support, performance upgrades, and integration with broader emission control systems.
Behind the headline numbers lie structural tensions that will define how companies position themselves over the next several years. The first challenge centers on the balance between capital intensity and operational efficiency. Advanced ESP configurations increasingly rely on digital control modules, corrosion-resistant materials, and hybrid filtration approaches, all of which raise upfront investment. At the same time, electrical energy consumption in large-scale installations remains substantial, translating into ongoing operating costs that plant operators must justify against performance gains. The second challenge is regulatory fragmentation. While federal and regional standards continue to push particulate limits downward, the pace and specifics of compliance requirements vary by jurisdiction and by industrial application, creating uneven demand cycles and complicating long-term planning. The third challenge involves the shift from greenfield installations to retrofit and rebuild activity. Many existing plants are prioritizing incremental upgrades that restore or exceed original collection efficiency without full system replacement, reshaping procurement patterns and service expectations.
Market Structure and the Shift Toward Service-Enabled Solutions
The ESP market’s evolution is increasingly defined by how suppliers manage the entire asset lifecycle rather than by initial equipment sales alone. Rebuild contracts, performance optimization, and integration with flue gas treatment systems are gaining weight in commercial negotiations. Companies that can demonstrate consistent collection efficiency, lower operating expenditure, and predictable maintenance intervals are finding stronger positioning in both utility and industrial segments. This shift is visible in recent contract activity and network expansion moves, where the emphasis is on extending service reach, supporting existing installations, and delivering measurable efficiency improvements. For decision-makers, the implication is clear: competitive advantage is moving from hardware specification to total cost of ownership and performance reliability over time.
Key Drivers Reshaping the ESP Market
Regulatory Pressure as a Baseline Demand Catalyst
Emissions regulations are the most consistent force behind ESP demand, and recent regulatory actions reinforce that trajectory. In the United States, the EPA’s Mercury and Air Toxics Standards require coal-fired power plants to contain filterable particulate emissions at 0.03 lb/MMBtu, accelerating the deployment of ESP systems that can meet or exceed those limits. At the same time, federal regulations on particulate matter emissions from industrial sources continue to compel facilities to adopt ESP technologies for compliance. These requirements do not merely create one-time purchase cycles; they establish a compliance floor that encourages operators to invest in systems capable of sustained performance, particularly where future tightening is anticipated. For suppliers, this environment rewards proven high-efficiency collection capability and the ability to document compliance outcomes.
Technological Innovation: Efficiency, Control, and Integration
Technological progress in ESP systems is increasingly focused on improving collection efficiency while moderating energy use and simplifying integration with downstream gas cleaning. High-efficiency collection up to 99.9% is now a benchmark that several leading providers reference, and achieving that level consistently often depends on advanced electrode design, better discharge management, and refined control logic. Equally important is the move toward smarter operation. AI-enhanced control systems and digital monitoring are being embedded into ESP platforms to adjust operating parameters in response to load changes, dust characteristics, and process conditions. This reduces wasted energy, stabilizes performance, and improves predictability for plant operators. Integration with flue gas conditioning and NOx reduction technologies further extends the value of ESP installations, especially in coal-fired utility settings where multi-pollutant control is a priority.
Recent developments illustrate how these innovations are being commercialized. Babcock & Wilcox secured more than 18 million USD in wet and dry ESP rebuild contracts for utility and industrial plants across the U.S. and Europe, emphasizing collection efficiency up to 99.9%, a clear signal that performance-led upgrades remain commercially attractive. FLSmidth expanded its service center network with a new facility in Dammam, Saudi Arabia, to support advanced emission control technologies including electrostatic precipitators, reflecting a strategy of positioning service capability closer to key industrial demand centers. Mitsubishi Heavy Industries delivered an ESP unit for a 700,000-tonne chemical pulp project in China, while Valmet shipped electrostatic precipitators to Nordic Paper’s Swedish Backhammar recovery boiler with completion targeted by the end of 2025. These activities show that demand is not limited to power generation; pulp and paper, chemical pulp production, and broader industrial recovery systems are also active deployment areas where ESP performance matters.
Demand-Side Shifts Across Power and Industrial Applications
Demand for ESP systems continues to be anchored by power generation, particularly where coal-fired and biomass-linked facilities must meet strict particulate limits or extend the viable operating life of existing assets. Beyond power, industrial applications are expanding the addressable market. Cement and lime processing, waste-to-energy and biomass, chemical and petrochemical operations, and specialized sectors such as pulp and paper recovery boilers all present distinct dust characteristics and operating conditions that shape ESP selection. The commercial implication is that a single ESP architecture rarely fits all applications. Suppliers that can tailor electrode design, gas flow management, and cleaning methods to specific process environments are better positioned to capture demand across multiple verticals. This is also where wet and dry system choices become strategically important, with selection driven by dust properties, moisture content, and downstream process constraints.
PW Consulting
Cost, Energy, and Supply Chain Considerations
Despite the positive demand outlook, cost and energy dynamics remain central to commercial decision-making. High capital and maintenance costs for advanced ESP systems incorporating digital control modules, corrosion-resistant materials, and hybrid filtration technologies require substantial upfront investment. Electrical energy consumption in electrostatic precipitators can also be substantial, with resulting high operating costs for large-scale installations. These factors encourage a more disciplined approach to procurement, where operators evaluate not only collection performance but also energy profile, maintenance intervals, and 부품 or material availability over the system’s lifespan. Supply chain considerations are becoming more prominent as well, particularly for specialized materials and control hardware. Providers that can streamline sourcing, localize support, and reduce downtime through predictable maintenance planning are likely to gain preference in competitive bidding situations.
Competitive Landscape and How Leading Players Differentiate
The ESP market is moderately concentrated, with a limited group of established companies holding meaningful share and long-standing relationships across utility and industrial markets. Market leadership is less about unit volume alone and more about the breadth of application coverage, demonstrated efficiency, service reach, and the ability to offer integrated emission control solutions. Several firms have built their positioning around high-efficiency systems, rebuild and retrofit capabilities, and sector-specific expertise. For example, some leaders emphasize wet and dry ESP systems for utility and industrial power generation with global installation experience, while others specialize in advanced ESP technologies integrated with gas cleaning systems for industrial emission control. Custom wet and dry ESP manufacturing for power, cement, and steel applications remains a differentiator for firms serving heavy industrial environments, and AI-enhanced control systems are increasingly part of the value proposition for providers targeting cement and industrial applications.
Worldwide Dry Electrostatic Precipitator Market
Company activity over the past two years highlights three strategic themes. First, performance-led rebuilds are a commercially meaningful pathway, as shown by major rebuild contracts focused on restoring or improving collection efficiency in existing plants. Second, geographic and service expansion is being used to reduce response times and strengthen relationships in important demand regions, including the Middle East. Third, sector-specific project wins in pulp, chemical pulp, and recovery boiler environments indicate that specialization can open doors beyond the largest power generation markets. Together, these moves suggest a market where incumbents are reinforcing their positions through service proximity, proven efficiency claims, and application-specific execution rather than relying solely on equipment pricing.
Consolidation, Fragmentation, and Entry Dynamics
The ESP market is not experiencing dramatic consolidation at the top, but it is showing signs of functional consolidation around capabilities. Buyers increasingly value suppliers that can handle design, installation, commissioning, and ongoing optimization under a coordinated framework. At the same time, niche players remain relevant where specialized applications, local support needs, or custom engineering demands create room for focused offerings. New entry is challenging but not impossible, especially where a company brings a clear technical advantage, such as a novel control approach, improved energy management, or a distinctive material solution that lowers lifecycle cost. In practice, the most resilient competitors are those that combine technical credibility with commercial flexibility, allowing them to serve both large-scale utility projects and smaller industrial retrofits without losing operational focus.
Forward Outlook: Trends Likely to Shape the Next 3-5 Years
Trend 1: Efficiency and Energy Management Will Become the Central Battleground
As regulations tighten and operating costs remain under scrutiny, the most important competitive differentiator will be the ability to deliver high collection efficiency without inflating energy consumption. Systems that can modulate power use intelligently, sustain efficiency across variable loads, and integrate with broader plant controls will be favored in both new installations and upgrades. This trend creates commercial opportunities for providers that can quantify energy savings, reduce maintenance burden, and show compliance durability over time. It also raises the stakes for suppliers still relying on static operating profiles, since plants are increasingly reluctant to accept high operating costs as a fixed requirement.
Electrostatic Chucks (ESCs) Market
Trend 2: Retrofit, Rebuild, and Life Extension Will Outweigh Greenfield Demand in Many Markets
In many regions, the near-term opportunity lies less in replacing entire systems and more in restoring performance, adapting to new fuel or process conditions, and extending service life. Rebuild contracts and targeted upgrades are likely to remain a significant share of activity, especially where plants need to meet current standards or prepare for future limits without committing to full replacement. This shift rewards vendors with strong field service capabilities, modular upgrade paths, and the ability to diagnose existing installations efficiently. For investors and manufacturers, it suggests that service-oriented revenue streams and upgrade kits may be as strategically important as flagship new-system sales.
Trend 3: Regional Service Footprints and Application Specialization Will Determine Access to Demand
Demand is geographically and sectorally uneven, and access to projects will increasingly depend on local presence and application knowledge. Expansion of service centers, local support teams, and region-specific engineering capacity can reduce friction in procurement and commissioning while improving responsiveness during operation. At the same time, companies that understand the dust and process nuances of specific industries will be better positioned to win in segments such as cement, waste-to-energy, chemical, and pulp and paper applications. The commercial opportunity here is to build repeatable sector playbooks rather than treating each project as a standalone customization exercise.
Risks and Uncertainties to Monitor
Several uncertainties could alter the pace or shape of market growth. Regulatory timelines may shift, particularly if compliance deadlines are adjusted or if enforcement emphasis changes across jurisdictions. Energy pricing and availability can affect operating economics, especially for large installations where power use is a major cost element. Material availability and lead times for specialized components may influence project scheduling and total cost. Finally, changes in fuel mix, plant retirement decisions, and the balance between coal, biomass, and alternative generation pathways can reshape where ESP demand appears and how quickly it materializes. Companies that monitor these variables closely will be better prepared to adjust pipeline planning and service capacity.
Strategic Recommendations for Decision-Makers
For ESP Manufacturers and Solution Providers
- Prioritize total-cost-of-ownership positioning by documenting efficiency outcomes, energy behavior, and maintenance predictability, not just collection performance at a point in time.
- Invest in service and rebuild capabilities, since retrofit and upgrade activity is likely to remain a durable source of revenue and customer contact.
- Build application-specific engineering playbooks for cement, waste-to-energy, chemical, and pulp and paper environments, where process conditions shape system selection and value claims.
For Investors and Strategic Partners
- Evaluate providers based on their ability to sustain high-efficiency claims in the field, expand service reach, and capture multi-pollutant integration opportunities rather than equipment scale alone.
- Watch for commercial signals in rebuild activity, regional service expansion, and sector project wins, as these often indicate where demand is becoming more concrete.
- Assess exposure to energy-intensive operating profiles and specialized material supply, since these factors influence margin stability and project execution risk over the forecast period.
For Plant Operators and Procurement Teams
- Select ESP solutions with a clear view of lifecycle cost, including energy consumption, maintenance intervals, and the feasibility of future upgrades as regulations or processes change.
- Use rebuild and retrofit pathways where feasible to meet current compliance targets while preserving capital flexibility for other plant priorities.
- Request performance evidence tied to operating conditions similar to your own, especially for dust characteristics, load variability, and integration with existing gas treatment systems.
The ESP market is moving toward a more performance-intensive, service-oriented, and application-aware phase of growth. That shift rewards companies that can combine proven collection efficiency with smarter operation, local support, and credible lifecycle economics. For organizations seeking to navigate this environment with greater precision, deeper segmentation data, company-level benchmarks, and customized strategic guidance can clarify where to commit resources and how to sequence next steps. Access the full PW Consulting report on the Electrostatic Precipitators market to explore detailed segmentation, competitive profiles, and forward-looking scenarios built for planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Electrostatic Precipitators (ESP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


