



Isoparaffin Solvents Market: Why 3.5% CAGR and $1.14B Trajectory Mask Hidden Shifts

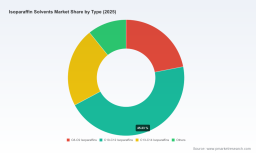
Isoparaffin Solvents Market: Navigating the Strategic Crossroads of Sustainability, Compliance, and Growth
The isoparaffin solvents market has entered a phase of measured maturation, shaped by tightening environmental mandates, evolving application demands, and a competitive landscape that rewards precision and compliance. After reaching a valuation of approximately 905.16 million USD in 2025, the sector is projected to expand at a compound annual growth rate of 3.5 percent through 2032, culminating in a market size near 1,144.78 million USD. This trajectory reflects more than steady demand growth; it signals a structural shift in how formulators, manufacturers, and regulators evaluate solvent performance, safety, and sustainability.
While the broader market moves forward on a moderate growth curve, the underlying dynamics are anything but uniform. Revenue distribution across regions and applications reveals a market that is geographically diversified but application-concentrated, with heavy reliance on industrial and specialty formulations that demand high-purity, low-odor hydrocarbon solvents. The competitive field remains moderately fragmented, with the top three players capturing roughly 28.3 percent of market share and the top five holding about 32.1 percent. Such concentration suggests that scale, technical differentiation, and regional capacity positioning matter significantly, yet they also leave space for niche players and innovative entrants to compete on performance, compliance, and supply reliability.
As 2025 transitions into the forecast period, the isoparaffin solvents market is being reshaped by environmental compliance, feedstock economics, and application-specific performance requirements. These forces are not isolated; they intersect to create both constraints and openings for companies that can align product portfolios with emerging regulatory and operational realities.
Market Landscape: Performance, Pressure Points, and the 2026-2032 Trajectory
A Market Defined by Steady Expansion and Structural Complexity
The isoparaffin solvents market has demonstrated consistent expansion across the 2020-2025 period, supported by enduring demand in paints and coatings, metalworking fluids, agrochemicals, cleaning formulations, pharmaceuticals, and personal care. This breadth of use underscores the versatility of isoparaffinic hydrocarbons as low-aromatic, low-odor alternatives to traditional solvent systems. However, breadth does not imply uniformity. Demand patterns vary by end-use performance requirements, regional manufacturing footprints, and regulatory exposure, creating a market where growth is unevenly distributed across segments and geographies.
Forecasting through 2032 suggests continued expansion, but also highlights a market that must balance volume growth with margin discipline. Feedstock-linked cost volatility and regulatory compliance costs place pressure on producer economics, while downstream customers increasingly prioritize product consistency, purity, and documentation. In this environment, market growth is less a simple function of demand volume and more a result of value capture through differentiated grades, technical support, and supply reliability.
Critical Challenges and Inflection Points
Several structural challenges are reshaping the competitive and operational landscape for isoparaffin solvent producers and users.
- Feedstock volatility and margin sensitivity: The production economics of isoparaffin solvents are closely tied to hydrocarbon feedstock dynamics. Price swings, availability constraints, and energy cost fluctuations can compress margins and complicate long-term pricing strategies. This sensitivity forces producers to manage cost structures carefully while maintaining product quality that meets stringent application specifications.
- Regulatory tightening on VOCs and aromatic content: Environmental regulation continues to redefine the acceptable boundary for solvent use. In multiple regions, including parts of South America, restrictions on volatile organic compound emissions and aromatic content have become more rigorous, especially for paints, coatings, and adhesives. These rules accelerate the shift toward high-purity isoparaffin grades but also increase compliance burdens and formulation complexity for downstream users.
- Performance versus sustainability trade-offs: Downstream formulators face a dual mandate. They need solvents that deliver consistent dissolution, evaporation, and rheological behavior, while also meeting sustainability goals and regulatory limits. Balancing performance, odor, toxicity perception, and carbon footprint is becoming a core product selection criterion rather than a secondary consideration.
These challenges are not merely obstacles. They are inflection points that reward players with strong technical portfolios, dependable supply, and clear regulatory alignment. Companies unable to navigate these pressures risk margin erosion, substitution risk, or loss of share in applications where compliance is a prerequisite.
Key Drivers Reshaping the Isoparaffin Solvents Market
Regulatory and Environmental Mandates as a Growth Accelerator
Environmental regulation is one of the most influential forces behind current market dynamics. In the United States, EPA VOC limits and in Europe, the Solvent Emissions Directive continue to steer formulators away from higher-aromatic solvent systems toward high-purity, low-aromatic alternatives. Isoparaffin solvents, with their low odor and reduced aromatic content, are increasingly positioned as compliant substitutes in applications where emissions limits and workplace safety requirements are tightening.
This regulatory pressure is particularly visible in regions where paint, coating, and adhesive manufacturers must meet stricter emission thresholds. In South America, for example, countries such as Brazil and Argentina have moved to tighten VOC emission standards between 2023 and 2025, mandating reduced aromatic content in solvents used across paints, coatings, and adhesives. Such measures do not simply constrain the market; they redirect it. Demand flows toward solvent grades that can satisfy compliance requirements without sacrificing application performance, and isoparaffins are well placed to benefit from that redirection.
Product Innovation Centered on Purity, Odor, and Application Fit
Technological progress in isoparaffin solvents is increasingly focused on refining product attributes rather than simply expanding volume. Leading suppliers are updating technical documentation, emphasizing low odor, low aromatic content, and narrow boiling ranges, and aligning products with specific formulation needs in coatings, cleaning, metalworking, and personal care. This is not cosmetic repositioning; it reflects a real shift in market expectations. Formulators want solvents that reduce odor complaints, improve workplace conditions, and enable cleaner formulations while preserving solvency performance.
Recent product and documentation updates from major players illustrate this direction. ExxonMobil Chemical updated the technical datasheet for Isopar M, highlighting low aromatic content. Shell Chemicals released an updated product datasheet for ShellSol, emphasizing low odor and suitability for surface coatings. These actions signal that competitive advantage is increasingly linked to grade-level differentiation and technical clarity, not just brand recognition. When downstream customers compare solvent options, the ability to demonstrate purity, consistency, and application-specific fit can be decisive.
Demand-Side Shifts in Coatings, Metalworking, and Specialty Formulations
Demand for isoparaffin solvents is being reshaped by changing expectations in major application categories. Paints and coatings remain a central use case, but the drivers within this segment are evolving. Coatings formulators are under pressure to reduce VOC emissions, improve indoor air quality, and support sustainability claims. Metalworking fluids and industrial cleaning applications continue to value low-odor, effective hydrocarbon solvents that support degreasing, parts cleaning, and process consistency. Agrochemical formulations also contribute to demand, where solvent choice can influence product stability, handling, and regulatory acceptability.
At the same time, personal care and pharmaceutical applications, while smaller in absolute terms, represent high-value segments where purity, odor control, and regulatory documentation matter disproportionately. In these markets, even modest volume growth can be strategically meaningful because the margin and differentiation potential is higher. The broader implication is that demand growth is not only a volume story; it is increasingly a value story, with certain applications generating stronger pull for premium, high-purity grades.
Capacity Adjustments and Regional Supply Positioning
Supply-side dynamics are also influencing market direction. Recent capacity actions by major producers point to a focus on regional availability and application-oriented supply reliability. In February 2025, Shell Chemicals inaugurated a new isoparaffin solvent production plant in Brazil, increasing local capacity by 30 percent. In March 2025, Chevron Phillips Chemical increased its manufacturing capacity for isoparaffin solvents. These developments matter because regional production can shorten supply chains, reduce logistical risk, and better serve local regulatory and application requirements.
For buyers, the practical implication is greater importance placed on supply continuity and regional support. For producers, the lesson is that capacity deployment is most effective when aligned with local demand intensity, compliance conditions, and distribution capabilities. As capacity expands in key regions, competition may intensify on service level, formulation support, and availability rather than price alone.
Competitive Landscape: Positioning, Differentiation, and Market Evolution
How Leading Players Are Shaping the Field
The competitive landscape in isoparaffin solvents is shaped by large chemical and energy-linked companies with broad hydrocarbon portfolios and strong technical reputations. These players compete not only on scale, but on product clarity, application support, and regulatory alignment. Several firms stand out for distinct positioning.
Solvent Naphtha Market
- Shell Chemicals has built a strong identity around ShellSol isoparaffins, emphasizing high-purity synthetic hydrocarbon solvents with narrow boiling ranges and low impurities. The brand is associated with coatings, inks, dry cleaning, and industrial applications, and recent updates have reinforced low-odor performance and surface coating suitability. Its February 2025 plant inauguration in Brazil also demonstrates a strategy of strengthening regional supply and local capacity.
- Chevron Phillips Chemical Company is recognized for Soltrol isoparaffin solvents, including Soltrol 130, which are positioned as low-odor and compatible with parts cleaning, degreasing, paints, inks, and agrochemical formulations. The March 2025 capacity increase signals continued investment in meeting demand for versatile, compliant solvent grades.
- ExxonMobil Chemical markets Isopar fluids with a focus on high purity, low aromatic content, and odorless properties for personal care, coatings, cleaning, and metalworking. The July 2025 technical datasheet update for Isopar M underscores a strategy of reinforcing product differentiation through documented purity and application-specific attributes.
- Braskem S.A. and TotalEnergies SE both participate in the market through broader hydrocarbon and chemical portfolios, supplying isoparaffin solvents for industrial and specialty applications, including paints and coatings. Their relevance lies in portfolio breadth and the ability to integrate solvent offerings within larger supply relationships.
- INEOS Group, Idemitsu Kosan, Calumet Specialty Products Partners, Sasol Limited, and SK Global Chemical each bring regional or specialized strengths. INEOS focuses on industrial cleaning, coatings, and personal care; Idemitsu Kosan supplies IP Clean and IP Solvent products; Calumet emphasizes industrial cleaning and coatings; Sasol participates through its chemical portfolio; and SK Global Chemical offers ISOL isoparaffins for industrial solvents and formulations.
What connects these players is a shared recognition that isoparaffin solvents are no longer commoditized cleaning or dissolving agents alone. They are increasingly evaluated as engineered chemical inputs with specific performance, safety, and compliance profiles. In this context, technical documentation, application expertise, and consistent quality become central competitive tools.
Strategic Positioning and Differentiation Levers
Leading companies are pursuing differentiation through several interlocking levers.
De-Aromatic Solvents Market
- Purity and low-aromatic positioning: In markets where VOC limits and aromatic content restrictions are tightening, high-purity grades gain an advantage. Suppliers that can clearly document low aromatic content and odor performance strengthen their relevance for compliant formulations.
- Application-focused product architecture: Rather than offering a single generic solvent, successful players tailor grades to specific uses such as coatings, metalworking, cleaning, personal care, and agrochemicals. This application alignment improves customer fit and reduces substitution risk.
- Regional capacity and supply visibility: Local production and reliable logistics reduce vulnerability to freight volatility and can improve responsiveness to regional regulatory changes. Brazil’s capacity expansion and broader capacity increases elsewhere illustrate the strategic value of placing supply closer to demand.
- Technical communication and datasheet clarity: Updated datasheets and product documentation are not administrative tasks; they are market-facing signals. Clear specifications help formulators validate compliance, compare alternatives, and justify solvent selection to internal and external stakeholders.
Together, these levers create a competitive environment where advantage is built through reliability, specificity, and compliance readiness rather than through broad volume claims alone.
Market Evolution: Consolidation, Fragmentation, and Entrant Dynamics
The market’s moderate concentration suggests room for both consolidation and targeted fragmentation. On one hand, large integrated players benefit from scale, feedstock access, and portfolio breadth, which can support pricing resilience and global reach. On the other hand, the presence of multiple capable regional and specialty suppliers means that differentiation by region, application, and grade remains viable.
Over the next several years, the landscape may evolve along three directions. First, selective consolidation could occur as players seek to strengthen geographic coverage, product ranges, or application expertise. Second, fragmentation may persist or deepen in high-value specialty niches where purity, odor, and documentation command premiums. Third, new entrants or expanding regional producers may gain ground by addressing local compliance needs and supply reliability more nimbly than global incumbents. The outcome will depend on how well companies align capacity, product grades, technical support, and regulatory preparedness with regional demand patterns.
Future Outlook: Three Trends Shaping the 2026-2032 Window
Trend 1: Compliance-Driven Grade Migration Toward High-Purity Isoparaffins
As VOC limits and aromatic content rules continue to tighten across multiple regions, a clear trend is the migration toward high-purity isoparaffin grades that can satisfy regulatory requirements while maintaining formulation performance. This shift is not just a regulatory response; it is becoming a procurement and product development preference. Formulators are increasingly choosing solvents that reduce compliance risk, lower odor concerns, and support sustainability narratives.
The commercial implication is that demand may grow more strongly for specific premium grades than for the market as a whole. Producers and buyers alike should expect a bifurcation in which high-purity, well-documented products capture disproportionate value, while undifferentiated grades face greater substitution pressure. The opportunity lies in aligning product portfolios with the grades that regulatory and performance trends are pulling toward.
Trend 2: Regional Supply Diversification and Near-Market Capacity
Another likely trend is continued regional diversification of supply. Recent capacity expansions in South America and capacity increases elsewhere suggest that producers are looking to reduce exposure to long supply chains and better serve local demand and compliance conditions. Over the forecast period, regional availability may become a more important purchase criterion, especially in markets where logistics cost, lead time, and regulatory context vary significantly.
For buyers, this trend creates opportunities to diversify supply sources and reduce dependency on a single route. For producers, it emphasizes the value of localized capacity, distribution partnerships, and application support that match regional market conditions. The risk is that overexpansion in one region could create localized oversupply, while underinvestment in another could leave demand underserved and open the door to imports or competitor entry.
Trend 3: Application-Specific Value Creation in Coatings, Cleaning, and Specialty Use
A third trend is the growing importance of application-specific value creation. Paints and coatings will remain a dominant demand pool, but the most strategic growth may come from tailored solutions that address odor, purity, and regulatory documentation in coatings, metalworking fluids, cleaning, and specialty formulations such as personal care and pharmaceuticals. These segments reward precision, consistency, and technical support, and they can generate stronger margins than bulk-oriented applications.
This trend opens opportunities for suppliers that can provide not just solvent volume, but formulation guidance, compliance documentation, and grade optimization. It also creates risk for players that compete primarily on price without offering the technical assurance that formulators increasingly require. In practice, the market is likely to reward those who treat isoparaffins as part of a broader solution rather than as a standalone commodity.
Strategic Implications and Action Guidance for Decision Makers
For Manufacturers and Producers
Producers should prioritize grade-level differentiation and regulatory readiness. As compliance becomes a stronger purchase driver, the ability to provide high-purity, low-aromatic, low-odor solvents with clear documentation will matter more than broad product claims. Capacity investments should be evaluated not only for volume potential but also for regional fit, feedstock exposure, and the ability to serve compliance-sensitive applications. Technical communication, including updated datasheets and application guidance, should be treated as a competitive asset that helps customers justify solvent selection and reduce formulation risk.
For Investors and Financial Stakeholders
Investors should look beyond aggregate market growth and focus on where value is concentrating. Segments and grades tied to regulatory compliance, odor reduction, and high-purity requirements are more likely to deliver durable demand and margin resilience than undifferentiated bulk solvent exposure. Regional supply dynamics also matter: capacity expansions and local production can strengthen competitive positioning, but they also create execution risk if demand growth is uneven. A careful assessment of feedstock exposure, regulatory alignment, and application mix is essential when evaluating companies in this space.
For Procurement and Formulation Teams
Procurement and formulation decision-makers should treat isoparaffin selection as a strategic variable rather than a tactical purchase. Compliance documentation, aromatic content, odor profile, and supply reliability should be weighted alongside price. Because regulatory requirements and application performance needs differ by region and formulation, it is wise to validate supplier capability across the specific grades and use cases that matter most. Diversifying supply sources and seeking suppliers with strong regional presence can reduce vulnerability to logistics disruptions and regulatory shifts.
Why Timely, Granular Intelligence Matters
The isoparaffin solvents market is moving through a period in which aggregate growth numbers tell only part of the story. Regulatory pressure, grade-level differentiation, regional capacity shifts, and application-specific demand are creating a landscape where timing, specificity, and supply positioning determine outcomes. For companies making investment, production, or procurement decisions, access to detailed segmentation data, regional breakdowns, and company-level movement tracking can materially improve decision quality. Broad directional awareness is useful, but the real advantage lies in understanding which grades, regions, and applications are gaining or losing traction, and how competitors are adjusting capacity and product positioning in response.
For organizations that need deeper coverage of market size by segment, regional demand patterns, competitive activity, and customized strategic recommendations, a comprehensive market research report can provide the structured detail required to move from general insight to concrete action. Detailed data, scenario-ready segmentation, and forward-looking assessment are particularly valuable when planning capacity, evaluating suppliers, or positioning product portfolios for compliance-led demand shifts.
Conclusion
The isoparaffin solvents market is not experiencing a sudden disruption; it is undergoing a deliberate restructuring shaped by environmental compliance, product purity expectations, regional supply strategy, and application-specific performance needs. The forecast growth path through 2032 suggests a market that continues to expand, but the more important story is where value is being created and where competitive advantage is being built. High-purity, low-odor, compliance-aligned grades are gaining relevance, regional capacity is becoming a strategic differentiator, and technical clarity is increasingly part of the commercial battleground.
PW Consulting Automotive & Machinery Research Center
For executives, investors, and procurement leaders, the practical question is no longer whether isoparaffin solvents remain important, but how to position for the next phase of demand migration, regulatory pressure, and supplier competition. Companies that align their strategies with these trends, and that invest in the intelligence needed to track them closely, are better placed to capture value in a market where growth and differentiation are increasingly inseparable.
For detailed analysis of this topic, please visit the official page: Isoparaffin Solvents Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


