



Data Center Busway Market 2026: 9% CAGR Means the Competition Just Changed

Data Center Busway Market 2025–2032: Strategic Shifts, Power Density, and the Path to Sustainable Scalability
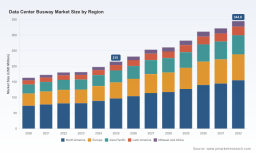
The data center busway market has entered a phase of accelerated structural transformation, driven by the convergence of artificial intelligence workloads, hyperscale expansion, and evolving power distribution requirements. Valued at approximately USD 215.0 million in 2025, the market has grown from USD 163.15 million in 2020, reflecting a compound annual growth rate of 9.0 percent across the forecast horizon through 2032, when revenues are projected to reach USD 344.8 million. This trajectory is not merely a function of incremental capacity additions. It reflects a fundamental rethinking of how power is routed, tapped, and managed within increasingly dense and modular computing environments. For executives, investors, and procurement leaders, the busway segment represents both a direct response to next-generation infrastructure demands and a lens through which broader shifts in data center design, material economics, and regulatory compliance can be understood.
The market’s expansion has been relatively consistent in recent years, yet the composition of growth is shifting. Historical performance from 2020 to 2025 illustrates steady upward movement, with particular acceleration in the most recent intervals as AI-driven deployment cycles matured. The forward outlook suggests that the pace will be sustained, though not uniformly distributed across all end-use contexts or product configurations. Rather than treating busway systems as commoditized electrical distribution components, industry participants are increasingly positioning them as integral elements of high-density, rapidly deployable, and energy-aware data center architectures. This reframing is reshaping competitive dynamics, procurement criteria, and long-term investment theses.
Market Landscape and Core Challenges
The current market environment is characterized by robust demand signals, but also by structural frictions that will define competitive outcomes over the next several years. Three intersecting challenges stand out as particularly consequential for operators, suppliers, and capital allocators alike.
Power Density and Architectural Compression
The transition toward high-density computing environments is compressing traditional layout assumptions. As rack power densities increase and AI clusters demand higher amperage distribution, legacy cable-based or fixed-tray approaches are encountering spatial, thermal, and installation constraints. Busway systems are gaining relevance because they offer modular tap-off flexibility, shorter deployment cycles, and the ability to adapt to evolving white-space configurations. However, this shift is not automatic. Integrating high-ampacity busway into prefabricated or containerized data center pods requires coordinated engineering across power, cooling, and structural dimensions. The challenge for suppliers is to deliver systems that balance current-carrying capacity, footprint efficiency, and ease of modification without introducing complexity that undermines the very speed advantages busway is meant to provide.
Material Cost Volatility and Conductor Selection
Raw material dynamics are becoming a more prominent factor in busway economics. Copper prices moved to 15-month highs in 2025 amid supply disruptions and sustained data center demand, placing upward pressure on manufacturing costs for copper-dependent systems. At the same time, aluminum conductor options are gaining attention for their weight and installation labor advantages in high-density deployments. This creates a strategic tension: copper remains the default expectation for many mission-critical specifications, while aluminum-based designs can reduce weight and installation effort when properly engineered and certified. Manufacturers and procurement teams must navigate performance expectations, total installed cost, and long-term reliability rather than relying on material conventions alone.
PW Consulting
Regulatory and Compliance Pressures
Regulatory expectations are increasingly shaping infrastructure upgrade decisions. In Europe, the Energy Efficiency Directive has drawn attention to the need for data center operators to modernize infrastructure, including busway replacement and upgrades in certain contexts, to support compliance objectives. In parallel, safety and reliability expectations in mission-critical facilities continue to elevate the importance of certified solutions. For example, UL listing requirements for specific busway offerings have become a meaningful differentiator for operators seeking assured reliability in data center applications. These dynamics do not simply add cost; they reshape the value proposition of busway systems by linking power distribution decisions to broader energy, safety, and operational resilience goals.
Key Drivers Reshaping the Market
The growth trajectory of the data center busway market is being propelled by a set of reinforcing drivers that extend beyond simple capacity expansion. Understanding how these forces interact is essential for anticipating where demand will concentrate and which product strategies will gain traction.
Technology Innovation in High-Ampacity, Modular Distribution
Product development is increasingly focused on scalable, high-current busway architectures that can adapt to rapidly changing white-space layouts. One of the most notable shifts is the move toward systems capable of supporting amperage levels well beyond conventional server room distributions, including solutions designed for environments where high-ampacity busway systems exceeding 4000A are required. This trend is closely tied to hyperscale AI data center construction, where power distribution must accommodate dense compute clusters while preserving flexibility for future expansion.
Innovation is also evident in toolless tap-off designs, double-stack configurations, and integrated monitoring capabilities. Double-stack busway systems, for instance, are being introduced to support growing AI data center demands while preserving white space, effectively enabling higher power density without proportionally increasing the floor footprint. At the same time, modular plug-in tap designs are reducing installation friction and enabling faster reconfiguration as workloads evolve. These advances are not isolated product features; they collectively support a broader architectural shift toward busway as a dynamic distribution layer rather than a static electrical accessory.
AI-Driven Demand and Hyperscale Deployment Patterns
The most powerful demand-side force is the proliferation of AI-focused infrastructure. Hyperscale AI data center construction is driving demand for high-ampacity busway systems, particularly in environments where power distribution must scale in lockstep with accelerated compute density. This is altering procurement priorities: speed of deployment, modularity, and compatibility with prefabricated modules are increasingly valued alongside raw current-carrying capacity.
The trend is visible in recent product and exhibition activity. New EcoStruxure Pod Data Center solutions have been introduced with high-power busway integrated alongside liquid cooling and prefabricated modules for AI cluster deployments, illustrating how busway is being embedded into broader pod-level architectures. Similarly, scalable high-capacity double-stack track-style busway systems have been announced to address growing AI data center demands while preserving white space. At major industry gatherings, multiple manufacturers have showcased modular data center solutions that emphasize busway power distribution as a core element of next-generation AI infrastructure. These developments suggest that busway is no longer a peripheral consideration; it is becoming a defining component of AI-ready data center design.
Policy, Efficiency Mandates, and Certification-Driven procurement
Policy and regulatory frameworks are influencing both retrofit and greenfield decisions. Efficiency mandates and energy-related directives are pushing operators to evaluate infrastructure upgrades more holistically, including busway replacement where it contributes to compliance or operational improvement. At the same time, certification and listing requirements are becoming more salient in procurement processes for mission-critical facilities. This is especially relevant where reliability, safety, and interoperability must be demonstrable through recognized standards.
The practical effect is a more discerning buyer environment. Operators are not simply seeking the lowest upfront cost; they are increasingly weighing lifecycle performance, compliance readiness, and integration with broader facility systems. For suppliers, this means that product leadership is increasingly defined by the ability to provide certified, monitored, and easily integrated solutions rather than by volume alone. In this context, busway systems that combine protection, metering, monitoring, and modular tap-off functionality are well positioned to align with evolving procurement criteria.
Supply Chain and Cost Structure Considerations
Supply chain conditions and material economics continue to shape product strategy and pricing dynamics. Copper price movements have introduced cost variability that affects both manufacturers and end users, particularly in segments where copper remains the dominant conductor choice. This has reinforced interest in aluminum conductor options, which can reduce weight and installation labor in high-density deployments. The strategic implication is that conductor selection is becoming a more explicit trade-off analysis, balancing electrical performance, mechanical handling, certification requirements, and installed cost.
In parallel, the broader supply chain emphasis on modularity and prefabrication is encouraging busway designs that can be shipped, assembled, and commissioned with minimal on-site customization. This aligns with the pace demands of hyperscale and colocation projects, where schedule certainty is often as valuable as technical performance. Suppliers that can standardize high-value configurations while maintaining flexibility for site-specific requirements are likely to capture disproportionate advantage in a market where deployment speed is a critical success factor.
Competitive Landscape and Leading Strategies
The competitive environment in the data center busway market is moderately concentrated, yet it is evolving quickly as suppliers differentiate around architecture, integration, and application-specific engineering. With a combined share held by the top three players at approximately 24.6 percent and the top five at about 26.2 percent, the market remains relatively fragmented at the top, leaving room for specialized positioning, regional strength, and targeted innovation. The strategic question is not simply who holds the largest share today, but which companies are building durable advantages in high-growth subsegments tied to AI, modularity, and compliance-driven upgrades.
Leading Players and Strategic Positioning
Several established manufacturers are defining the market’s direction through product architectures that explicitly address high-density AI workloads, modular deployment, and integrated monitoring. Their approaches illustrate how busway is being repositioned from a utility product to a strategic infrastructure component.
Schneider Electric has emphasized integrated pod-level solutions that combine high-power busway with prefabricated modules and liquid cooling for AI cluster deployments. Its recent product launch of EcoStruxure Pod Data Center solutions featuring high-power busway integrated with liquid cooling and prefabricated modules reflects a strategy centered on holistic, rapid-deployment architectures. The company’s exhibition activity has also highlighted busway integration with power shelf concepts for 48V AI systems, signaling attention to evolving power architectures as well as traditional distribution.
Eaton Corporation has focused on modular tap-off flexibility and scalable white-space optimization through track-style busway systems. Its Pow-R-Way III and PowerWave 2 platforms are positioned around modular tap-off for scalable white-space and high-density power distribution. By showcasing modular data center solutions including busway power distribution at Data Center World 2026, Eaton reinforced a strategy that aligns busway with adaptable facility layouts and repeatable deployment patterns.
Vertiv has advanced high-capacity, space-efficient designs with its PowerBar Track and double-stack busway systems. Its offerings support high current levels with copper and aluminum options and emphasize toolless tap-offs for AI data center white-space optimization. The recent announcement of a scalable high-capacity double-stack PowerBar Track busway system for growing AI data center demands illustrates a clear focus on density, scalability, and space preservation.
ABB Ltd has concentrated on integrated protection, metering, and monitoring within low-voltage busway systems for server room distribution. Its Lmax-T systems are designed to support data center server room distribution with integrated protection, metering, and monitoring up to 86 kW per rack. This positions ABB around operational visibility and localized power management, which is increasingly valued in environments where granular monitoring supports efficiency and reliability objectives.
Siemens AG has pursued smart monitoring and strategic power distribution partnerships, with aluminum-based busway systems designed for high-density AI data centers. Its approach underscores the growing importance of monitoring-enabled systems and collaborative ecosystem positioning in high-value segments.
LS Cable & System has built a differentiated presence around modular plug-in taps and UL listing for high-capacity AI and energy-efficient data center power distribution. Its Data-way™ busway with modular plug-in taps and UL listing emphasizes mission-critical reliability and readiness for next-generation AI data centers, a positioning reinforced by its exhibition presence at Data Center World 2026.
Other notable participants contribute additional variety to the competitive field. Legrand offers data center busway solutions for modular power distribution in mission-critical facilities. nVent provides custom medium- and high-voltage bus systems for industrial and data center power applications, expanding the scope beyond standard low-voltage distribution. EAE Electric offers busway systems up to 6300A with data center-specific solutions for power distribution, highlighting the persistent demand for very high-current configurations in specialized environments.
Strategic Differentiation and Evolving Market Structure
Across these players, differentiation is increasingly rooted in four dimensions: current capacity and conductor flexibility, modularity and deployment speed, integration with monitoring and protection, and certification or listing readiness for mission-critical use. Companies that can combine these attributes within repeatable, prefabrication-friendly architectures are gaining leverage in a market where AI-driven projects reward both performance and schedule certainty.
The market structure appears likely to evolve through a mix of consolidation, specialization, and ecosystem positioning rather than through a single dominant wave of unification. Large, globally integrated suppliers benefit from breadth, engineering resources, and cross-selling potential across power management portfolios. At the same time, specialized or regionally strong players can compete effectively by emphasizing certification, customized high-current solutions, or rapid responsiveness to local procurement requirements. New entrants and adjacent players may also find openings by targeting specific niches such as very high-ampacity systems, aluminum-based designs, or modular pod-integrated busway solutions. The overall trend is toward a more application-aware competitive landscape, where Winning strategies depend on how well a product aligns with the operational, regulatory, and architectural priorities of the end facility.
Future Trends and Commercial Opportunities
Looking ahead to the next three to five years, several trends are likely to shape the data center busway market and create distinct commercial opportunities. These trends are interconnected, and their combined effect will determine which product categories, geographies, and use cases capture the most value.
Trend 1: High-Ampacity, AI-Optimized Busway as a Default Consideration
As AI workloads continue to drive higher power densities, high-ampacity busway systems will become less of a specialized option and more of a baseline consideration for new hyperscale and large colocation builds. The practical opportunity lies in designing for scalability from the outset: systems that can accommodate future power increases, support modular tap expansion, and integrate with cooling and prefabricated infrastructure will command stronger interest than fixed, single-purpose configurations. Commercially, this favors suppliers that can offer proven high-current performance, conductor flexibility, and documented compatibility with AI cluster layouts. The risk is that demand may become concentrated in a narrower set of high-specification systems, intensifying competition among suppliers that can meet those requirements at scale.
Trend 2: Material Strategy and Total Installed Cost as Competitive Levers
Material economics will continue to influence product design and procurement decisions. Copper price volatility and the practical benefits of aluminum conductor options in high-density deployments will encourage more explicit total cost evaluations, including weight, handling, installation labor, and long-term maintainability. This creates an opportunity for manufacturers to differentiate through engineered solutions that justify material choices with measurable installation and operational advantages. It also introduces a risk: if certification, customer familiarity, or application-specific performance requirements strongly favor one conductor type in certain segments, the ability to substitute may be limited. The most resilient strategies will likely involve offering credible options across conductor types while clearly mapping each to specific use cases and total cost profiles.
Busway-Bus Duct Market
Trend 3: Compliance, Monitoring, and Lifecycle Value as Procurement Differentiators
Regulatory efficiency expectations and mission-critical reliability standards are likely to elevate the importance of compliance-ready, monitored busway systems. As operators align infrastructure upgrades with energy efficiency and operational resilience goals, busway solutions that incorporate protection, metering, and monitoring will be better positioned to support both compliance and operational management objectives. The commercial opportunity here extends beyond hardware sales to includes integrated value propositions that reduce lifecycle risk, support audits or reporting, and simplify future modifications. A key uncertainty is the pace and uniformity of regulatory adoption across regions, which could create uneven demand patterns and require suppliers to remain agile in different compliance environments.
Data Center Rack Market
Actionable Implications for Decision Makers
The data center busway market is evolving from a component-level discussion into a strategic infrastructure question. The following implications are most relevant for manufacturers, investors, and procurement leaders seeking to act on current dynamics rather than react to them.
For Manufacturers and Solution Providers
- Prioritize architectures that combine high-current capability with modular tap flexibility and toolless or low-friction installation, especially where AI-driven white-space optimization is a priority.
- Develop clear conductor strategies that address both copper and aluminum use cases, supported by certification, testing, and documented total installed cost arguments rather than relying on convention alone.
- Strengthen integration narratives around monitoring, protection, and prefabricated module compatibility, since these attributes increasingly align with procurement criteria for mission-critical and efficiency-focused facilities.
For Investors
- Focus on companies with credible positioning in high-ampacity, AI-related deployments and evidence of product momentum through launches, trade presence, or qualified project pipelines.
- Assess exposure to material cost dynamics and supply chain resilience, particularly where product portfolios depend heavily on a single conductor type or limited sourcing pathways.
- Look for differentiation that is difficult to replicate quickly, such as certified solutions, integrated monitoring capabilities, or strong alignment with modular/pod-based data center architectures.
For Procurement and Infrastructure Leaders
- Evaluate busway options against total lifecycle criteria, including deployment speed, reconfiguration flexibility, monitoring and protection integration, and compliance readiness, rather than basing decisions solely on initial price.
- Plan for future power density increases by specifying systems that can scale in amperage and tap capacity without requiring wholesale redesign of the distribution layer.
- Verify certification and listing status early in the selection process, especially where mission-critical reliability and regulatory alignment are explicit project requirements.
The breadth of forces shaping this market—from AI-driven power density and material economics to efficiency mandates and modular deployment models—makes detailed, up-to-date segmentation and company-level intelligence highly valuable. For decision makers evaluating market entry, capacity expansion, product roadmap priorities, or procurement strategies, a fuller view of subsegment dynamics, regional variation, and competitive movements can materially improve planning accuracy. More comprehensive data and tailored analysis are available through the complete PW Consulting market report, which provides deeper segmentation detail and customized strategic guidance for specific business contexts.
For detailed analysis of this topic, please visit the official page: Data Center Busway Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


