



Tax Software Market: Why Cloud Adoption and 9% CAGR Shift the Competitive Landscape

Navigating the Tax Software Market: Strategic Trends and Commercial Opportunities
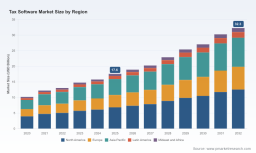
The global tax software market is undergoing a structural transformation driven by technological advancement, regulatory complexity, and shifting user expectations. Valued at approximately $17.6 billion in 2025, the market has expanded steadily from $10.2 billion in 2020, reflecting a compound annual growth rate of 9.0 percent through 2032. By the end of the forecast horizon, total market revenue is projected to approach $32.3 billion, underscoring sustained institutional and consumer demand for digital tax solutions. This growth trajectory is not merely a function of population expansion or inflation; it represents a fundamental shift in how tax compliance, reporting, and advisory services are delivered. Organizations that understand the underlying drivers, competitive dynamics, and emerging friction points will be best positioned to capture value in the coming years.
Market Landscape and Core Challenges
The market's expansion has been broad-based, with cloud-based solutions now representing the largest share of revenue, reflecting a decisive migration away from legacy on-premises deployments. Individual tax filing continues to anchor volume, while business and corporate tax management segments contribute meaningful but more specialized revenue streams. Geographically, adoption patterns vary significantly, with mature markets showing high penetration and emerging regions accelerating digital onboarding as regulatory frameworks modernize and internet infrastructure improves.
Despite the favorable growth backdrop, the industry faces several structural challenges that will shape competitive outcomes over the next five years. First, regulatory fragmentation and compliance velocity are intensifying. Tax authorities across jurisdictions are updating filing formats, validation rules, and electronic submission requirements at an accelerating pace. Software vendors must continuously align their platforms with IRS Modernized e-File standards, state-level franchise tax mandates, and error-checking protocols. The operational burden of maintaining compliance across multiple jurisdictions creates a high barrier to entry and rewards vendors with robust regulatory monitoring and rapid update cycles.
Second, user experience expectations are rising faster than legacy architectures can accommodate. Both individual filers and professional preparers increasingly expect intuitive interfaces, guided workflows, automated data ingestion, and real-time error feedback. Platforms that rely on manual form entry or fragmented dataflows risk losing adoption to solutions that reduce cognitive load and accelerate filing turnaround. This shift is particularly pronounced among self-employed professionals and small business owners who prioritize simplicity and predictable pricing.
Third, cost structure pressures are reshaping procurement decisions. Professional-grade tax software typically carries annual licensing costs in the range of $700 to $1,275 for multi-user access, a meaningful expense for smaller firms and independent preparers. While these investments deliver compliance assurance and workflow efficiency, margins remain sensitive to pricing models, update frequency, and the perceived value of advanced features. Vendors must balance feature richness with affordability, particularly as free or low-cost guided filing options expand for eligible taxpayers and raise expectations for baseline functionality across the market.
These challenges intersect at a critical inflection point: the market is moving from a compliance-centric model toward an experience- and outcomes-centric model. The winners will be those that convert regulatory complexity into simplified user journeys, maintain update reliability at scale, and deliver clear return on investment for both professional firms and end users.
Key Drivers Shaping Market Evolution
Several interconnected forces are accelerating demand and redefining value propositions across the tax software ecosystem.
Technological Innovation and Workflow Automation
Cloud-native architectures, automated form population, and integration with financial data sources are reducing manual effort and error rates. Guided preparation workflows, predictive error checks, and rapid e-filing feedback loops are becoming table stakes rather than differentiators. For professional preparers, annual software updates that incorporate new tax laws, form revisions, and validation enhancements are essential to maintaining throughput and compliance accuracy. The release cadence and update transparency of leading platforms directly influence user retention and referral momentum within accounting and tax practices.
Policy and Regulatory Environment
Regulatory modernization is both a constraint and a catalyst. Tax authorities are progressively mandating electronic submissions, enhanced error validation, and structured data formats to improve processing efficiency and reduce rejection rates. Providers must demonstrate compliance with assurance testing systems and maintain approved status to operate within official filing channels. At the same time, tiered access models, such as no-cost guided preparation for eligible income brackets, expand the addressable user base while pressuring vendors to offer clear differentiation for premium features. The net effect is a more standardized compliance baseline, with competitive advantage shifting toward usability, advisory extensions, and multi-jurisdiction coverage.
Demand-Side Behavior Shifts
End users are increasingly treating tax software as an annual operating tool rather than a one-time filing utility. Individuals and small business owners value continuity, data portability, and time savings. Professional firms seek platforms that scale across seasons, support diverse client profiles, and integrate with broader practice management workflows. The preference for cloud delivery amplifies these expectations by enabling remote access, collaborative preparation, and centralized document management. As a result, switching costs are rising for users who have invested in historical data, trained workflows, and integrated ecosystems, favoring vendors that can deepen lifetime value through reliability and extensibility.
Cost Structure and Procurement Dynamics
The economics of tax software procurement are evolving as firms weigh licensing fees against labor costs, error remediation, and seasonal capacity constraints. Multi-user access models, update subscriptions, and support expectations shape total cost of ownership. For smaller practices, predictable annual pricing and straightforward update processes can be decisive, while larger firms prioritize scalability, role-based access, and audit-ready documentation. The market is gradually rewarding vendors that offer transparent pricing, efficient update delivery, and demonstrable time savings, particularly in environments where preparer labor remains a significant cost driver.
Competitive Landscape and Leading Strategies
The market is characterized by a concentrated core of established vendors alongside a long tail of specialized providers serving distinct user segments. Intuit maintains a prominent position in the individual and self-employed segments, leveraging broad brand recognition, guided filing experiences, and a wide distribution footprint. H&R Block complements this landscape with a strong retail and digital presence, emphasizing accessible filing pathways and small business support. In the professional segment, Wolters Kluwer and Thomson Reuters serve accounting firms and tax practitioners with comprehensive preparation and practice management tools, focusing on regulatory update cadence, multi-form coverage, and workflow integration. Smaller but focused providers, including Drake Software, TaxAct, TaxSlayer, On-Line Taxes, CFS Tax Software, and Advanced Tax Solutions, differentiate through niche functionality, pricing clarity, or specialized professional workflows.
Accounting Software Market
Strategic differentiation is increasingly defined by three dimensions: compliance reliability, user experience, and ecosystem fit. Leading vendors invest heavily in maintaining approved e-filing status, delivering timely updates aligned with tax law changes, and providing error validation that reduces rework. Equally important is the design of preparation workflows, including guided prompts, document capture, and transcript integration that lower the skill threshold for complex filings. Finally, ecosystem fit matters as firms evaluate how well a platform aligns with existing practice management, client communication, and data storage preferences. Vendors that excel across all three dimensions tend to retain multi-year loyalty, while laggards face churn when competitors demonstrate faster update cycles or smoother user journeys.
The competitive landscape is evolving through both consolidation and fragmentation. Larger platforms are expanding their feature sets to serve adjacent user segments, blurring the line between individual and professional tools. At the same time, specialized providers continue to carve out defensible positions by focusing on specific form sets, regional compliance requirements, or price-sensitive professional markets. New entrants face a steep climb given the importance of approval status, historical data accumulation, and trusted update cycles, but they can gain traction by targeting underserved workflows, offering transparent pricing, or delivering superior onboarding experiences. Overall, the market is moving toward a bifurcated structure in which broad-platform leaders compete on scale and integration while focused providers compete on specificity and cost clarity.
PW Consulting
Future Trends and Commercial Opportunities
Looking ahead to the next three to five years, three trends are likely to determine where value concentrates and how competitive advantage is built.
Trend One: Compliance-as-a-Service and Continuous Update Models
Regulatory change will continue to accelerate, and the ability to deliver reliable, audited updates will become a core commercial asset. Platforms that institutionalize continuous compliance monitoring, automated test suites, and rapid deployment pipelines will reduce the risk of filing rejections and user friction. This trend creates opportunities for vendors to monetize update assurance, compliance documentation, and proactive regulatory alerts as part of premium service tiers. For buyers, the commercial implication is clearer visibility into total compliance risk and a stronger basis for vendor selection based on update reliability rather than feature count alone.
Trend Two: Guided Experiences and Tiered Offerings
User expectations will keep shifting toward guided, low-friction preparation, particularly among individuals and small business owners who value speed and certainty. Tiered pricing models will likely deepen, with no-cost or low-cost guided pathways for eligible users coexisting alongside premium advisory and comprehensive preparation features. Vendors that design seamless handoffs between free, guided, and professional-grade workflows can expand reach while preserving margin through upsell into data continuity, multi-state filing, and practice-oriented tools. The strategic opportunity lies in using guided experiences as an entry point that builds trust and historical data retention, then converting that engagement into recurring, higher-value relationships.
Worldwide Tax & Revenue Collection Software Market
Trend Three: Integration with Broader Financial Workflows
Tax preparation is increasingly viewed as one node within a larger financial operations workflow. Connections to accounting data, bank and payment records, payroll information, and document storage reduce duplicate entry and improve accuracy. Platforms that enable secure data exchange, standardized imports, and role-based collaboration will capture additional stickiness and reduce seasonal onboarding costs. This trend opens commercial pathways for vendors to position tax software as part of a year-round financial toolkit, rather than a seasonal utility, potentially expanding cross-sell opportunities and lengthening the customer lifecycle.
These trends carry inherent uncertainties. Regulatory decisions can alter filing requirements or reimbursement structures, shifting demand patterns unexpectedly. Rapid update cycles can strain support resources if error validation or form coverage is incomplete. Pricing pressure from free or low-cost guided options may compress margins in volume-driven segments. And integration ambitions can collide with data privacy expectations and interoperability constraints. Organizations that monitor these variables closely and maintain flexible product roadmaps will be better equipped to pivot as conditions evolve.
Strategic Actions for Decision Makers
The following recommendations are intended to help different stakeholder groups translate market dynamics into practical actions.
For Software Vendors and Product Leaders
Prioritize update reliability and compliance assurance as foundational differentiators. Invest in automated testing, transparent release notes, and rapid remediation processes to reduce filing rejections and user friction. Simultaneously, refine user journeys to lower the cognitive burden of complex forms, and design tiered offerings that preserve accessibility while creating clear paths to premium features. Evaluate integration points with accounting, document management, and client communication tools to strengthen year-round relevance and reduce seasonal switching risk.
For Investors and Strategic Allocators
Focus due diligence on vendors with durable update cycles, approved filing status, and evidence of user retention beyond a single season. Assess whether a company's pricing model aligns with the cost sensitivities of its target segment, and whether its roadmap anticipates regulatory complexity rather than reacting to it. Favor platforms demonstrating clear product-led growth signals, such as multi-year data continuity, expanding form coverage, and measurable time savings for professional preparers. Monitor consolidation potential among specialized providers whose workflows could be absorbed into broader platforms.
For Procurement Teams and Practice Owners
Evaluate tax software based on total compliance risk, update cadence, and workflow fit rather than headline pricing alone. Ask vendors how they validate form changes, how quickly updates reach users, and how error feedback is delivered during filing windows. Consider the long-term value of data portability, role-based access, and integration with existing practice tools. Where eligible, explore guided filing options to reduce preparation time for straightforward returns, while reserving professional-grade platforms for complex cases that require multi-state coverage, entity-level filings, or advisory extensions.
Market conditions in tax software are being reshaped by the intersection of regulatory modernization, cloud adoption, and rising user expectations. The organizations that thrive will be those that treat compliance reliability as a product foundation, design for sustained user engagement, and position their offerings within broader financial workflows. Detailed segmentation data, vendor scorecards, regional demand patterns, and customized strategic recommendations are available in the full research report, which provides the granular evidence base needed to support planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Tax Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


