



Soy Sauce Market Beyond the 5.4% CAGR: Strategic Shifts Reshaping Asia Pacific Dynamics

The Strategic Soy Sauce Market: Navigating the Next Wave of Growth
The global condiments sector has long relied on soy sauce as a foundational ingredient, but the current market trajectory suggests a more sophisticated evolution than simple volume expansion. As the industry moves through a period of steady revenue growth and shifting consumption patterns, strategic decision-makers must look beyond headline numbers to understand the structural forces reshaping supply chains, competitive positioning, and consumer expectations. The market has demonstrated consistent momentum over the past half-decade, with revenue figures climbing steadily and a projected compound annual growth rate signaling continued expansion through the early 2030s. Yet this growth masks underlying complexities that demand careful navigation.
From a macro perspective, the industry has transitioned from a mature, regionally concentrated category into a more globally integrated space where premiumization, geographic diversification, and operational scale intersect. Total market revenue has grown from the high twenty-nines billion range in 2020 to surpass the forty-one billion mark by 2025, and forward projections indicate continued upward movement, with the market expected to approach the sixty-billion threshold by 2032. This trajectory reflects more than population growth or basic culinary adoption; it points to a category gaining relevance in modern food preparation, ethnic cuisine globalization, and industrial food formulation. For executives and investors, the headline growth rate of approximately 5.4 percent annually provides a useful baseline, but the real strategic value lies in understanding where growth concentrates, what threatens it, and how incumbents are adapting.
Several structural tensions currently define the industry's inflection point. First, the sector operates within a moderately concentrated environment where a limited number of large producers command meaningful share, yet smaller specialty manufacturers continue to carve out profitable niches through authenticity, craftsmanship, and geographic specificity. This coexistence of scale and specialization creates both competitive friction and partnership opportunities. Second, raw material cost dynamics introduce volatility that can compress margins or force pricing strategies that risk alienating price-sensitive buyers. Third, regulatory divergence across key markets means that compliance requirements, labeling rules, and ingredient transparency expectations differ sharply depending on where a product is manufactured, distributed, or consumed. These three forces, market concentration, input cost variability, and regulatory asymmetry, form the backdrop against which strategic choices must be made.
Understanding the Market Landscape and Its Pressures
The global soy sauce market has matured into a multi-regional industry where cultural familiarity, foodservice integration, and retail convenience collectively drive demand. Asia Pacific remains the dominant revenue contributor, reflecting both deep culinary tradition and large population bases, but growth is increasingly visible in regions where Asian cuisine adoption continues to expand among mainstream consumers. The category is no longer confined to traditional home cooking; it now flows through packaged food manufacturing, restaurant operations, and cross-cultural food experimentation. This broader application footprint has helped stabilize demand even as certain mature markets face slower household penetration growth.
Three challenges stand out as particularly consequential for strategic planning:
Soy Milk Market
- Margin pressure from input cost volatility: Soybeans and fermentation inputs are subject to agricultural cycles, weather disruptions, and commodity trading dynamics. When harvest forecasts shift or trade flows adjust, producers must decide whether to absorb cost increases, renegotiate supplier agreements, or pass changes through to customers, each path carrying commercial risk.
- Regulatory fragmentation: Labeling, nutritional disclosure, and ingredient transparency rules vary across jurisdictions. A product positioned for global distribution must comply with differing standards on GMO disclosure, nutritional labeling, and processing classifications, which can complicate packaging, marketing, and market-entry sequencing.
- Competitive differentiation in a crowded category: Traditional large-scale brewing, accelerated production methods, and artisanal fermentation all compete for shelf space and foodservice contracts. Consumers and professional buyers increasingly evaluate flavor complexity, sodium content, authenticity claims, and sourcing ethics, raising the bar for what constitutes competitive advantage.
These challenges are not insurmountable, but they do require a more deliberate approach to product architecture, supply chain resilience, and geographic prioritization. Companies that treat the category as a single homogeneous proposition risk missing the opportunities hidden in regional taste preferences, application-specific formulations, and regulatory arbitrage where compliant positioning can become a market-access advantage.
Core Drivers Shaping the Next Growth Cycle
The market's forward momentum is not accidental; it is being propelled by a combination of technological advancement, shifting consumer behavior, supply-side restructuring, and evolving regulatory frameworks. Each driver interacts with the others, creating a landscape where advantages compound for organizations that align product strategy with operational readiness.
Innovation in Production and Product Architecture
Fermentation science and process control have progressed beyond the traditional binaries of naturally brewed versus chemically accelerated production. Modern manufacturers are investing in controlled fermentation environments, strain selection, and analytical quality systems that improve consistency while preserving the flavor profiles consumers associate with authenticity. At the same time, product architecture has expanded to include reduced-sodium formulations, cleaner-label variants, and flavor-specialized offerings tailored to specific culinary applications. This innovation is not merely technical; it is commercial. Producers that can deliver consistent taste, adaptable viscosity, and stable shelf performance gain advantages in both retail and industrial food service settings.
Regulatory Divergence as a Strategic Variable
Regulatory environments are not moving in unison, and this divergence has become a meaningful factor in market strategy. In some markets, soy sauce benefits from exemptions or lighter labeling burdens, while in others, GMO disclosure, nutritional labeling, or deeply processed product classification introduces additional compliance steps. These differences shape where companies choose to launch first, how they design packaging, and which ingredient claims they can safely make. For global players, the capability to modularize compliance by region, rather than treating labeling as a single global template, can reduce time-to-market friction and avoid costly reformulation cycles. For smaller brands, understanding regulatory thresholds early can determine whether a product can scale internationally or remains regionally constrained.
Demand-Side Shifts Toward Authenticity and Application Versatility
Consumer and buyer behavior continues to tilt toward products that signal authenticity, craftsmanship, and culinary specificity. This does not mean every segment seeks premium pricing; rather, it means that trust, origin narrative, and flavor reliability increasingly influence purchase decisions. At the same time, foodservice operators and packaged food manufacturers demand ingredients that perform consistently across large batches and varied recipes. The dual demand for artisanal credibility and industrial reliability pushes manufacturers to build portfolios that serve both ends of the spectrum. Brands that can articulate a clear position, whether as a heritage fermented product or a dependable industrial ingredient, are better placed to secure shelf space, contract stability, and repeat procurement.
Pasta Sauce Market
Supply Chain and Cost Structure Realignment
Soy sauce production depends on soybean supply, brewing infrastructure, logistics, and regional labor and energy costs. Agricultural price forecasts for the coming marketing years point to higher season-average soybean prices compared with the prior year, which signals potential cost pressure for upstream inputs. This does not automatically translate into market-wide margin erosion, but it does reward organizations that secure forward contracts, diversify sourcing, and optimize plant utilization. Companies with geographically distributed production footprints can shift volume among facilities, hedge against localized disruptions, and respond more flexibly to currency or logistics shocks. In practical terms, supply chain resilience is becoming a competitive differentiator rather than a back-office function.
Competitive Dynamics and Strategic Positioning
The industry's competitive field is shaped by a mix of long-established brewing specialists, large regional manufacturers, and smaller innovators pursuing distinctive flavor profiles or niche market positions. The largest producers combine scale, export capability, and multi-plant infrastructure, while others compete through premium positioning, regional brand equity, or specialized product development. This structure supports a market where share is contestable but not easily overturned, because scale advantages in brewing capacity, distribution relationships, and ingredient procurement are difficult to replicate quickly.
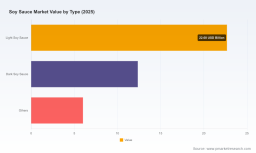
Several strategic postures are visible across the leading set. One is geographic expansion through local production, which reduces shipping costs, shortens lead times, and signals commitment to a market. A second is premiumization through naturally brewed positioning and taste differentiation, which targets consumers and foodservice buyers willing to pay for perceived quality and culinary authenticity. A third is portfolio breadth across light, dark, and specialty variants, allowing a manufacturer to serve multiple culinary applications and capture demand across different cooking traditions. A fourth is innovation in small-batch, distinctive flavor profiles that can command premium pricing and build loyal following among chefs, specialty retailers, and consumer enthusiasts.
Recent operational developments illustrate how these strategies are playing out in practice. A major Japanese producer with significant U.S. manufacturing presence has been progressing a new American production facility, with first shipments anticipated in the fall of 2026 after groundwork laid in 2024. This kind of investment signals confidence in sustained demand and a desire to deepen local supply capability rather than relying solely on export flows. Meanwhile, in the Chinese market context, leading domestic brands have continued to showcase light, dark, and standard varieties through major trade platforms, reinforcing the importance of category breadth and export visibility for manufacturers seeking broader international reach.
Market structure appears likely to evolve along two parallel paths. Consolidation pressure will persist where scale economics, distribution leverage, and sourcing advantages favor larger operators, especially in price-competitive segments and high-volume foodservice channels. At the same time, fragmentation will remain viable in premium, regional, and specialty segments where authenticity, craft narrative, and differentiated flavor profiles create defensible positions. New entrants that can combine a clear brand story with disciplined production quality, or that can serve an underserved application such as a specific culinary format or a clean-label requirement, can still gain traction without directly challenging the largest incumbents on volume alone.
Forward-Looking Trends for the 2026 to 2032 Window
Looking ahead, several trends are likely to shape how growth is captured and where value accrues. These trends are grounded in current market data, recent operational moves, and the regulatory and demand environment already in motion.
PW Consulting
Local Production and Regional Capacity Expansion
As demand broadens beyond traditional strongholds, the economics of long-distance export versus local manufacturing become more consequential. Additional production capacity in key markets can improve responsiveness, reduce logistics exposure, and support labeling or formulation adaptation to regional requirements. Over the next several years, more manufacturers are likely to evaluate where to place capacity based on demand density, input availability, and regulatory clarity. The strategic implication is that presence in a market will increasingly be judged not just by brand recognition but by supply reliability and local compliance readiness.
Premiumization Paired with Functional Positioning
Premium products will continue to grow in relevance, but premiumization alone will not define success. The most durable growth will likely come from products that combine authentic fermentation or distinctive flavor with practical benefits such as lower sodium, cleaner ingredient lists, or application-specific performance. This pairing allows manufacturers to address both consumer-facing premium demand and buyer-facing formulation needs. Brands that can communicate flavor quality while meeting functional expectations will have a stronger chance of commanding price resilience and repeat usage.
Regulatory Clarity as a Market Access Multiplier
Because regulatory requirements differ across markets, companies that proactively align product design and labeling with local rules can turn compliance into a market-entry advantage. In regions where nutritional labeling is not required, simpler packaging and broader claim flexibility may be available; in regions with stricter disclosure, early adaptation can prevent reformulation delays and protect brand consistency. Over time, the ability to navigate multiple regulatory regimes efficiently will become part of the competitive baseline for companies pursuing international distribution.
These trends carry uncertainty. Cost volatility in soybean supply could compress margins for producers with less flexible sourcing or pricing strategies. Regulatory changes could shift faster than anticipated in some markets, altering labeling obligations or ingredient disclosure expectations. Consumer taste preferences may evolve toward lower-sodium or plant-forward alternatives, requiring manufacturers to innovate without diluting the category's core identity. Each of these risks is manageable with the right data, scenario planning, and operational agility.
Strategic Actions for Decision-Makers
For manufacturers, the priority is to align product architecture with both flavor differentiation and operational resilience. That means evaluating whether portfolio breadth, premium positioning, or local production offers the best return in each target market, and ensuring that sourcing and facility strategy can absorb input cost variability without sacrificing consistency. For investors, the opportunity lies in identifying organizations that combine credible brand equity with scalable production and a clear regional expansion plan, while monitoring where margin exposure to raw material costs and regulatory complexity may create downside risk or require additional capital discipline. For procurement and foodservice buyers, the practical focus should be on supplier reliability, formulation consistency, and compliance alignment, since these factors increasingly determine whether a soy sauce supplier can support large-scale operations across multiple markets without disruption.
Access to detailed segmentation data, regional revenue splits, and granular competitive movement can sharpen each of these decisions. Broad market trajectories provide direction, but precise allocation decisions require clearer visibility into where growth concentrates, how share is shifting among product types, and which operational investments are likely to yield durable advantage. The full research report offers that level of detail, including segmented data, company-level developments, and market-access considerations that support tailored commercial planning.
The soy sauce market is entering a phase where growth is real, but competitive advantage will depend on how well organizations align innovation, compliance, and supply chain readiness with the specific markets and applications they choose to serve. Companies that treat the category as a strategic platform rather than a routine ingredient business are better positioned to convert steady industry expansion into defensible share and healthier margins.
For detailed analysis of this topic, please visit the official page: Soy Sauce Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


