



Employee Scheduling Software Market 2026: Why 11.2% CAGR Redefines Growth Strategy

The Employee Scheduling Software Market: Navigating Growth, Fragmentation, and the AI Inflection Point
The employee scheduling software market has transitioned from a tactical admin utility to a strategic operational layer that directly shapes labor costs, compliance exposure, and service continuity. Revenue across the sector expanded from approximately USD 148.5 million in 2020 to an estimated USD 225.0 million by 2025, reflecting a compound annual growth rate of 11.2% over the 2020–2025 period. Forward projections indicate the market will reach roughly USD 250.7 million in 2026 and continue expanding toward USD 367.0 million by 2032, sustained by the same structural tailwinds that drove the earlier acceleration. This trajectory signals more than incremental software adoption; it reflects a fundamental rethinking of how organizations translate demand volatility into shift coverage while controlling overtime, reducing compliance risk, and preserving employee experience.
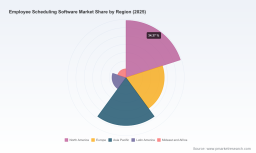
The growth curve is not uniform. Cloud-based deployment continues to dominate new implementations, while on-premises footprints are shrinking as organizations migrate toward integrated platforms that connect scheduling with payroll, time tracking, and workforce analytics. Mid-size enterprises and small businesses together account for the largest share of adoption volume, driven by the need for affordable, mobile-first tools that can scale without dedicated HRIT teams. Large enterprises are pursuing fewer but deeper deployments, prioritizing forecasting accuracy, multi-site orchestration, and integration with broader HCM ecosystems. Geography also matters: North America remains the largest revenue center, Europe follows with strong compliance-led demand, and Asia Pacific is emerging as the fastest-expanding region as service-sector digitization and flexible staffing models accelerate.
Defining the Current Inflection Points
Despite the expansion, the market sits at a series of crossroads. First, legacy schedulers that rely on static templates and manual overrides are increasingly misaligned with demand patterns characterized by seasonal spikes, last-minute absenteeism, and customer-facing fluctuations. Organizations that continue to manage shifts through spreadsheets or siloed tools face mounting labor mismatches that translate directly into overtime leakage, understaffed service windows, and scheduling friction for employees. Second, compliance complexity is intensifying. Meal-and-rest mandates, overtime thresholds, union rules, and region-specific labor regulations are proliferating, making manual enforcement error-prone and legally risky. Platforms that cannot automate policy enforcement and audit trails are losing relevance in regulated environments. Third, integration expectations are rising. Buyers now assume that a scheduling tool will connect with time and attendance, payroll, demand signals, and workforce analytics without custom middleware. Vendors that remain point solutions risk being bypassed in favor of platforms that can reduce integration debt and administrative fragmentation.
Key Drivers Reshaping the Market
Three to four forces are converging to redefine the value proposition of employee scheduling software, shifting it from convenience to operational leverage.
Technology Innovation and the AI Forecasting Shift
Artificial intelligence has moved from a feature promise to a core differentiator. Modern platforms combine historical attendance, demand signals, seasonality, and employee availability to generate shift forecasts and coverage recommendations that adjust in real time. This matters because scheduling accuracy directly affects labor cost and service quality. Organizations using AI-driven planning and real-time analytics report meaningful reductions in overstaffing and overtime, with customer-reported outcomes pointing to an average 21% decrease in labor costs. At the same time, automated shift planning paired with mobile self-service has been associated with roughly 30% higher shift coverage and 23% lower overtime costs in typical deployments. The strategic implication is clear: scheduling software is increasingly a cost-control and continuity tool, not merely a shift calendar. The vendors winning attention are those that translate forecasting into actionable coverage plans, flag compliance conflicts early, and let employees swap or pick shifts without creating coverage gaps.
Policy and Regulatory Pressure as a Catalyst for Automation
Labor regulation is no longer a static backdrop; it is becoming one of the most powerful adoption drivers. Platforms increasingly embed rules for meal breaks, rest periods, overtime limits, union requirements, and state-specific mandates so that schedule generation and adjustments automatically respect policy boundaries. This reduces legal exposure and administrative burden while giving managers a defensible scheduling process. In parallel, data privacy expectations have hardened, especially for cloud-based tools serving European and regulated markets. Maintaining GDPR and SOC 2 compliance is now table stakes for enterprise buyers, and platforms that can demonstrate consistent controls around data handling, access, and auditability enjoy a shorter sales cycle in sensitive environments. The practical outcome is that compliance automation and privacy assurance are becoming competitive moats, particularly for vendors serving multi-jurisdiction workforces.
Demand-Side Change: Frontline Work Patterns and Employee Expectations
The shape of hourly and frontline work continues to evolve. Service sectors, retail, logistics, healthcare support, and hospitality face demand that fluctuates with weather, seasons, local events, and consumer behavior. Employees, meanwhile, expect greater visibility and control over their schedules, faster shift confirmation, and simpler swap mechanisms. This dual pressure pushes organizations toward scheduling tools that are mobile-first, self-service enabled, and capable of balancing business coverage needs with employee preferences. Mobile clock-in, shift templates, real-time notifications, and team communication features are increasingly expected rather than optional. Companies that ignore the employee experience dimension tend to see higher attrition and last-minute coverage gaps, which in turn inflate labor costs and degrade service consistency.
Worldwide Field Service Software Market
Cost Structure and SaaS Economics Favoring Cloud Deployment
The cost equation favors cloud-based delivery, especially for small and mid-size organizations that lack large internal IT footprints. Subscription economics reduce upfront capital barriers, accelerate deployment, and make it easier to add locations, users, and modules as needs evolve. For larger enterprises, the cloud transition is less about affordability and more about integration and analytics. Centralized data from scheduling, time tracking, and payroll creates visibility into labor cost trends, coverage efficiency, and overtime patterns, enabling more informed workforce planning. This dynamic reinforces the dominance of cloud models in new revenue and explains why on-premises installations are increasingly limited to specialized or legacy environments with strict data residency or operational constraints.
Competitive Landscape and Leading Strategies
The market is moderately concentrated, with the top three providers holding roughly 24.6% of revenue and the top five near 26.2%. That leaves substantial room for specialization, regional strength, and segment-focused differentiation. The field spans global HCM-scale platforms, workforce-management specialists, and SMB-oriented mobile tools, each pursuing distinct strategic positions.
Strategic Positioning Among Leading Providers
ADP has built a broad workforce management footprint with ADP Workforce Now, integrating scheduling, time tracking, shift optimization, and compliance tools aimed at hourly and frontline workers. Its strength lies in scale, payroll linkage, and the ability to serve a wide range of organization sizes with a single platform. UKG has pushed enterprise-grade capabilities through UKG Pro and Kronos Workforce Central, emphasizing AI forecasting, real-time coverage planning, labor cost optimization, and multi-site shift management. The recent expansion of UKG’s integration ecosystem underscores a platform strategy: in March 2026, it introduced 15 Workforce Management APIs to streamline connections with scheduling and time-tracking platforms, reflecting a recognition that interoperability now shapes buying decisions. Ceridian Dayforce positions around a unified platform for global enterprises, combining scheduling, shift assignment, workforce analytics, and automated compliance within a single system, appealing to organizations that want consistency across regions and functions.
Rippling targets growing businesses with an integrated HR and workforce management suite that links scheduling, AI demand forecasting, shift planning, and payroll, reducing the friction of juggling separate tools. Deputy remains focused on shift-based industries with AI labor forecasting, mobile apps, and compliance automation, a model that resonates in retail, hospitality, and light industrial settings. Connecteam and Homebase emphasize SMB usability through app-based scheduling, shift swapping, mobile clock-in, labor cost tracking, and compliance alerts, competing on ease of adoption and day-to-day usability. Paychex Flex and Paycor extend mid-market reach by tying scheduling to payroll and HCM dashboards, providing labor cost visibility and shift management within broader HR processes. When I Work emphasizes employee self-scheduling and real-time reporting, a straightforward value proposition for teams that want flexibility without administrative overhead. Workday brings enterprise HCM depth with advanced scheduling, demand forecasting, and compliance-driven workforce planning for large organizations. Finally, TCP Software and Shiftboard highlight highly operational niches: automated forecasting, mobile management, fatigue management, contingent labor tools, and labor cost reduction for mission-critical environments, where coverage assurance and risk control outweigh convenience alone.
Nurse Scheduling Software Market
How the Landscape Is Evolving
Three trends are reshaping the competitive structure. Integration is becoming a default expectation rather than a differentiator, pushing vendors to offer APIs, prebuilt connectors, and data flows that tie scheduling into payroll, analytics, and demand systems. At the same time, specialization is intensifying in high-stakes segments such as healthcare support, logistics, manufacturing, and other environments where fatigue management, compliance enforcement, and contingent labor coordination carry direct operational and safety implications. A third dynamic is the steady arrival of well-funded new entrants that lean into mobile-first design, AI forecasting, and SMB affordability, expanding choice but also fragmenting attention for buyers. The net result is a market that rewards clear positioning: platforms that can demonstrate measurable coverage improvements, labor cost control, and compliance automation within a buyer’s existing technology stack are gaining traction, while undifferentiated schedulers are facing longer evaluation cycles and stricter comparison criteria.
Forward-Looking Trends and Commercial Opportunities
Looking across the next three to five years, several trends are likely to determine where value accrues and where new opportunities emerge.
AI-First Scheduling Becomes the Operational Standard
Forecasting and real-time adjustment will become embedded baseline capabilities rather than premium add-ons. As models improve with richer attendance history, demand signals, and policy constraints, organizations will expect scheduling systems to anticipate coverage gaps, recommend shift fills, and flag labor cost risks before shifts are published. The commercial opportunity lies in solutions that connect forecasting with execution: auto-suggested shifts, mobile acceptance flows, and manager dashboards that make actionable decisions fast. Vendors that can show defensible improvements in coverage and overtime—with clear measurement frameworks—will find it easier to justify expansion and renewals.
Compliance Automation as a Core Buying Criterion
The regulatory environment will continue to reward platforms that can encode rules, enforce them at schedule creation, produce audit-ready documentation, and adapt quickly to changing requirements. This is particularly relevant for multi-state, multi-jurisdiction, and unionized workforces. The opportunity for providers is to package policy guidance, rule templates, and document support as part of the workflow rather than as separate services. Organizations that treat compliance automation as a design principle—rather than a retroactive fix—will reduce legal exposure and administrative effort while strengthening employee trust in the scheduling process.
Integration Ecosystems and Workforce Data Platforms
The future value chain is increasingly interoperable. Scheduling will connect more tightly with time and attendance, payroll, labor analytics, and demand planning, creating a more complete view of workforce costs and coverage. Buyers will favor solutions that minimize custom integration work and enable data to move cleanly between functions. This opens opportunities for platforms that act as orchestration layers, standardize data models, and provide APIs that accelerate deployments and reduce total cost of ownership. For enterprises, the prize is workforce visibility that supports planning beyond individual shifts: staffing models, labor budgets, and service-level commitments aligned with realistic demand.
These trends carry uncertainty. AI adoption depends on data quality and change management; inaccurate inputs or poorly governed models can erode trust and limit realized savings. Compliance expectations can shift quickly, requiring vendors and buyers alike to keep pace with new rules and interpretations. Integration depth can also become a double-edged sword: over-engineaging ecosystems may complicate deployments, while under-integrated tools may fail to meet enterprise expectations. Finally, pricing pressure is likely to intensify as more competitors offer AI features at competitive price points, making it essential for providers to differentiate on outcomes, not just feature lists.
Strategic Actions for Decision-Makers
The market’s direction suggests several practical moves, tailored to different roles in the value chain.
PW Consulting Information & Electronics Research Center
-
For enterprise and mid-market buyers evaluating scheduling software: prioritize platforms that link scheduling with payroll and time tracking, enforce compliance rules automatically, and provide measurable coverage and labor-cost outcomes. Run pilots that test forecasting accuracy under real demand variability, not just idealized scenarios. Confirm that the solution supports mobile self-service, shift swaps, and rapid manager overrides without creating policy violations. Assess integration effort early, because hidden middleware and data cleanup can turn a low-cost tool into a high-friction deployment.
-
For investors and strategic partners: focus on providers with credible AI forecasting, strong compliance automation, and clear integration roadmaps, especially those demonstrating repeatable labor-cost reductions and coverage improvements in target verticals. The highest-conviction opportunities are likely in platforms that can serve shift-based and mission-critical environments at scale while maintaining data-privacy assurance for regulated markets. Watch for consolidation signals, since interoperability demands and integration fatigue may drive buyers toward platforms that can unify functions and reduce vendor count.
- For vendors and product leaders: invest in measurable outcome claims, not just feature breadth. Make compliance automation, auditability, and privacy controls visible and easy to validate. Build integration pathways that reduce deployment time and data fragmentation, and design mobile self-service experiences that improve employee adoption while protecting coverage integrity. Differentiation will increasingly come from how well a platform reduces overtime leakage, improves shift coverage, and keeps schedules within policy boundaries without adding manager workload.
The employee scheduling software market is moving from incremental digitization to a more outcome-driven phase in which forecasting accuracy, compliance automation, and integration maturity determine competitive strength. For organizations navigating shifting labor patterns and rising regulatory complexity, the question is no longer whether to adopt scheduling software, but which platform can convert schedule planning into lower labor costs, fewer compliance risks, and more reliable coverage. Detailed segmentation data, vendor-by-vendor benchmarks, and customized adoption roadmaps can sharpen those decisions further; PW Consulting’s full research report provides that deeper breakdown for teams preparing investment, procurement, or product strategy choices in this space.
For detailed analysis of this topic, please visit the official page: Employee Scheduling Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


