



Beyond 4.5% CAGR: The Real Drivers Reshaping the Contact Lens Solution Market

Navigating the Contact Lens Solution Market: Strategic Trends and Commercial Opportunities (2026–2032)
The contact lens solution market is entering a phase of measured but meaningful transformation. Valued at approximately USD 2,200.0 million in 2025, the sector has expanded steadily from USD 1,850.0 million in 2020, reflecting a compound annual growth rate of 4.5% across the 2026–2032 forecast period. By 2032, revenue is projected to reach USD 2,900.0 million. This trajectory signals a market that has moved past early adoption cycles and is now shaped by formulation innovation, regulatory discipline, and shifting consumer expectations around lens care. For executives and investors, the opportunity lies not in chasing volume alone, but in aligning product portfolios, supply chain resilience, and go-to-market strategies with structural shifts that will redefine competitive advantage over the next five years.
Market Landscape and Core Challenges
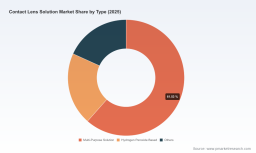
The market remains concentrated, with the top three players accounting for roughly 65% of revenue and the top five capturing about 75%. This concentration underscores the importance of scale, distribution network strength, and regulatory readiness, but it also masks underlying segmentation dynamics that are reshaping value creation. Multi-purpose solutions continue to anchor the category, while hydrogen peroxide-based systems and specialized formulations carve out meaningful niches for users seeking deeper cleaning, sensitivity management, or compatibility with advanced lens materials. Demand is distributed across rinsing, cleaning, and disinfecting applications, with disinfection representing the largest share of end-use value, reflecting consumer emphasis on eye health and hygiene.
Despite steady growth, the sector faces several structural pressure points that will determine which companies capture disproportionate share:
Worldwide Contact Lenses Cleaner Boxes Market
- Regulatory complexity and formulation change management. Contact lens solutions are classified as Class II medical devices in major markets, requiring 510(k) clearance pathways, sterility validation aligned with recognized pharmacopeial standards, and compliance with tamper-resistant packaging and labeling expectations. Any significant change to formulation, packaging, or manufacturing process can trigger updated submissions, increasing time-to-market and cost for iterative innovation.
- Raw material and preservation trade-offs. Formulations must balance preservatives, wetting agents, disinfectants, and humectants to maintain sterility, lens compatibility, and wearer comfort. Cost volatility in specialty ingredients, combined with sensitivity toward preservative exposure, pushes manufacturers to refine formulations without compromising performance or shelf stability.
- Consumer behavior and reimbursement nuance. Purchasing patterns are increasingly influenced by out-of-pocket convenience, health account eligibility, and the broader shift toward daily disposables. While solutions remain eligible for reimbursement through health flexible spending arrangements in many contexts, the growth of single-use lenses can dampen recurring solution consumption in certain segments, requiring companies to reposition value around comfort, eye health, and lens longevity rather than volume alone.
For decision-makers, the strategic implication is clear: growth will increasingly come from differentiation in formulation, patient experience, and compliance-friendly packaging, rather than from broad-based price competition. Companies that treat regulatory and formulation constraints as design parameters—rather than afterthoughts—will be better positioned to scale new variants and defend margins.
Key Drivers of Market Change
Technological Innovation and Formulation Evolution
Innovation in lens care is moving toward systems that reconcile disinfection efficacy with comfort and material compatibility. Hydrogen peroxide-based platforms have gained traction among users seeking thorough cleaning and reduced preservative exposure, especially for sensitive eyes or extended wear routines. At the same time, multi-purpose solutions continue to evolve with improved wetting agents, protein management, and hydration technologies that support all-day comfort across soft and rigid lens types. The broader lens ecosystem is also influencing solution design: as lens manufacturers introduce advanced optics and material architectures—such as daily disposable lenses incorporating extended depth of focus optics—solution providers must ensure compatibility, stability, and cleaning performance across a widening range of materials and use cases.
The commercial impact is twofold. First, formulation leadership can justify premium positioning when it delivers measurable benefits in comfort, cleanliness, or sensitivity management. Second, compatibility with next-generation lenses creates switching costs and partnership opportunities, as eye care professionals and consumers seek care regimens that preserve lens performance over time.
Contact Lenses Market
Regulatory and Reimbursement Environment
Regulatory discipline remains a central driver of market structure. Because solutions are Class II devices, manufacturers must navigate clearance requirements, sterility testing expectations, and packaging/labeling standards that are designed to protect end users from contamination and misuse. The requirement to discard solution after each use—and the clinical guidance against reusing leftover product—reinforces safety but also shapes consumption patterns and consumer education needs. Any significant design or formulation change can necessitate updated regulatory notifications, which makes portfolio agility dependent on robust quality systems and proactive regulatory planning.
On the demand side, reimbursement mechanics through health flexible spending accounts add a layer of consumer convenience that can influence trial, repeat purchase, and basket size. However, reimbursement is not uniform across jurisdictions or plan types, so commercial teams should treat eligibility as an enabler rather than a baseline assumption. Brands that make safe use, proper disposal, and value articulation explicit in their messaging can convert regulatory and reimbursement realities into trust and repeat usage.
Demand-Side Shifts in Consumer and Professional Behavior
Consumer expectations are increasingly shaped by comfort, eye health, and convenience. Wearers are more informed about lens care hygiene, more sensitive to preservative exposure, and more likely to compare solutions based on feel, compatibility, and ease of use. Professional channels remain influential: eye care practitioners guide recommendations based on lens type, wear schedule, and patient sensitivity, making clinical endorsement a powerful lever for adoption. At the same time, the expansion of daily disposable lenses in certain demographics introduces a strategic counterweight, as some users reduce reliance on reusable lens care products.
This creates a nuanced demand environment. Growth is not simply a function of more wearers; it is a function of which care regimens professionals recommend, which formulations consumers trust, and how effectively brands communicate hygiene and compatibility benefits. Companies that invest in practitioner education, consumer-facing safety messaging, and product experiences that reduce misuse will be better equipped to sustain share even as lens formats evolve.
Supply Chain and Cost Structure Dynamics
The cost structure of contact lens solutions is influenced by specialty ingredients, sterilization and quality control requirements, and packaging integrity. Preservatives, wetting agents, disinfectants, and humectants must be sourced and blended to consistent specifications, while packaging must support tamper resistance and clear labeling. Fluctuations in raw material availability, energy costs, and logistics can pressure margins, particularly for lower-volume or highly specialized variants.
PW Consulting
Resilience is becoming a competitive differentiator. Manufacturers that diversify supplier bases, standardize core formulation platforms to enable efficient scale, and invest in packaging designs that balance safety with cost will be more capable of protecting margins during input cost swings. In addition, businesses that align production flexibility with regional demand patterns can respond more effectively to localized growth without overcommitting capacity.
Competitive Landscape and Leading Strategies
The market is anchored by a mix of large, globally scaled players and specialized manufacturers that compete on formulation depth, material compatibility, and channel relationships. Large incumbents leverage broad distribution, established practitioner trust, and multi-platform portfolios that span multi-purpose and peroxide systems. Their strategic advantage lies in the ability to cross-sell across lens types, sustain brand recognition, and absorb regulatory and quality system investments that smaller entrants may find harder to match.
Specialized firms compete by focusing on underserved needs: preservative-free or peroxide-based options for sensitive eyes, solutions tailored to rigid gas permeable and scleral lenses, and formulations optimized for silicone hydrogel compatibility. These players often win on clinical specificity and practitioner recommendation, building loyalty in niches where fit, comfort, and lens material compatibility matter more than broad brand familiarity. The presence of innovative manufacturers from diverse geographies also introduces fresh formulation ideas and regional go-to-market expertise, intensifying competition in both mature and faster-growing markets.
Several strategic patterns are emerging among leading participants:
- Portfolio architecture that pairs scale with specialization. Leading companies maintain broad multi-purpose franchises while expanding targeted peroxide or sensitivity-focused variants to capture adjacent demand without diluting core brand equity.
- Compatibility and lens ecosystem alignment. As lens materials and optics advance, solution providers that validate performance across silicone hydrogel, rigid, and hybrid formats create practical reasons for professionals to recommend their products, reinforcing repeat usage.
- Safety and compliance as a brand asset. Packaging, labeling, and usage messaging that make proper handling and disposal simple can reduce contamination risk and build trust, turning regulatory requirements into differentiation rather than burden.
- Regional execution with global standards. Companies are balancing standardized quality and formulation platforms with localized distribution and education efforts, allowing them to scale efficiently while adapting to regional prescribing habits and channel dynamics.
The competitive landscape is likely to evolve through a combination of consolidation among scaled players seeking portfolio breadth and incremental entry by specialized firms targeting high-value niches. Merger activity, if it occurs, will probably be driven by the desire to combine distribution reach with formulation expertise or to secure access to specific lens care platforms. At the same time, new entrants will need to clear regulatory hurdles, demonstrate compatibility with contemporary lenses, and establish practitioner trust—barriers that favor disciplined, evidence-led positioning over aggressive price-based launches.
Future Trends and Commercial Implications (2026–2032)
Looking ahead, three trends are likely to shape the market’s next phase and create tangible commercial opportunities.
Trend 1: Formulation-led differentiation will increasingly determine share
As volume growth normalizes, competitive wins will come from formulations that deliver clear, perceptible benefits—enhanced comfort, improved protein and deposit management, reduced sensitivity risk, or stronger compatibility with advanced lens materials. Brands that can document performance and communicate it credibly to both practitioners and consumers will be positioned to command better shelf placement, repeat usage, and resilience against private-label pressure.
Commercial opportunity: Invest in variant architectures that extend core platforms into high-value use cases, and build evidence and education programs that translate formulation advantages into recommendation and repurchase.
Trend 2: Integration with the broader lens ecosystem will matter more
The link between lens design and care regimen is tightening. As lens manufacturers introduce new materials and optical designs, solution providers that ensure compatibility and co-develop care protocols can deepen their relevance in professional channels. This ecosystem alignment can also create bundled value propositions, where lens and care choices are optimized together for comfort, hygiene, and lens longevity.
Commercial opportunity: Pursue compatibility validation, practitioner co-education, and channel partnerships that position solution products as integral to lens performance rather than as incidental consumables.
Trend 3: Safety, compliance, and consumer education will become growth levers
Because misuse and reuse can undermine safety and trust, brands that make correct handling, single-use discipline, and disposal easy to understand can reduce risk while reinforcing product credibility. Packaging clarity, labeling precision, and targeted education will increasingly separate reliable performers from commoditized alternatives. Regulatory requirements will continue to raise the floor on quality and safety, but the upside will accrue to brands that treat these requirements as a foundation for consumer confidence.
Commercial opportunity: Design packaging and messaging that reduce misuse, support sterility expectations, and make health-account eligibility or purchase convenience explicit where applicable, thereby improving trial and repeat behavior.
Potential risks and uncertainties should be factored into planning. Input cost volatility and supplier concentration can compress margins if not managed with diversified sourcing and platform efficiency. Regulatory changes or more stringent post-market expectations could lengthen update cycles for formulations and packaging. The continued expansion of daily disposables in select segments may shift consumption patterns away from reusable care products in some geographies, requiring portfolio rebalancing. Finally, reimbursement nuances and regional plan differences mean that demand elasticity will vary, so forecasting should be localized rather than assumed uniform.
Strategic Actions for Decision-Makers
Different stakeholders face distinct priorities, but all can benefit from a disciplined focus on formulation value, ecosystem alignment, and operational resilience.
For Manufacturers and Brand Leaders
- Prioritize platform-based innovation. Build a small number of robust formulation platforms that can be extended into multi-purpose, peroxide, and sensitivity-focused variants, preserving scale while enabling targeted differentiation.
- Strengthen compatibility and evidence. Validate performance across contemporary lens materials and optics, and equip practitioner channels with clear, credible information that supports recommendation and repeat use.
- Treat compliance as design input. Embed tamper-resistant packaging, clear labeling, and single-use discipline into product experience from the outset, reducing misuse risk and reinforcing trust.
For Investors and Strategic Partners
- Assess differentiation quality, not just scale. Evaluate whether potential targets have defensible formulation advantages, compatibility claims, and practitioner relationships that can sustain pricing power beyond volume growth.
- Watch portfolio fit and regulatory readiness. In consolidation scenarios, prioritize combinations that add genuine platform or niche capability without creating overlapping, low-margin clutter, and confirm that quality systems can support iterative updates efficiently.
- Monitor demand shifts by lens format. Track daily disposable adoption and reusable lens trends at a regional level, since consumption patterns and solution attach rates will diverge across markets and consumer segments.
For Procurement and Channel Decision-Makers
- Evaluate total value, not unit price alone. Consider formulation reliability, compatibility with the lenses you prescribe or stock, packaging integrity, and educational support when selecting care products, since these factors influence patient outcomes and repeat purchase behavior.
- Align sourcing with local demand and compliance expectations. Favor suppliers that can demonstrate consistent quality, clear usage guidance, and responsiveness to regional regulatory and reimbursement conditions.
- Use education to drive correct usage. Provide consumers and patients with straightforward instructions on single-use discipline and safe handling, reducing contamination risk and protecting brand and channel reputation.
The contact lens solution market is not undergoing a sudden disruption; it is evolving through a series of compounding shifts in formulation, regulation, lens technology, and consumer expectations. That evolution rewards companies that can combine scientific rigor with clear value communication, and that treat compliance and compatibility as strategic assets rather than operational constraints. The most resilient strategies will be those that connect product design to real-world use, align with professional recommendation pathways, and remain flexible enough to adapt as lens formats and regional demand patterns continue to change.
For leaders seeking to move from directional understanding to precise execution, a deeper view of segment-level dynamics, regional demand patterns, and company-specific positioning can sharpen prioritization and reduce uncertainty. Detailed segmentation data, competitive benchmarks, and tailored scenario analysis are available in the full PW Consulting report on the contact lens solution market, where the underlying splits and forward-looking assumptions are unpacked for decision-ready use.
For detailed analysis of this topic, please visit the official page: Contact Lens Solution Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


