



PhotoMOS Optically Isolated Relay Market: Why 7.5% CAGR Through 2032 Changes Everything

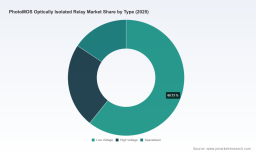
Navigating the PhotoMOS Optically Isolated Relay Market: Strategic Trends and Commercial Opportunities
Market Landscape and Defining Challenges
The PhotoMOS optically isolated relay sector has demonstrated consistent expansion over the past five years, with total market revenue climbing from approximately $320 million in 2020 to an estimated $463.5 million by 2025. The forward trajectory points toward sustained growth, with projections indicating a rise to roughly $766 million by 2032, translating to a compound annual growth rate of 7.5 percent. This expansion reflects the technology’s entrenched role in signal and power switching where galvanic isolation, low leakage, and high-frequency performance are non-negotiable. Unlike electromechanical counterparts, optically isolated MOSFET relays eliminate moving parts, reduce contact wear, and enable faster switching cycles, making them increasingly attractive in environments where reliability and footprint constraints dominate design decisions.
Despite the favorable growth trajectory, the industry is navigating a series of structural pressures that are reshaping how value is created and captured. First, raw material dynamics have tightened margins across the supply chain. Substrate costs tied to gallium arsenide and silicon-based components rose sharply in 2024, contributing to a measurable increase in manufacturing complexity. Energy and labor expenses in the sector followed a similar upward path, compounding the challenge for producers operating on thin conversion economics. Second, the competitive field remains moderately concentrated, with the top three players commanding roughly half of total revenue and the top five firms accounting for approximately 65 percent. This concentration provides scale advantages to established players but leaves smaller manufacturers exposed to pricing pressure and input volatility, with nearly 30 percent of smaller producers reporting direct exposure to component cost fluctuations.
A third challenge lies in application-specific qualification and thermal ruggedization. Automotive and high-temperature industrial deployments increasingly demand devices that can operate reliably at elevated temperatures without compromising isolation integrity or switching consistency. Meeting these thresholds requires tighter process control, advanced packaging, and more rigorous validation cycles, which in turn extend time-to-market and raise development costs. Together, these dynamics create a market that is growing steadily but not uniformly; profitability and competitive positioning now depend on how well firms can absorb input cost variability, accelerate qualified product introductions, and align portfolio breadth with high-growth application pockets.
Key Drivers Shaping the Market
Technological Innovation and Performance Breakthroughs
The core appeal of PhotoMOS relays continues to be refined through device-level engineering. Recent product iterations emphasize lower on-resistance variability, reduced leakage under idle conditions, and packaging formats that support higher power density without sacrificing isolation margins. Optical semiconductor architectures that combine LED inputs, photodiode detection arrays, and MOSFET outputs have matured to the point where non-contact switching can rival or surpass electromechanical performance in many signal and power routing tasks. These improvements matter commercially because they allow designers to replace multiple discrete components with a single isolated switching element, simplifying board layouts, reducing assembly complexity, and improving long-term reliability in cycling applications.
A concrete example of this trajectory is the introduction of voltage-driven photorelays in compact package formats with elevated temperature ratings. Newly launched devices targeting semiconductor testers, electric vehicles, and high-temperature industrial equipment demonstrate how manufacturers are pushing the envelope on thermal endurance and form factor simultaneously. By shipping voltage-driven models rated for operation at 135°C in small S-VSON4T packages, suppliers are directly addressing the qualification needs of automotive and heavy-duty industrial users who must maintain performance under harsher thermal cycles. The immediate start of volume shipments signals that these enhanced specifications are moving from prototype interest to production demand.
Policy and Regulatory Environment
Regulatory expectations around safety isolation, electromagnetic compatibility, and automotive qualification frameworks continue to shape product roadmaps. Markets that serve medical devices, automotive systems, and telecommunications infrastructure are governed by standards that reward demonstrateable isolation reliability, temperature stability, and long-term drift characteristics. In practice, this means that a relay’s datasheet performance is only part of the commercial equation; documented qualification pathways, traceability, and certifiable manufacturing processes increasingly influence procurement decisions. The regulatory tilt favors suppliers that can provide not only performance metrics but also the documentation and process consistency that downstream integrators require to clear their own validation hurdles.
PW Consulting Information & Electronics Research Center
At the same time, energy efficiency expectations in industrial automation and telecom equipment are nudging designers toward solutions that minimize standby losses and reduce wasted power in switching nodes. Optically isolated relays with stable on-resistance and low leakage align well with these efficiency goals, creating a policy-adjacent tailwind that reinforces demand beyond pure performance considerations.
Demand-Side Shifts Across End Use Segments
Demand patterns are being reshaped by the electrification and automation of core industrial and mobility systems. The push toward smarter factories, responsive motor control, and modular automation architectures is expanding the set of points in a design where isolated switching is useful. Telecommunications infrastructure, particularly where power distribution and signal routing must remain robust under continuous operation, continues to represent a substantial demand base. Medical device developers also rely on isolation for safety-critical circuits, and the trend toward more compact, portable, and battery-aware equipment is reinforcing interest in relay solutions that combine isolation with minimal footprint. Automotive and electric vehicle applications form a faster-growing but more exacting demand pocket, where temperature tolerance, vibration resilience, and high-frequency switching capability determine commercial relevance.
Supply Chain and Cost Structure Evolution
Cost structure remains a pivotal driver of competitive outcomes. The rise in GaAs and silicon substrate costs, coupled with higher energy and labor expenses, has raised the baseline cost of production and increased the importance of yield optimization, packaging efficiency, and supply continuity planning. Smaller manufacturers have been disproportionately affected, with a notable share reporting exposure to component cost volatility and a measurable increase in production energy usage across the sector. This environment rewards firms that can manage bill-of-material variability, secure stable substrate supply, and design around cost-effective package options without compromising qualification readiness.
Strategic sourcing is becoming more important as a differentiator. Producers that build relationships with qualified substrate suppliers, maintain disciplined inventory planning, and design families of parts that share common internal architectures can reduce per-unit complexity and improve margin resilience. In this sense, the cost story is not only about reacting to price increases; it is about engineering the product portfolio and manufacturing flow to tolerate volatility while preserving performance integrity.
Competitive Landscape and Leading Strategies
The competitive field is anchored by a group of established electronics and components manufacturers with distinct positioning strategies. Panasonic Corporation has built a broad offering around its proprietary PhotoMOS MOSFET-based optically isolated semiconductor relays, with a wide variant range designed to cover automation, automotive, and high-frequency switching needs. Its emphasis on low leakage and stable on-resistance reflects a focus on predictable switching behavior across diverse application conditions. The breadth of variants supports integrators who need multiple specification points within a consistent family, reducing design fragmentation and simplifying substitution decisions.
PhotoMos Relays Market
OMRON Corporation positions its MOSFET relay line around optical semiconductor technology that combines LED input, photodiode array detection, and MOSFET output for non-contact signal and power switching. This framing emphasizes the isolation mechanism and the resulting contactless operation, appealing to applications where switching reliability and isolation clarity are central to the design rationale. OMRON’s strategy appears to lean on integration ease and application breadth, providing engineers with drop-in options that align with established industrial and instrumentation workflows.
Toshiba Electronic Devices & Storage Corporation has focused on photorelays with MOSFET output, including voltage-driven models and high-temperature variants tailored for semiconductor testers, electric vehicles, and high-frequency applications. Its recent push into small packages with elevated temperature ratings illustrates a clear strategic move toward thermally demanding and space-constrained deployments. By targeting automotive and industrial equipment with devices that can withstand higher operating temperatures, Toshiba is positioning itself in segments where qualification durability and package efficiency translate directly into commercial advantage.
Littelfuse, Inc. brings an optically isolated MOSFET power relay portfolio aimed at DC switching in motors, medical systems, robotics, and vehicles, with emphasis on high isolation and current handling. This positioning underscores the power-handling side of the market, where the value proposition extends beyond signal switching to scenarios requiring robust current transfer under isolated conditions. Littelfuse’s focus on power-centric applications complements the broader signal-switching emphasis seen elsewhere, indicating that competition is not monolithic but segmented by performance emphasis and end-use fit.
Strategic Positioning and Differentiation
Across these leaders, differentiation is emerging along three axes: portfolio breadth, application qualification readiness, and packaging efficiency. Broad variant families reduce customer integration effort and create switching costs that favor incumbents. High-temperature and voltage-driven models address the exacting requirements of automotive and industrial users, turning thermal endurance into a competitive moat. Compact packaging that preserves isolation and current capability supports density-sensitive designs, which is increasingly important as equipment footprints shrink and thermal management becomes more constrained.
Commercial success in this environment depends on aligning these attributes with real procurement drivers. Engineers do not select relays on datasheet elegance alone; they choose components that clear qualification gates, fit existing layouts, and can be sourced reliably over the product lifecycle. Suppliers that can demonstrate consistent performance across lot variations, provide clear documentation for safety and isolation requirements, and offer practical mechanical compatibility are better placed to convert technical appeal into sustained design wins.
Market Structure Evolution
The market is likely to see a mix of consolidation and targeted specialization. Incumbents with scale advantages will continue to invest in variant breadth, thermal ruggedization, and qualification support, reinforcing their hold on high-volume application areas. At the same time, smaller manufacturers may find the most viable path through niche focus, such as specialized packaging, custom voltage-driven configurations, or application-specific isolation profiles. New entrants typically face steep qualification and documentation hurdles, but targeted innovation in package form factors or substrate efficiency could create entry points where performance-per-cost improves enough to attract design attention. Overall, the concentration profile suggests that scale matters, yet differentiation in qualified performance and supply stability will determine who captures incremental share in faster-growing application pockets.
Future Trends and Commercial Opportunities
Trend 1: Thermal-Ruggedized, Voltage-Driven Devices in Automotive and Heavy-Duty Industrial Use
The demand for relays that can sustain performance at elevated temperatures is expected to strengthen as automotive and industrial equipment designs push into harsher operating envelopes. Voltage-driven photorelays in compact packages with high temperature ratings are well aligned with this direction, and volume adoption is likely to increase as validation cycles mature and supply stabilizes. The commercial opportunity here lies in securing qualified supply, offering design-in support that shortens customer validation time, and building variant coverage that matches the exact voltage and package needs of target platforms. Firms that can pair thermal robustness with reliable volume availability will be positioned to convert specification leadership into design wins.
The risk side of this trend includes qualification lag. Even when devices are technically capable, automotive and heavy-duty industrial programs require extended validation, and any supply inconsistency or lot variation can slow adoption. Thermal claims must be backed by repeatable manufacturing control; otherwise, the promise of high-temperature operation becomes a marketing point rather than a dependable design advantage.
Trend 2: Consolidation Around Supply Stability and Qualification Support
As input costs and energy expenses remain elevated, buyers will increasingly favor suppliers that reduce risk across the procurement lifecycle. This points toward a trend where the winners are not only those with strong datasheet performance but also those with demonstrated supply continuity, clear qualification documentation, and responsive engineering support. Integrating these capabilities into a coherent value proposition will become a central competitive battleground. The opportunity is to reframe the product offering from a component to a reliability package: part selection assistance, documentation readiness, lot consistency, and lifecycle availability.
The uncertainty here is that consolidation pressure can squeeze smaller players who lack scale in substrate sourcing or packaging efficiency. If smaller manufacturers cannot manage cost volatility or demonstrate qualification readiness, they may lose relevance in volume-driven segments even if their technical performance is competitive. The market may therefore prune the long tail of suppliers, leaving a mix of broad-line incumbents and a smaller set of specialized niche players.
Worldwide Opto-Isolators Market
Trend 3: Higher Switching Density and Application-Leveraged Portfolios
Because optically isolated relays reduce mechanical wear and support faster cycling, they are well suited to designs that need more switching points in less space. As automation, telecom power distribution, and medical equipment continue to increase functional density, demand is likely to grow for relay families that are optimized around specific voltage ranges, isolation requirements, and mechanical footprints. The opportunity is to build application-leveraged portfolios: groups of parts that share internal architecture but cover the voltage, current, and package variations that a given application class requires. This reduces customer integration effort and increases the likelihood of multiple design wins within the same end-use segment.
The risk is that over-broad variant proliferation can dilute manufacturing focus and raise complexity costs. The strategic answer is disciplined portfolio design: cover the most commercially relevant specification points with efficient shared architectures, and avoid spreading resources across low-demand variants that add complexity without proportional revenue potential.
Strategic Implications for Decision-Makers
For Manufacturers and Product Leaders
- Prioritize thermal-ruggedized and voltage-driven variants where automotive and heavy-duty industrial demand is expanding, and align package strategy with the compact form factors that density-sensitive designs require.
- Manage substrate and energy cost exposure through disciplined sourcing, yield improvement, and shared architectures that lower per-unit complexity without sacrificing qualification readiness.
- Invest in qualification documentation and application support as part of the product offering, since selection decisions are increasingly influenced by validation ease and supply reliability as much as by raw performance.
For Investors and Strategic Allocators
- Focus on suppliers that combine variant breadth with credible high-temperature and compact packaging roadmaps, because these attributes are most likely to capture demand in faster-growing automotive, industrial automation, and medical device segments.
- Evaluate exposure to input cost volatility and the company’s ability to sustain margins through sourcing discipline, packaging efficiency, and portfolio concentration on commercially relevant specification points.
- Watch for consolidation signals and niche specialization patterns; the market is likely to reward firms that can demonstrate supply continuity and qualification support, while marginal players without these capabilities may face share erosion.
For Procurement and Design-In Teams
- Evaluate optically isolated relays not only on datasheet metrics but also on qualification pathways, lot consistency, documentation readiness, and lifecycle availability, since these factors influence long-term program risk.
- Assess package and voltage compatibility against existing layouts and future density goals, and favor families that reduce the need for multiple discrete parts across similar switching functions.
- Plan for cost-structure variability by engaging suppliers that can provide transparent sourcing strategies and stable volume commitments, particularly for programs with elevated temperature or high-cycle requirements.
The PhotoMOS optically isolated relay market is expanding along a clear trajectory, but the most important competitive questions are no longer about whether the technology is useful. They are about which suppliers can deliver qualified performance reliably, manage cost volatility without eroding margins, and align portfolio design with the application segments that are growing fastest. For decision-makers navigating this landscape, the edge will come from detailed visibility into segment-level demand patterns, regional intensity, qualification requirements, and the specific product roadmaps that incumbents and specialists are advancing.
To map these dynamics at the granularity required for program planning, vendor selection, and investment allocation, a closer look at segmented demand estimates, regional distribution, and company-by-company positioning is essential. A full research report can provide the detailed breakdown needed to translate these strategic themes into specific sourcing decisions, portfolio priorities, and risk assessments.
For detailed analysis of this topic, please visit the official page: PhotoMOS Optically Isolated Relay Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


