



Intelligent Parcel Locker Market: Why 12.5% CAGR and Commercial Buildings Redefine Growth

The Intelligent Parcel Locker Market: Strategic Trends and Commercial Opportunities in a High-Growth Landscape
The intelligent parcel locker ecosystem has transitioned from a niche convenience to a structural component of modern logistics and urban infrastructure. Between 2020 and 2025, global revenue climbed from approximately $800 million to $1.2 billion, reflecting a compound annual growth rate of 12.5% through the forecast horizon to 2032. By the end of that period, market value is projected to approach $2.74 billion, driven by compounding pressures on last-mile efficiency, the normalization of self-service pickup, and sustained investment in connected physical infrastructure. This trajectory is not merely a function of rising e-commerce volumes; it signals a broader recalibration of how goods move through dense residential, commercial, and transit environments.
For executives, investors, and procurement leaders, the opportunity lies in recognizing where the market is genuinely differentiating versus where it remains commoditized. The sector has entered a phase where deployment speed, carrier-agnostic interoperability, and functional specialization determine competitive advantage. Yet the same forces creating tailwinds also expose operational and regulatory friction that can stall rollouts or compress margins if not addressed early.
Market Snapshot and Structural Constraints
The revenue trajectory across the 2020–2032 window demonstrates steady accumulation rather than cyclical spikes, with the most pronounced inflection occurring between 2023 and 2026. That pattern aligns with the maturation of carrier-agnostic locker networks, the scaling of multi-function units, and the gradual shift from pilot deployments to standardized portfolio strategies. Market concentration remains moderate, with the top three players holding roughly a quarter of total value and the top five capturing just over a third. This fragmented structure indicates room for consolidation but also a landscape where regional specialists, functional innovators, and logistics incumbents can still win through targeted positioning.
PW Consulting
Several constraints are shaping how this growth actually translates into realized deployments. First, the economics of urban footprint acquisition remain uneven. High-density zones offer superior utilization but introduce zoning complexity, property-owner negotiations, and maintenance access challenges that can lengthen sales cycles. Second, the operational reliability of connected lockers depends on a layered stack of hardware durability, secure communications, and software integration with parcel management platforms. Mismatches across those layers create deployment risk, particularly when units must operate continuously in varied weather conditions while maintaining real-time status visibility for both carriers and end users. Third, the shift toward multi-functionality is introducing new performance expectations. Lockers are increasingly expected to accommodate refrigerated freshness, secure laundry exchanges, and modular reconfiguration without sacrificing throughput or simplicity for the end user. Managing that breadth of capability without inflating unit costs or complicating maintenance is a defining engineering and commercial tension.
Core Drivers Reshaping the Market
Technological Innovation and Connected Hardware
The technological evolution of parcel lockers is moving beyond isolated access control toward integrated, sensor-rich systems that support remote diagnostics, flexible carrier routing, and specialized environmental management. Modular architectures now allow operators to scale footprint and functionality as demand patterns shift, while solar-powered and off-grid configurations reduce dependency on site electrification and enable deployment in locations where wiring constraints would otherwise stall installations. Bluetooth- and IoT-enabled notifications have become baseline expectations for contactless, real-time pickup coordination, and secure data handling at the locker level has taken on added importance as tracking and access workflows generate more operational data. These capabilities are not merely feature upgrades; they directly affect utilization, downtime, and the ability of carriers and property operators to manage multiple delivery partners through a single physical footprint.
The commercial implication is clear: hardware differentiation is increasingly tied to how well a locker system integrates into broader operational workflows rather than to standalone metalbox durability. Units that can flexibly accommodate multiple carriers, provide reliable connectivity in densely built environments, and adapt to specialized loads such as perishables or laundry are gaining traction across residential complexes, retail click-and-collect points, and institutional campuses. This is accelerating a shift in procurement criteria from unit price toward total cost of ownership, uptime, and interoperability.
Worldwide Smart Electronic Locker Systems Market
Regulatory and Policy Dynamics
Policy and regulatory conditions are shaping both the pace and the structure of locker adoption. Universal service providers in Europe have expanded parcel locker networks in ways that lower delivery costs and improve consumer convenience, reflecting a strategic alignment between public logistics obligations and private infrastructure deployment. At the same time, data sovereignty frameworks in EU countries require secure, locker-based data handling for parcel tracking and access, which pushes vendors and operators toward more rigorous information governance. Spectrum and wireless regulations further influence deployment by enabling real-time IoT notifications and secure, contactless operations, making regulatory clarity around connectivity an underappreciated enabler of adoption.
These regulatory currents create a dual effect. They raise the compliance burden for cross-border or multi-jurisdiction deployments, but they also provide a structural advantage to operators and vendors that design for secure data handling and standardized connectivity from the outset. In practice, locker networks that treat regulatory alignment as an afterthought face higher integration cost and slower site approval, while those embedding compliance into architecture reduce friction and can scale more predictably across regions.
Demand-Side Shifts in Consumer and Enterprise Behavior
On the demand side, the normalization of self-service pickup has changed expectations around availability, security, and convenience. Consumers increasingly view round-the-clock access as preferable to constrained delivery windows, especially in urban settings where in-home delivery is less reliable or less desired. For residential and mixed-use properties, parcel lockers address recurring pain points around package theft, concierge burden, and space constraints. In retail environments, click-and-collect lockers help retailers and brands manage foot traffic, reduce missed-handoff friction, and create a more predictable pickup experience. Institutions such as universities and colleges are also deploying lockers to streamline distribution for campus mail, procurement deliveries, and student services.
This demand evolution is broadening the addressable use cases beyond traditional postal and courier handoffs. As a result, locker installations are increasingly evaluated on the strength of the surrounding service model: who operates the unit, how carriers are onboarded, how notifications and access credentials are managed, and how maintenance is handled over the asset life. The market is therefore rewarding operators and vendors that can present a coherent end-to-end story rather than a standalone hardware proposition.
Cost Structure and Last-Mile Labor Economics
Labor economics remain one of the most powerful structural drivers. Intelligent parcel lockers reduce last-mile labor requirements for postal and courier providers by enabling automated self-service access, which helps mitigate the cost and scheduling volatility associated with repeated delivery attempts and individual handoffs. In high-density cities, the deployment of smart lockers also supports more sustainable urban logistics by minimizing physical delivery trips, an outcome that resonates with both cost discipline and sustainability targets. The combined effect is a clearer economic rationale for shared locker infrastructure as a complement to, rather than a replacement for, traditional delivery channels.
This cost dynamic influences both carrier behavior and property-level adoption. Carriers see value in consolidating drop-offs into predictable, self-service points, while building operators and retail managers value the reduced handling burden and improved security profile. The strategic opportunity lies in aligning business models so that these benefits are captured collectively rather than siloed across separate stakeholders, which is often the difference between a one-off installation and a scaled network.
Competitive Landscape and Leading Strategies
The competitive field is diverse, spanning hardware manufacturers, service-oriented networks, and logistics-aligned partnerships that are reshaping how locker infrastructure is deployed and monetized. ZHILAI has emphasized smart locker variants that include solar-powered, Bluetooth-enabled, and refrigerated models, positioning itself around flexible last-mile pickup and self-service use cases. Quadient has built a carrier-agnostic model through Parcel Pending by Quadient, aggregating thousands of locations and pairing locker hardware with management software for residential, retail, and commercial settings. OMNIC has focused on manufacturing indoor and outdoor smart lockers, including solar off-grid options and all-in-one multi-function models suited to logistics and e-commerce operations, with protection specifications that address demanding environments. KEBA has pursued a partnership-led approach, supplying classic parcel lockers and loxmate systems under relationships with bpost and GLS, reinforcing its role in automated delivery infrastructure. Postal Source operates in the United States with intelligent locker solutions oriented toward secure package management and streamlined operations, reflecting demand for dependable hardware and process simplification in local markets.
These profiles illustrate three distinct strategic orientations. One emphasizes hardware versatility and environmental adaptability, appealing to operators with varied site conditions and specialized load needs. Another emphasizes network scale and software-managed interoperability, aiming to become the connective tissue between carriers, property operators, and end users. A third relies on established postal and logistics partnerships to secure volume and deploy standardized locker assets within existing service frameworks.
Strategic Positioning and Differentiation
The companies gaining momentum tend to differentiate along a few consistent dimensions. Carrier-agnostic network design reduces dependency on any single delivery partner and improves asset utilization by accommodating multiple service providers through the same locker footprint. Multi-function hardware, including cooling and laundry-capable configurations, extends the addressable demand beyond standard parcel handoffs and supports higher value-per-site economics where specialized flows exist. Solar and off-grid options broaden deployment feasibility and reduce site preparation costs, which is especially relevant for outdoor installations or properties with limited electrical infrastructure. Secure connectivity and data-handling rigor are becoming differentiators as regulatory expectations rise and as operators rely on remote monitoring, fault detection, and access management across distributed fleets.
Partnership strategies are equally important. Recent activity shows a clear pattern of using rail networks, courier relationships, and technology partnerships to accelerate footprint expansion. In January 2025, Quadient partnered with ScotRail to deploy smart parcel lockers across Scotland’s rail network for 24/7 secure commuter access, illustrating how transit infrastructure can serve as a distributed pickup layer. In February 2025, KEBA was selected as the exclusive supplier of classic parcel lockers for bpost in Belgium for the year, a deal that aligns hardware supply with a universal service provider’s delivery modernization efforts. In April 2025, Expedibox partnered with Virtual.com to deploy 1,700 smart lockers across Canada by 2026, showing how cross-border and multi-operator collaborations can scale regional networks quickly. In July 2025, InPost S.A. acquired a Spanish courier company to expand smart locker network coverage, signaling consolidation and vertical coordination as growth levers. In October 2025, Quadient expanded its strategic partnership with Evri to activate 2,000 additional Parcel Pending by Quadient smart lockers across the UK, reinforcing the carrier-network expansion model.
Market Structure and Evolution Trends
The market’s evolution is trending toward selective consolidation paired with continued specialization. On one hand, acquisitions and deep partnerships are concentrating network assets and carrier relationships in the hands of a smaller number of well-capitalized players. This is most visible in Europe, where locker networks are increasingly tied to postal and courier service strategies and where multi-market rollouts benefit from standardized hardware and software platforms. On the other hand, functional differentiation is creating space for new entrants and regional specialists, particularly in cooling, laundry, solar off-grid, and campus or transit-adjacent deployments. The result is a hybrid structure: a consolidating core network layer, with a more fragmented periphery where specialized use cases, local property relationships, and site-specific regulatory conditions reward tailored solutions.
For the competitive landscape, this means that scale alone is not sufficient. The winners are likely to be those that combine network density with reliable interoperability, functional flexibility where it matters, and a credible operating model for maintenance and software updates across dispersed assets. Vendors and operators that can make locker infrastructure easy to operate for multiple stakeholders will have an advantage in converting individual installations into durable network value.
Forward Trends for the Next Three to Five Years
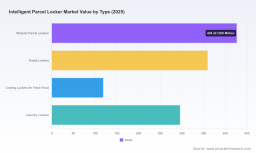
The next phase of growth will likely be shaped by three reinforcing trends. First, multi-function locker platforms will become more common as operators seek higher utilization from each installation. Refrigerated fresh-food lockers, laundry exchange models, and modular reskinning of standard units will allow sites to serve layered demand without requiring separate infrastructure for each flow. This trend creates opportunity for vendors that can deliver reliable thermal management, sanitary handling, and easy reconfiguration without sacrificing core parcel throughput. It also introduces complexity in service design, since different user workflows and maintenance requirements must be managed under one physical asset.
Worldwide Luggage Storage Locker Market
Second, connectivity and data governance will increasingly determine deployment velocity. As IoT-enabled notifications and remote management become standard, the quality of wireless integration, cybersecurity, and compliance with local data-handling rules will affect how quickly sites can be brought online and how confidently operators can scale. This favors organizations that treat connectivity, access control, and data handling as foundational design choices rather than downstream add-ons. The uncertainty here lies in the unevenness of regulatory requirements across jurisdictions and in the practical burden of maintaining secure, auditable systems across a growing installed base.
Third, network expansion will continue to intersect with public and transit infrastructure, retail real estate, and residential master planning. Rail networks, commuter hubs, grocery-anchored retail, and large residential complexes are natural expansion surfaces because they concentrate foot traffic, improve utilization, and reduce per-delivery friction. This creates commercial opportunity for operators that can negotiate site access, align stakeholder incentives, and sustain uptime across public-facing installations. The risk is that public-sector approval processes, property-owner alignment, and maintenance accessibility can slow rollouts or raise total cost if not managed proactively.
Together, these trends point toward a market where value accrues to entities that can integrate hardware versatility, network interoperability, regulatory readiness, and stakeholder coordination. The commercial opportunity is not simply to sell more lockers, but to build locker ecosystems that produce measurable reductions in delivery friction, operational burden, and missed-handoff losses while remaining adaptable to changing demand.
Strategic Considerations for Decision Makers
For Manufacturers and Technology Providers
Product roadmaps should prioritize modular scalability and interoperability as much as hardware durability. Units that can be reconfigured for cooling, laundry, or standard parcel use, and that support solar or off-grid deployment where site conditions require it, will open more addressable opportunities. Equally important is the software layer: remote diagnostics, secure access workflows, and compatibility with multiple carrier systems reduce the operational friction that often undermines broad adoption. Manufacturers that invest early in these capabilities and document their reliability across varied environments will be better positioned to participate in scaled network deployments rather than one-off sales.
For Investors
The market’s moderate concentration and steady growth trajectory suggest a landscape with both consolidation candidates and specialized innovators. Capital allocation decisions should account for the distinction between asset-heavy network models and hardware-plus-software positions that depend on partnerships for scale. Networks tied to credible carrier relationships, transit or retail footprints, and repeatable site-procurement processes offer more predictable expansion paths, while highly specialized hardware plays may deliver stronger differentiation in narrower segments. Due diligence should emphasize utilization economics, maintenance burden, data-handling compliance, and the durability of partnerships that drive deployment pipelines.
For Procurement and Operations Leaders
Procurement decisions should evaluate locker solutions as long-lived operational assets rather than commoditized endpoints. Key evaluation criteria include carrier-agnostic usability, uptime and remote management capabilities, security and data-handling alignment, and the practicality of installation and maintenance at the intended site types. Where deployments span multiple stakeholders, the operating model matters as much as the hardware: clarity on who manages access, notifications, fault response, and carrier onboarding can determine whether a locker installation becomes a shared efficiency asset or an underused inconvenience. Early alignment among property operators, delivery partners, and technology providers reduces ambiguity and improves the odds of sustained utilization.
Detailed segmentation data, regional deployment economics, and company-level assessments can sharpen these decisions further by showing where functional specialization, partnership structures, and regulatory readiness create the strongest near-term value. Comprehensive research reports can help decision makers compare vendor positions, evaluate site-level viability, and map out differentiated strategies across residential, retail, commercial, and institutional applications with greater precision. For organizations preparing investment, procurement, or expansion choices, deeper intelligence provides the granularity needed to move from broad market confidence to targeted, defensible action.
For detailed analysis of this topic, please visit the official page: Intelligent Parcel Locker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


