



Methyl Mercaptan Market 2026: Beyond the 6.5% CAGR Story

Strategic Trends and Commercial Opportunities in the Methyl Mercaptan Market: Navigating Growth Amid Structural Shifts
The global market for methyl mercaptan (methanethiol) has entered a phase of measured expansion, driven by its indispensable role as an odorant for natural gas and liquefied petroleum gas, alongside a growing footprint as a chemical intermediate in methionine synthesis and specialty applications. From 2020 through 2025, the market grew from approximately USD 118.0 million to a base-year valuation of USD 155.0 million, reflecting recovery trajectories, capacity adjustments, and steady end-use demand. Looking ahead to 2032, the trajectory points toward sustained upward momentum, with forecasts indicating a revenue base that climbs steadily toward USD 225.0 million. This expansion corresponds to a compound annual growth rate of 6.5% across the 2026–2032 forecast period, a figure that signals broad-based acceptance rather than speculative overgrowth. While the headline numbers provide directional clarity, the strategic reality on the ground is more nuanced: growth is uneven across applications, supply chain dynamics are tightening, and regulatory scrutiny is reshaping operational playbooks for producers and downstream users alike.
Market Landscape and Core Challenges
The market's current structure is characterized by a concentration that remains moderately fragmented at the top but increasingly consolidated in terms of strategic capability. The leading three firms account for roughly 35% of revenue, while the top five extend that share to approximately 48%, indicating that scale, integration, and technical differentiation are becoming more important than pure volume dominance. This balance creates room for specialized players while simultaneously raising the bar for competitive resilience. The most consequential shift is not a single disruption but a convergence of constraints that are redefining how value is captured.
One central challenge is the tension between feedstock stability and margin preservation. Methyl mercaptan is predominantly produced through the reaction of hydrogen sulfide with methanol, a route that is technically mature but highly sensitive to methanol pricing, logistics, and regional availability. As methanol markets experience episodic volatility—particularly in major consuming regions where spot prices can spike sharply—producers face a recurring test of whether to pass through costs, absorb them through operational efficiency, or restructure contracts to smooth exposure. The second challenge lies in regulatory complexity. Methyl mercaptan is classified as a toxic substance with a permissible exposure limit of 0.5 ppm under occupational safety standards, and it falls under risk management programs with threshold quantities that require active compliance planning. Its hazardous waste classification further introduces recordkeeping, handling, and transportation obligations that can escalate the cost and risk profile of operations, especially for facilities functioning near urban or environmentally sensitive zones.
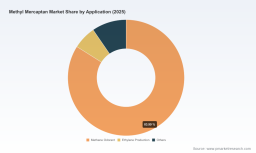
A third challenge emerges from application concentration and the reputational sensitivity of odorization. The largest share of demand continues to stem from methane odorant use, which ensures gas leak detection and public safety. While this application is structurally durable, it also subjects producers to scrutiny around consistency, purity, and delivery reliability. Any lapse in quality or continuity can cascade into utility liabilities, regulatory inquiries, and reputational consequences that go beyond price competition. Together, these pressures create a market environment in which operational discipline and technical differentiation matter as much as capacity positioning.
T Dodecyl Mercaptan Market
Key Drivers Shaping Market Dynamics
Technological Innovation and Process Optimization
Innovation in methyl mercaptan production is less about reinventing the core chemistry and more about improving selectivity, purity, energy intensity, and safety. Advances in catalytic formulations, integrated reactor management, and downstream purification have enabled producers to deliver high-purity grades and tailored intermediates that meet the stricter specifications of methionine synthesis and specialty chemical applications. These improvements are strategically significant because they allow manufacturers to move up the value chain rather than compete solely on commodity volume. High-purity offerings can command stronger positioning in animal nutrition and fine chemical synthesis, where consistency and impurity control directly influence downstream performance. At the same time, process improvements that reduce energy consumption and waste generation help offset some of the cost pressure from raw materials, reinforcing margin durability in an environment where feedstock prices can shift quickly.
Policy and Regulatory Environment
Regulatory frameworks are acting as both a constraint and a catalyst for disciplined growth. Occupational exposure limits, risk management requirements, and hazardous waste classification elevate the compliance burden, but they also create a barrier that rewards operators with robust safety systems, documented processes, and strong supply chain traceability. In practice, this dynamic favors producers and distributors that invest in operational maturity, because buyers increasingly view compliance capability as part of overall reliability. Policy signals also influence demand indirectly. As gas networks and industrial consumers prioritize safety and environmental performance, odorization requirements are likely to remain stable or intensify, sustaining volume support for the core application. At the same time, evolving expectations around emissions, handling, and waste management are pushing firms to modernize storage, transport, and reporting practices, which may favor integrated players with the capital and technical resources to adapt quickly.
Demand-Side Shifts in Consumption and End-Use Behavior
Demand growth is being propelled by a combination of energy infrastructure needs and expanding use in animal nutrition and chemical synthesis. Natural gas odorization remains the dominant application, and its durability is reinforced by continued focus on leak detection, network safety, and regulatory expectations around gas quality. Beyond this core, the role of methyl mercaptan as a chemical intermediate is gaining strategic relevance, especially in methionine production and related applications where it supports downstream nutritional and formulation needs. This dual structure is important for commercial strategy because it diversifies exposure: the odorant market provides scale and consistency, while specialty intermediates offer differentiation and higher value capture. Demand-side behavior is also shifting toward buyers who prioritize reliability, specification consistency, and supplier compliance over lowest price, a trend that strengthens the position of suppliers capable of demonstrating technical and operational maturity.
Supply Chain and Cost Structure Evolution
Cost structures are increasingly shaped by regional feedstock dynamics and logistics. Methanol pricing, in particular, has become a critical variable, with spot markets exhibiting periods of sharp movement that can affect production economics and contract stability. For producers, the practical response is to develop more sophisticated procurement strategies, flexible sourcing, and transparent cost pass-through mechanisms where market conditions allow. For downstream users, the implication is that long-term supply relationships, quality assurance, and delivery reliability may increasingly outweigh marginal price differences. The supply chain is also being influenced by geographic diversification. India has emerged as an active production and export base, adding a new layer of capacity and competition that can improve availability but also introduces new expectations around consistency, certification, and compliance. This expansion is constructive for buyers seeking flexibility, while challenging established players to sharpen their value propositions beyond simple volume.
Competitive Landscape and Leading Strategies
The competitive environment reflects a blend of large-scale integrated producers and focused regional manufacturers, with strategies that diverge based on geographic footprint, product breadth, and technical specialization. Chevron Phillips Chemical Company stands out as a leading-volume producer, positioning methyl mercaptan as a specialty chemical intermediate with strong relevance to methionine synthesis and broader applications. Its scale and integration provide a foundation for consistent supply and broad market reach, and its profile underscores the importance of linking volume leadership with application-specific capability. Arkema S.A. operates through its thiochemicals platform, offering methyl mercaptan and high-purity grades as well as sodium methyl mercaptide alternatives for methionine production. This approach illustrates a strategy of portfolio breadth and application flexibility, enabling customers to select from related chemistries depending on process requirements and formulation goals. Evonik Industries AG incorporates methyl mercaptan within a specialty chemical portfolio tied to animal nutrition and chemical synthesis, emphasizing application alignment and quality differentiation rather than pure commodity competition.
Worldwide Mercaptans Market
A distinct competitive layer is forming among Indian manufacturers such as Vizag Chemical International and Triveni Interchem Private Limited, both active in production and export. Their presence adds capacity and geographic optionality, particularly for international buyers seeking alternative sourcing points and cost-competitive supply. While scale and global integration differ across these companies, the common strategic thread is the ability to meet industrial specifications and export demand with increasing reliability. The competitive trend appears to be evolving along two axes: consolidation of advantage among firms that combine scale, technical quality, and compliance maturity, and differentiation among regional players that can compete on availability, service, and cost while steadily improving process standards.
This landscape is likely to see further selective integration and capability-based competition rather than broad consolidation for its own sake. Buyers are increasingly evaluating suppliers across a wider set of criteria, including purity, delivery consistency, regulatory readiness, and application support. In that environment, firms that invest in technical service, specification control, and transparent sourcing are better positioned than those relying primarily on price leadership. The emergence of new export-oriented capacity also suggests that regional diversification will continue to shape procurement strategies, especially as buyers seek resilience against localized feedstock volatility or logistics disruptions.
Future Outlook: Trends and Commercial Implications
Refined Value Capture Through Application Diversification
Over the next three to five years, the market is expected to tilt further toward value differentiation enabled by application breadth and specification leadership. Odorization will remain the revenue backbone, but the most strategic growth may come from higher-specification grades and intermediate uses that support methionine and specialty synthesis. Businesses that can reliably bridge core odorant supply with specialty-grade capability are likely to capture stronger positioning, because they can serve multiple demand streams while reducing dependence on any single application cycle. For commercial decision-makers, this suggests that product mix strategy and technical service capability will be as important as volume scaling.
Cost Discipline and Feedstock Strategy as Competitive Moats
As feedstock cost volatility remains a defining feature, competitive advantage will increasingly belong to firms that can manage methanol exposure with flexibility and transparency. Long-term procurement agreements, blended sourcing approaches, and operational improvements that reduce energy and waste intensity will help insulate margins. At the same time, buyers are likely to place greater weight on reliability and compliance assurance, meaning that cost leadership alone will be insufficient if it comes at the expense of consistency or risk management. The commercial opportunity here is twofold: producers can differentiate through resilient cost structures and predictable delivery, while buyers can secure supply by prioritizing partners with demonstrated feedstock management and quality control.
Regulatory Maturity as a Structural Advantage
Regulatory expectations around exposure control, risk management, hazardous waste handling, and transportation are likely to remain stringent, and in some contexts may become more operationally demanding. This environment favors organizations that treat compliance not as overhead but as a structural asset. Companies with robust safety systems, documentation discipline, and modern logistics practices will be better positioned to serve customers who face their own audit, ESG, and risk expectations. The commercial takeaway is that regulatory readiness can become a differentiator in supplier selection, especially for large downstream users and utilities where reliability and risk mitigation carry significant operational and reputational weight.
Risks and Uncertainties to Monitor
The principal uncertainties include methanol price volatility, potential regional policy shifts affecting handling and classification, and the possibility of demand softness if gas infrastructure investment or downstream synthesis demand slows. Supply diversification from new export-oriented capacity can improve availability, but it also raises expectations for specification consistency and compliance, which can become a source of friction if standards differ across regions. In addition, any disruption to logistics or distribution networks may disproportionately affect specialty-grade supply, where timing and purity are especially critical. Decision-makers should therefore build flexibility into sourcing and inventory strategies while monitoring regulatory updates that could alter handling requirements or cost structures.
Strategic Recommendations for Decision-Makers
For manufacturers and producers, the priority is to strengthen differentiation beyond volume. Investing in high-purity grades, improving process efficiency, and building transparent feedstock management capabilities can support stronger margins and more resilient customer relationships. Equally important is advancing compliance maturity as a visible capability, since occupational exposure limits, risk management requirements, and hazardous waste obligations are increasingly influential in supplier evaluations. Producers that can demonstrate consistent quality, reliable delivery, and substantive technical support will be better positioned to compete as the market rewards operational discipline alongside scale.
For investors and strategic acquirers, the market's 6.5% growth trajectory through 2032 suggests attractiveness, but value capture will depend on assessing exposure to feedstock volatility and regulatory complexity. Opportunities may be strongest in businesses that combine stable application demand with differentiated product capability or that have clear pathways to improve cost structures through procurement flexibility and process optimization. When evaluating potential investments, attention should extend beyond revenue growth to the durability of margins, the quality of compliance systems, and the alignment between product mix and end-use demand. In this market, the most compelling cases often combine predictable cash flow from core odorant demand with optionality from specialty intermediates and regional sourcing.
For procurement leaders and end-use buyers, the strategic imperative is to balance cost optimization with supply resilience and specification reliability. Price comparisons remain necessary, but they should be weighed against consistency, compliance readiness, and the supplier's ability to support application-specific needs. Diversifying sourcing where appropriate can reduce exposure to regional feedstock volatility or logistics disruption, and building long-term relationships with suppliers that demonstrate strong technical and regulatory capability can reduce the risk of supply interruptions or quality issues. In practice, procurement strategy should treat methyl mercaptan not only as a commodity input but as a component of operational safety and downstream performance.
Conclusion
The methyl mercaptan market is moving through a period in which growth is real but increasingly conditional on operational maturity, application differentiation, and disciplined cost management. The baseline trajectory points to steady expansion, yet the more important strategic question is not whether demand will rise, but how value will be captured as feedstock volatility, regulatory expectations, and competitive diversification reshape the field. Companies that align their product capabilities, compliance systems, and sourcing strategies with these shifts are better positioned to convert market growth into durable advantage. For readers seeking more granular segmentation data, regional detail, and tailored scenario analysis, the full research report offers deeper segmentation and customized guidance to support decisions at the operational and portfolio level.
PW Consulting
For detailed analysis of this topic, please visit the official page: Methyl Mercaptan Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


