



Hole Saw Market: Why 6.98% CAGR and Dry Drilling Shift Redefine Growth to 2032

Strategic Trends and Commercial Opportunities in the Hole Saw Market: A 2026 Outlook
The hole saw market has evolved from a steady, utility-driven niche into a dynamic sector shaped by material science advances, changing construction practices, and selective application expansion. Valued at approximately $335.4 million in 2025 and projected to reach $533.6 million by 2032, the market is on a six-year trajectory that reflects a compound annual growth rate near 7 percent. The historical arc from 2020 through 2025 shows a market that recovered from a mid-cycle correction in 2022 and then accelerated, reaching $328.05 million by 2024 before settling into the current base year. This pattern underscores an industry that is no longer defined by incremental volume growth alone, but by structural shifts in how holes are made, where they are made, and by whom.
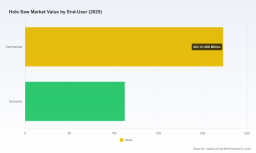
The broad-based expansion masks an underlying tension: growth is uneven across material segments, usage modes, and end-user profiles. Bi-metal solutions continue to anchor the market with the largest share, supported by versatility across metal and wood applications and sustained demand from professional trades. Carbide teeth have gained traction in rough-in and composite applications where durability and clean cuts matter, while diamond and carbon steel variants serve more specialized roles. On the application side, dry drilling represents the larger pool, reflecting convenience and speed in field conditions, whereas wet drilling remains essential where heat management and tool longevity are critical. Commercial end users account for the majority of demand, highlighting the importance of rental fleets, contracting workflows, and industrial maintenance, while domestic channels contribute a meaningful second tier driven by repairs, renovations, and DIY-adjacent professional work.
Regionally, North America leads with the strongest revenue concentration, followed by Europe and Asia Pacific, which are close in scale but differ in channel maturity and project mix. Latin America and the Middle East and Africa remain smaller but are not irrelevant; they are shaped by infrastructure cycles, public works programs, and localized procurement practices. The competitive field is highly concentrated, with the top three players holding roughly 78 percent of market share and the top five approaching 88 percent. This concentration points to mature branding, established distribution, and strong ties to professional channels, but it also leaves room for differentiation through product design, service ecosystems, and application-specific solutions.
Saw Wire Market
Market Snapshot and Structural Challenges
The hole saw market today operates in a context where demand is reliable but not uniform. The core revenue base is supported by construction, electrical, plumbing, and maintenance activities, yet the rate of adoption varies by material, use mode, and buyer type. A market moving from $335.4 million in 2025 toward $533.6 million in 2032 implies more than incremental expansion; it implies continued rewiring of how hole-cutting tools are specified, stocked, and used. The historical figures between 2020 and 2025 show resilience after a brief contraction in 2022, with a decisive rebound in 2024 and a stable, slightly higher base in 2025. This trajectory sets up a forecast period from 2026 to 2032 that hinges on continued investment in skilled trades, infrastructure maintenance, and productivity-enhancing tooling.
Beneath the growth headline, three challenges shape the market’s next phase. First, the industry faces a durability-versus-cost dilemma. Higher-performance materials and tooth geometries extend service life, but they also increase unit cost and can complicate trade-off decisions for price-sensitive buyers. Second, specification and compliance complexity is intensifying. Public works and utility projects increasingly require precise diameter control, standards alignment, and documented performance, which favors tools and systems that can meet formal requirements rather than generic substitutes. Third, channel and user behavior are fragmenting by use case. Dry drilling remains the larger operational mode, but wet drilling persists where heat, material hardness, or finish quality demand it. This duality creates a need for flexible product lines and clear guidance rather than one-size-fits-all offerings. These challenges are not barriers so much as filters: they separate products that can travel across applications from those that must earn their place in specific workflows.
Key Demand Drivers Shaping the Next Cycle
Technology and material science remain the most direct levers in this market. High-speed steel and HSS-Co grades underpin cutting performance and durability across metal and wood applications, and their continued refinement supports longer life, cleaner cuts, and better resistance to wear in demanding conditions. On the innovation side, bi-metal platforms are being reinforced with tooth designs that reduce breakage and extend useful life, while carbide and diamond variants are pushed into applications where surface quality and tool longevity justify the premium. The emergence of impact-compatible hole saws with quick-change shanks illustrates a broader push toward compatibility with modern cordless ecosystems and faster changeover on site. These advances are not merely engineering details; they translate into fewer interruptions, less waste, and better predictability for professional users who bill by the job.
Policy and specification environments are also shaping demand in subtle but durable ways. In several jurisdictions, hole saw applications are written into construction specifications for service taps on dip water mains and RCP pipes, for sewer main connections, and for utility work where accurate sizing and avoidance of damage are non-negotiable. ANSI-aligned standards and precise diameter control are increasingly referenced in public contracts for concrete and metal hole cutting, and certain stormwater and utility connection contracts explicitly list hole saw cutting as an approved method. For suppliers, this means that documentation, consistency, and compliance-ready performance can become differentiators. It also means that specifications can lock in demand for particular tool classes in recurring public projects, creating steadier usage patterns than purely discretionary construction spend.
Worldwide Wire Saw Market
On the demand side, buyer behavior is shifting toward systems and reliability rather than isolated consumables. Professional electricians, plumbers, and contractors increasingly evaluate hole saws as part of an end-to-end hole-making setup that includes arbors, ejector mechanisms, and kits sized for common tasks. Educational content and practical demonstrations have gained traction as buyers look for techniques that reduce setup time and improve results without additional jigs. At the same time, the growth of cordless tools continues to reshape expectations around weight, access, and speed, pushing accessory suppliers to optimize tooth geometry and slot designs for faster cutting in battery-powered workflows. The domestic segment adds another layer: while smaller in absolute size than commercial demand, it is responsive to renovation cycles, repair activity, and the availability of clear, application-specific kits that reduce guesswork.
Supply-side dynamics reinforce these demand shifts. The material base for hole saws depends on steel grades, coatings, and tooth technologies that must balance performance with cost and availability. Recent trade activity and product stocking decisions indicate that distributors are expanding assortments to cover a broad size range and to surface top-branded options for professional and industrial use. This breadth matters because buyers in maintenance and renovation contexts value immediate availability across common sizes, while industrial buyers prioritize predictable performance and compatibility. At the same time, raw material considerations and manufacturing complexity can affect lead times and margin structure, making inventory positioning and SKU rationalization important levers for competitiveness.
Competitive Landscape and How Leaders Position
The market is anchored by a concentrated set of U.S.-headquartered manufacturers that compete on application fit, durability claims, and brand trust within professional channels. One leading industrial cutting specialist focuses on complete hole saw system solutions, emphasizing bi-metal platforms with reinforced tooth design aimed at reducing breakage and extending service life. This positioning targets buyers who prioritize uptime and predictable performance in metal-cutting workflows. A second major player specializes in bi-metal hole saws and arbors for professional electricians and industrial use, leaning on a clear identity with trade professionals and a focus on accessories that support efficient hole-making. A third well-known power tool brand offers bi-metal and carbide-tooth hole saws with lifetime tooth break warranties, access slot designs, and claims of faster cutting for cordless tools, aligning its accessory line with the broader cordless productivity narrative. A fourth industrial brand supplies hole cutting tools, arbors, and complete systems for plumbing and construction applications, reinforcing a systems-oriented approach for trade workflows.
A fifth manufacturer emphasizes weld-together bi-metal hole saws with variable tooth design for extended life and improved cutting performance, along with heavy-duty kits, appealing to users who need robust. A sixth developer has pushed into impact compatibility for thin metal cutting, introducing quick-change quarter-inch impact shanks and rapid size changes, a move that responds to the practical need for speed and tool interchangeability on active jobsites. A seventh precision toolmaker contributes hole saw sets within a broader industrial portfolio, supporting applications where accuracy and repeatability are paramount. An eighth brand addresses rough-in and demo scenarios with carbide-tooth sets designed for clean boring through wood and nail-embedded materials, reflecting a focus on finish quality and material complexity in residential and light commercial work.
PW Consulting
These leaders differentiate not just on material or tooth count, but on how well their offerings map to recurring tasks and user expectations. Systems thinking is a recurring theme: arbors, ejectors, kits, and warranty language are used to reduce friction and increase confidence. Brand trust and trade-channel relationships remain powerful assets in a concentrated market. At the same time, the competitive landscape is not static. New product launches and stock expansion decisions show that incumbents continue to refresh assortments and add technical touches, while distributors and content creators explore practical techniques that can change how tools are used. The evolution is less about dramatic market disruption and more about layered differentiation: better compatibility with cordless tools, clearer guidance for specific materials, and stronger alignment with specification-driven public work. Consolidation pressure remains high at the top, but there is ongoing room for specialists to capture niches by solving a narrow, high-friction problem exceptionally well.
Forward-Looking Trends and Where Value Is Likely to Accumulate
Over the next three to five years, one durable trend is the continued synchronization of hole saws with cordless and impact-driven workflows. As battery tools become more prevalent in trade settings, accessories that cut faster, reduce binding, and change over quickly will be favored. This favors tooth geometries, slot designs, and shank configurations that are optimized for modern power sources and for reduced setup time. The commercial implication is that accessory portfolios must be evaluated not in isolation, but as part of the tool-using ecosystem, with speed, compatibility, and breakage resilience becoming core purchasing criteria.
A second trend is the rising importance of specification-driven demand in public works and utility projects. Where standards and precise diameter control are written into contracts, tools that can demonstrate conformance and reliable performance will see more predictable repeat demand. This shifts some competition away from pure price toward documentation, consistency, and the ability to support compliance requirements in sewer, water main, and stormwater applications. Suppliers that can map products to common specifications and provide clear technical backing are better positioned to participate in recurring public project spend.
A third trend is the ongoing segmentation of the market by material and use mode, with bi-metal retaining a broad base, carbide and diamond gaining in targeted applications, and carbon steel serving cost-sensitive roles. The practical takeaway is that growth will likely come from better matching of product attributes to defined tasks, not from a single universal solution. Kits that combine common sizes, complementary arbors, and core-ejection features can reduce friction and expand the addressable set of jobs. In parallel, educational and demonstration content will continue to influence adoption by making advanced techniques accessible without specialized jigs.
These trends carry both opportunities and risks. The opportunity lies in product-line clarity, stronger trade and public-sector alignment, and accessory ecosystems that reduce downtime. The risk is over-indexing on premium materials without clear user value, allowing price pressure and channel fragmentation to erode margins. A related uncertainty is the pace of cordless adoption across different trades and geographies, which can shift the relative attractiveness of specific tooth and shank designs. Finally, specification reliance can be a double-edged sword: it creates steady demand where present, but can also slow switching if new tools must pass formal review before substitution is accepted.
Actionable Guidance for Decision Makers
For manufacturers, the priority is to sharpen application fit and reduce friction in the field. That means investing in tooth and slot designs that improve speed and breakage resistance for cordless and impact use, while maintaining clear bi-metal platforms for broad metal and wood coverage. Equally important is the surrounding system: arbors, ejectors, sizing ranges, and warranty language that make the product easier to trust and easier to use. Inventory breadth should be balanced with discipline, focusing on sizes and kits that align with high-frequency tasks in trade and maintenance channels. Where possible, technical documentation and compatibility information should be explicit enough to support specification use and to reduce purchase hesitation.
For investors, the market’s concentration and steady growth create a landscape where execution quality matters more than broad category exposure. Value is likely to accumulate where portfolios are tightly aligned with professional workflows, where durability claims are backed by design and documentation, and where accessory ecosystems increase stickiness within trade channels. The spread between dry and wet use modes, and between commercial and domestic demand, suggests that companies with flexible product strategies and strong channel relationships can sustain more predictable revenue than those dependent on narrow, cyclical segments. Monitoring specification adoption in utility and public works, cordless compatibility trends, and distributor assortment decisions will provide early signals of where demand is heading.
For procurement and operations leaders, the practical mandate is to standardize around tools and systems that reduce changeover time and improve result consistency. Preference should be given to offerings that support common tasks, offer clear diameter control, and come with documentation suitable for specification environments when relevant. Kit-based purchasing can lower error rates and simplify stocking for frequent jobs, while impact-compatible and quick-change designs can improve throughput in battery-powered workflows. In specification-driven projects, confirming that tooling meets referenced standards and diameter requirements should be part of procurement checks, not an afterthought.
For leaders seeking to move faster with segment-level detail, sizing distributions, regional channel dynamics, and supplier-by-supplier positioning, a complete research report is available. It provides granular breakdowns across type, application, end-user, and region, along with company profiles and recent market developments that support scenario planning and market-entry decisions. Accessing that detail enables more precise sizing of opportunities, sharper competitive benchmarking, and customized recommendations aligned with specific product strategies and buyer contexts.
For detailed analysis of this topic, please visit the official page: Hole Saw Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


