



Power Cords & Extension Cords Market: 6.2% CAGR Trajectory Changes Everything

The Power Cords & Extension Cords Market: Strategic Shifts and Commercial Opportunities (2026–2032)
The global market for power cords and extension cords has matured into a sector defined by steady value accumulation, structural segmentation, and incremental but consequential regulatory change. Over the 2020–2025 period, revenue expanded from roughly $3.26 billion to $4.4 billion, establishing a trajectory that carries forward into the 2026–2032 forecast window. The extended outlook points to a compound annual growth rate of 6.2%, lifting projected revenue to approximately $6.68 billion by 2032. This pace is neither explosive nor stagnant; it reflects a market where demand fundamentals are broad-based, yet growth is increasingly tied to differentiation in safety, performance, and application-specific engineering.
Regional activity illustrates a market that is geographically diversified but unevenly developed. North America and Asia Pacific together anchor the largest revenue pools, reflecting mature commercial construction patterns, dense electronics ecosystems, and sustained household demand. Europe remains a substantial contributor, shaped by localized certification regimes and building practices. Latin America and the Middle East/Africa represent smaller but expanding bases, often driven by infrastructure investment, urbanization, and gradual formalization of electrical supply chains. Rather than signaling saturation, the geographic spread highlights where product configuration, voltage standards, and certification pathways must be managed with precision.
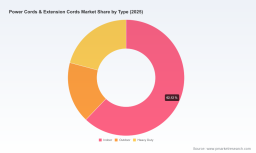
The market is structurally split across indoor, outdoor, and heavy-duty product families. Indoor configurations hold the largest share, supported by continuous deployment in homes, offices, and light commercial environments. Outdoor solutions form a smaller but resilient segment tied to construction, outdoor equipment, temporary power setups, and seasonal demand cycles. Heavy-duty cords occupy a distinct position, serving industrial use, medical-adjacent environments, and settings where thermal stress, abrasion resistance, and mechanical durability are non-negotiable. Application-side demand also divides across residential, commercial, and industrial channels. Residential remains the largest demand base, commercial contributes a meaningful mid-tier volume, and industrial represents a specialized segment that rewards higher engineering rigor and compliance confidence.
Key Challenges and Inflection Points
A market growing at a consistent mid-single-digit rate can still feel pressure at the margin. Three challenges stand out as current inflection points. First, raw material volatility is reshaping cost expectations. Price movements in PVC and related polymer inputs have introduced variability in production economics, especially for manufacturers balancing export competitiveness with domestic cost structures. The gap between regional input prices has become more than a procurement issue; it now influences margin planning, inventory strategy, and the timing of price adjustments to downstream customers.
Second, safety and certification requirements are tightening in ways that alter product design and time-to-market. Recent revisions to the UL 817 standard for cord sets and power-supply cords, including new provisions for heater-use power-supply cords, reflect a broader push toward clearer performance expectations in higher-load and thermally sensitive applications. For manufacturers, this is not merely a compliance update. It changes testing protocols, documentation practices, and the engineering margin needed to remain acceptable across North American and internationally harmonized channels.
Third, the market faces an identity challenge around commoditization versus specialization. Many product forms are still viewed as interchangeable, especially in price-sensitive consumer channels. Yet the highest-value opportunities increasingly reside in application-specific performance, traceability, and certification clarity. Companies that compete primarily on generic specifications risk margin compression, while those building defensible positions around medical-grade, industrial-grade, or custom cord sets are better positioned to protect pricing and customer retention.
Key Drivers Reshaping Market Trajectory
The 6.2% CAGR over the forecast horizon is not simply a continuation of past momentum. It reflects structural drivers that interact with one another: technology, regulation, demand-side behavior, and cost architecture. Understanding how these forces converge is essential for deciding where to invest, where to build capability, and where to exercise caution.
Innovation in Materials, Plug Geometry, and Application-Specific Design
One of the more durable drivers is incremental engineering innovation. Power cord and extension cord demand is not only increasing in volume; it is becoming more exacting in specification. This includes better insulation and jacket formulations that balance flexibility, flame resistance, and thermal endurance. It also includes design improvements in connector geometry, strain relief, and cord organization, which matter in both residential convenience and commercial durability. In data center-adjacent and hospital-adjacent settings, where cord integrity is tied to uptime and safety, even modest improvements in strain management, labeling, and configuration consistency can influence procurement decisions.
A second innovation theme is the broadening of purpose-built product families. Heavy-duty and outdoor configurations continue to gain relevance in applications where exposure, repeated flexing, and mechanical stress are routine. Medical-grade and hospital-grade cord sets represent a narrower but higher-stakes segment where performance documentation and certifiable consistency can become competitive differentiators. Custom wiring harnesses and OEM-tailored solutions extend the market beyond standardized retail SKUs into value-added configurations that are less vulnerable to direct price comparison.
Regulatory and Certification Dynamics
Regulatory expectations are becoming a more explicit part of market strategy. Certification is already central to many channels, but recent standard revisions are adding precision around higher-risk use cases. The July 30, 2025 revision of UL 817 introduced new requirements for heater-use power-supply cords, signaling that regulators are paying closer attention to load conditions where thermal management becomes critical. This matters because heater-related applications often operate near the upper bounds of common cord capabilities, where small specification gaps can become safety or reliability concerns.
For companies with North American exposure, UL alignment is a market-access prerequisite in many cases and a competitive trust signal in others. For internationally oriented manufacturers, the challenge is maintaining certification readiness across multiple regulatory regimes while keeping product families efficient enough to avoid over-fragmentation. The practical effect is that compliance is no longer a back-office function; it is increasingly part of product strategy, marketing credibility, and channel access.
Demand-Side Shifts in Residential, Commercial, and Industrial Use
Demand behavior is evolving on both the consumer and enterprise sides. In residential settings, the growth of home offices, entertainment setups, and smart-home devices continues to support accessory demand. Extension cords and power strips are no longer treated solely as temporary utilities; they are being chosen for cord length, barrier compatibility, aesthetic integration, and perceived safety. In commercial environments, demand is shaped by office refurbishment, retail upgrades, hospitality turnover, and the ongoing need for flexible power distribution during fit-outs and reconfigurations.
Industrial demand plays a different role. It is less about volume expansion and more about reliability, specification discipline, and supply assurance. Factories, maintenance operations, and facilities teams often prioritize cords and cord sets that can withstand repeated use, environmental exposure, and inspection regimes. As industrial procurement becomes more selective, the value shifts toward documentation, consistency, and the ability to match cord sets to specific equipment and site conditions.
Supply Chain and Cost Structure Pressures
Cost structure remains a pivotal driver because it influences both competitiveness and product strategy. Recent pricing movements in PVC illustrate how material economics can diverge by region. In April 2026, China PVC prices were reported near $735.45 per metric ton, while U.S. PVC prices were reported at $822.45 per metric ton. That spread matters for manufacturers operating across export and domestic channels, because it affects landed cost, relative pricing power, and the attractiveness of localization versus import-based supply.
Beyond raw materials, the supply chain is also being shaped by the need for resilience. Procurement teams increasingly value supplier stability, lead-time predictability, and the ability to support custom configurations without excessive turnaround penalty. As a result, some buyers are willing to accept differentiated pricing if it is paired with dependable certification support, batch consistency, and timely delivery. This is gradually shifting the market from pure cost competition toward a more balanced evaluation of cost, risk, and performance assurance.
Competitive Landscape and Leading Strategies
The competitive field is broad, with participants spanning large North American and European manufacturers, Indian electricals players, and specialized Asian cord-set producers. What distinguishes the more successful players is not simply scale, but the ability to align product families with the market’s growing emphasis on safety, application specificity, and configuration flexibility.
Southwire Company LLC occupies a strong position in building wire and cable, including extension cords used in utility, industrial, and commercial applications. Its profile reflects a broad distribution footprint and familiarity with the requirements of installation, infrastructure, and commercial construction markets. For Southwire, the strategic advantage lies in combining product breadth with the credibility needed to serve demanding channel requirements.
Volex plc represents a more globally integrated model, manufacturing power cords, plugs, connectors, and custom wiring harnesses for consumer, industrial, and data center-related uses. Its broad configuration capability supports customers that need standardized solutions and tailored assemblies alike. The strategic implication is that cord-set suppliers with harness and connector expertise can capture additional value by addressing OEM and facility needs beyond simple off-the-shelf cords.
Havells Ltd and Goldmedal Electricals both illustrate the strength of electricals-focused manufacturers in India, with product lines spanning home electricals, extension cords, flexible cables, switches, and power accessories. Their relevance comes from serving both residential and commercial channels with products that balance affordability and practical reliability. In these markets, scale in distribution, brand recognition, and breadth across electrical accessories can be as important as cord-specific engineering.
In China, Ningbo Biaoda Electric Co., Ltd., Jiaxing Hongzhou Cable Co., Ltd., and similar specialized manufacturers reinforce the region’s role as a production base for power cords, power boards, extension cords, and power strips. Their competitive strength typically lies in manufacturing efficiency, configuration variety, and export readiness. The challenge for these players is converting cost and volume advantages into durable positioning, particularly as buyers pay closer attention to certification, traceability, and application suitability.
Taiwan-based YFC-Boneagle Electric Co., Ltd. adds a further dimension through global exports of power cords, cord sets, LAN cables, and networking accessories. Its export-oriented profile underscores how regional manufacturers can compete internationally by aligning with end-market requirements in connectivity and power distribution.
On the U.S. and specialty side, Kord King, Electri-Cord Manufacturing, Webber Electronics, Inc., Z-Tronix Inc., and Quail Electronics, Inc. illustrate a different competitive logic. Kord King’s emphasis on premium cords, medical-grade, heavy-duty, and construction-grade cord sets shows how a manufacturer can pursue higher-margin positioning by aligning with demanding use cases. Electri-Cord Manufacturing’s focus on domestic, international, and hospital-grade cords reinforces the same theme: specialty certification and application specificity can create defensible niches. Webber Electronics combines international, North American, hospital-grade, and GFCI power cords across medical, industrial, dental, and commercial markets, reflecting the importance of multi-standard readiness and sector-targeted product lines. Z-Tronix and Quail Electronics extend this pattern with OEM, industrial, commercial, and international configuration capabilities, including custom power cords and cord sets. Their presence suggests that serving both standard and custom requirements can be a practical way to diversify demand while maintaining deeper customer relationships.
PW Consulting Information & Electronics Research Center
Strategic Positioning and Differentiation
Across these companies, several strategic patterns are emerging. One is the move toward application-specific credibility. Manufacturers that can demonstrate consistent performance in medical, industrial, or higher-load contexts are better positioned to escape pure price competition. Another is the blending of standardization with customization. Companies offering both standard cord sets and tailored configurations can capture broader demand while preserving relationships with customers who need tailored specifications. A third pattern is certification readiness as a competitive asset, especially where UL and other standard alignments affect purchasing confidence and channel access.
Market Structure and Evolution
Market concentration remains moderate. A collective concentration reading shows that the top three participants account for roughly 28.5% of the market, while the top five reach about 39.2%. This suggests a field that is not dominated by a small number of incumbents, but still features meaningful leadership positions. The structure leaves room for both consolidation and specialized entry.
Consolidation is plausible in segments where distribution scale, certification infrastructure, and cost discipline matter increasingly. New or expanding entrants can still find openings by focusing on underserved configurations, niche certification needs, or regional demand that is not fully served by larger players. At the same time, the low-concentration structure means that brand trust, product reliability, and compliance documentation can be decisive in purchasing decisions, particularly when buyers compare otherwise similar offerings.
Future Trends and Commercial Implications (2026–2032)
Looking ahead, the market’s direction is unlikely to be driven by a single breakthrough. More likely, it will be shaped by the compounding effect of specification tightening, demand fragmentation, and cost-aware procurement. Three trends are especially relevant for decision-makers.
First, application-specific certification and documentation will become more central to product competitiveness. As revisions such as the UL 817 update for heater-use power-supply cords take effect, buyers in higher-load or higher-risk environments will likely increase scrutiny on whether cords are explicitly appropriate for the intended use. This favors manufacturers that can provide clear guidance, consistent batch quality, and reliable conformity evidence.
Second, cost and material volatility will continue to reward supply chain discipline. With regional PVC pricing divergence and broader input variability, companies that can manage inventory, hedging, sourcing mix, and localized production more effectively will have an advantage in protecting margins without sacrificing service levels. This may also encourage more regionalized production or supplier diversification in response to regional cost differentials.
Wireless Chargers & Power Cords and Portable or Wearable Charging Cable Market
Third, demand will continue to fragment across more specialized use cases, increasing the importance of configuration capability. Residential convenience products will persist at scale, but commercial and industrial buyers will increasingly value solutions tailored to equipment, environment, and installation constraints. That creates opportunities for cord-set suppliers that combine standard SKUs with custom engineering, especially where connectors, cord length, jacket type, and certifying marks must be aligned to specific procurement standards.
Risks and Uncertainties
These opportunities are not risk-free. Regulatory evolution can accelerate and vary by region, imposing additional testing and documentation burdens that disrupt product rollouts if compliance systems are not prepared. Raw material price swings may compress margins more quickly than pricing adjustments can recover them, particularly for manufacturers with limited flexibility in sourcing or product mix. There is also the persistent risk that certain consumer-facing categories remain commoditized for longer than anticipated, making volume growth dependent on distribution strength and promotional intensity rather than value-based differentiation.
Another uncertainty lies in the pace of channel consolidation among buyers. If procurement becomes more centralized and specification-driven, smaller suppliers may face higher barriers to entry unless they can demonstrate clear technical or certification advantages. Conversely, if buyers continue to value flexibility and responsiveness, specialized suppliers may retain a strong position even in a moderately concentrated market.
Actionable Recommendations for Decision-Makers
For manufacturers, the central question is whether product strategy is built around interchangeable volume or defensible specialization. The more durable path is to align at least part of the portfolio with higher-trust applications and clearer certification requirements. That could mean investing in medical-grade or industrial-grade offerings, strengthening documentation for heater-use and other higher-load applications, and ensuring that connector and cord configurations are developed with end-use conditions in mind rather than generic specifications alone. It also means checking whether cost structures can absorb regional material volatility without forcing reactive price moves that erode customer trust.
Appliance Power Cord Market
For investors, the market offers a mix of steady growth and selective upside. Broad exposure may be attractive for its consistency, but the most meaningful value creation is likely to come from companies that demonstrate certification readiness, application specificity, and the ability to serve custom or higher-specification demand. Due diligence should pay attention to whether a company’s product mix is concentrated in price-sensitive commodity segments or balanced with segments that justify stronger pricing and longer customer retention. Supply-chain resilience and regional cost positioning should also be evaluated, given the divergence in raw material pricing and its effects on competitiveness.
For procurement and supply chain leaders, the priority is to treat cord and cord-set purchasing as a specification and risk decision, not solely a unit-cost decision. Evaluations should include suitability for the intended application, certification alignment, traceability, and the supplier’s ability to support standard and custom configurations without unacceptable lead-time penalties. Where operations involve higher loads, medical contexts, or industrial conditions, the cost of qualification errors can exceed the apparent savings from choosing the lowest-priced option. Supplier stability and documentation quality are therefore part of the value equation, not optional extras.
The broader takeaway is that the power cords and extension cords market is changing in ways that reward preparedness. The growth path is solid, but the competitive winners will be those who interpret regulation, cost volatility, and demand fragmentation as strategic signals rather than background noise. For organizations that need detailed segmentation, regional cost dynamics, and application-level demand patterns to refine their plans, deeper commercial intelligence can shorten the gap between high-level strategy and executable action.
For detailed analysis of this topic, please visit the official page: Power Cords & Extension Cords Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


