



Anti-Decubitus Cushions Market: How $738M in 2025 Sparks a 6.05% CAGR Shift

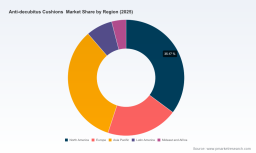
The Anti-Decubitus Cushions Market: Strategic Trends, Competitive Positioning, and Commercial Opportunities Through 2032
Understanding the Current Market Landscape
The global anti-decubitus cushions market has entered a phase of steady expansion, driven by evolving patient care standards, aging demographics, and a growing emphasis on pressure injury prevention across healthcare and home-care settings. From 2020 through 2025, the sector experienced consistent growth, supported by rising institutional procurement of specialized seating solutions and expanding clinical recognition of pressure redistribution technologies. By 2025, the market reached a revenue base that reflects both mature product adoption in established healthcare systems and incremental penetration in emerging care environments. Moving forward, the forecast period through 2032 points toward a sustained mid-single-digit compound annual growth trajectory, indicating that demand is not merely cyclical but structurally anchored in long-term care requirements.
Outdoor Cushions Market
This growth pattern, however, is not uniform. The market continues to navigate a transition from standardized, commoditized cushion designs toward differentiated, risk-stratified solutions that address varying pressure injury severities, patient mobility profiles, and care settings. At the same time, distribution channels, reimbursement pathways, and procurement cycles remain complex, creating barriers to rapid scaling for manufacturers and suppliers alike. Understanding where value is created and where friction persists is essential for executives evaluating market entry, portfolio expansion, or supply chain repositioning.
Core Challenges and Inflection Points
Three structural challenges currently shape the market's trajectory and determine which players can convert volume growth into sustainable margin expansion.
PW Consulting
- Regulatory and compliance fragmentation continues to influence product development cycles and market access. Cushions intended for wheelchair seating and pressure redistribution must satisfy multiple technical and safety expectations, including flammability requirements, washability standards, and performance benchmarks for seating stability and pressure distribution. While certain categories benefit from streamlined premarket pathways, manufacturers still face establishment registration, listing obligations, and the need to maintain documentation that supports clinical procurement and reimbursement eligibility. This layered compliance environment increases time-to-market for new designs and places a premium on regulatory agility.
- Reimbursement architecture and purchasing dynamics create uneven demand visibility. Pressure-reducing support surfaces, including anti-decubitus cushions, are covered under durable medical equipment benefit structures, but actual utilization depends on regional policies, institutional formularies, and cost-containment pressures within healthcare budgets. Buyers often evaluate total cost of ownership, replacement frequency, and clinical outcomes rather than unit price alone, which pushes suppliers to demonstrate value beyond basic pressure relief. This dynamic can slow adoption of premium or specialized designs in cost-sensitive procurement environments, even when clinical rationale is clear.
- Material performance and durability expectations are rising as care settings demand longer service life and consistent skin-contact safety. Products relying on gel inserts, air cells, and foams must balance load distribution, contour adaptation, and resistance to wear while maintaining hygiene and inspection compatibility. As clinical protocols increasingly emphasize proactive pressure injury prevention, the tolerance for inconsistency in cushion performance narrows, forcing manufacturers to refine material selection and quality control rather than compete primarily on price.
Key Demand Drivers Reshaping the Market
Several interconnected forces are expanding the addressable market and altering how suppliers compete. Understanding these drivers helps clarify where growth is likely to concentrate and which capabilities will differentiate future winners.
Technical Innovation and Performance Differentiation
Innovation is shifting from generic cushion construction toward engineered solutions that align with patient risk levels and clinical use cases. Alternating-pressure designs, vertical air-cell architectures, and hybrid foam-and-gel configurations illustrate how manufacturers are tailoring products to specific pressure redistribution goals and positioning needs. These design choices are not cosmetic; they directly affect how effectively a cushion maintains tissue perfusion, reduces shear, and supports prolonged seating without compromising user comfort or caregiver handling.
Material requirements are also becoming more specific. Medical-grade polyurethane, structured foam layers, and air-cell systems must deliver durability, skin-contact safety, and predictable performance over repeated use and cleaning cycles. In parallel, manufacturers are increasingly designing for inspectability and launderability, recognizing that hygiene protocols and routine checks are integral to pressure injury prevention programs. The cumulative effect is a market where engineering rigor and documented performance characteristics increasingly influence purchasing decisions, particularly in higher-acuity or institutional environments.
Policy, Reimbursement, and Standards Alignment
The policy environment plays an outsized role in shaping demand stability. Because pressure-reducing support surfaces are positioned within durable medical equipment coverage frameworks, manufacturers and distributors must continuously align product attributes with coverage logic and procurement criteria. Even when certain device categories are treated with lighter premarket burdens, market access still depends on registration, listing compliance, and the ability to support end-user justification. This creates a structural requirement for transparent product documentation and clear alignment with clinical use cases.
Standards further influence competitive positioning. Performance expectations around seating stability, pressure distribution, and safety characteristics compel suppliers to maintain consistent validation processes. Where standards are well understood and broadly adopted, they can reduce uncertainty and accelerate procurement decisions. Where expectations differ across regions or care settings, they can fragment product roadmaps and increase the operational cost of serving multiple markets. For executives, the practical implication is that regulatory and standards alignment is not a back-office concern; it is a commercial differentiator that affects win rates, channel partnerships, and expansion timing.
Demand-Side Changes in Care Delivery and End-User Behavior
Demand patterns are evolving as care shifts across hospital, rehabilitation, residential, and home environments. Prolonged sitting associated with wheelchair use, supportive seating needs, and positional management requirements create multiple application pathways for anti-decubitus cushions. At the same time, clinical awareness of pressure injury prevention has increased the emphasis on proactive seating solutions rather than reactive treatment. This shift encourages earlier adoption and broader usage across patient populations that may have previously been underserved by standard seating options.
End-user behavior is also changing. Institutions and individual buyers increasingly weigh practical usability, maintenance requirements, and replacement cycles when selecting cushions. A product that performs well in isolation but is difficult to clean, inspect, or fit within existing seating systems may lose out to a moderately less advanced alternative with better workflow compatibility. As a result, manufacturers that integrate ergonomic fit, ease of maintenance, and compatibility with common seating platforms are better positioned to convert clinical desirability into commercial adoption.
Supply Chain Realities and Cost Structure Pressures
The supply side of the market continues to face pressures that influence pricing, product design, and margin management. Raw material selection for air cells, foams, and gel components affects not only performance but also sourcing complexity and production consistency. Manufacturers must manage variability in material availability, processing requirements, and quality assurance while maintaining cost structures that remain acceptable to procurement teams.
At the same time, value migration is occurring toward designs that justify their cost through durability and reduced replacement frequency. In a market where buyers evaluate long-term outcomes and total cost of ownership, suppliers that can demonstrate reliable performance over time may have more room to defend pricing than those competing on short-term unit cost alone. This dynamic is particularly relevant for companies seeking to expand into higher-specification segments or to build trust with institutional buyers who prioritize consistent outcomes over occasional cost savings.
Competitive Landscape and Leading Strategic Postures
The market is characterized by a moderately concentrated competitive structure, with leading players holding meaningful but not dominant shares. This concentration level suggests that scale alone does not guarantee advantage; rather, differentiation through product design, clinical positioning, and channel execution often determines commercial outcomes. Several established companies illustrate distinct strategic approaches within the sector.
Diversified Pressure Care Offering
Some market participants emphasize a broad pressure care portfolio that addresses high-risk patient groups and intelligent pressure management. Companies in this segment often focus on alternating-pressure designs and air-based cushion systems engineered to redistribute load and reduce ulcer risk. By building product lines around specific risk profiles and seating requirements, these suppliers position themselves as solutions providers rather than commodity cushion manufacturers. Their advantage lies in the ability to match product design to clinical need, which can strengthen adoption among care teams seeking targeted pressure redistribution and positioning support.
Specialized Seating and Positioning Expertise
Other players concentrate on seat cushion geometry, vertical air-cell configurations, and positioning-focused designs. These products are developed with an emphasis on reducing pressure injuries in higher-risk scenarios while maintaining stability and pressure redistribution performance. A positioning-oriented approach can resonate in environments where seating alignment, patient stabilization, and injury prevention are equally important. Manufacturers pursuing this path often differentiate by aligning cushion design with practical use requirements, including compatibility with wheelchair systems and ease of inspection or cleaning.
Integrated Mobility and Seating Ecosystems
A further strategic posture involves integrating cushion solutions into broader mobility and seating ecosystems. Companies with strong wheelchair or seating platform presence often leverage their distribution relationships, service networks, and product compatibility to support cushion adoption. Gel and foam insert designs, along with contoured support options, are used to address pressure ulcer prevention and body contour needs within an existing equipment framework. This ecosystem approach can reduce friction for end users, since cushions that fit well with established seating products are easier to specify and deploy.
Air-Cell and Redistribution-Focused Positioning
Certain manufacturers build competitive advantage around air-cell cushion lines designed for optimal pressure redistribution and anti-decubitus protection. Custom and standard configurations allow these suppliers to address varying patient requirements while maintaining a consistent design philosophy centered on load management. This product-centric strategy can be particularly effective in segments where pressure redistribution performance is the primary purchasing criterion and where clinicians or procurement teams seek proven cushion mechanics rather than broader portfolio breadth.
How the Competitive Landscape Is Evolving
The market is likely to continue evolving along several directions. One is gradual consolidation among suppliers seeking to capture broader seating and pressure-care value chains, especially where integrated product compatibility and service coverage can improve customer retention. Another is segmentation, with manufacturers narrowing their focus to particular applications, risk levels, or care settings in order to differentiate on performance rather than price. A third is the ongoing entry of specialized players that bring novel material approaches, ergonomic designs, or digital-adjacent support services into the category. In each case, the central question for executives is whether scale, specialization, or ecosystem integration will create more durable advantage in their target segments.
Forward-Looking Trends and Associated Opportunities
Looking ahead three to five years, the market is expected to be shaped by a small number of high-impact trends that will influence product roadmaps, channel strategy, and investment priorities.
Trend One: Greater Emphasis on Risk-Stratified Seating Solutions
As pressure injury prevention becomes more systematically integrated into care protocols, demand may progressively shift toward solutions matched to specific patient risk profiles rather than one-size-fits-all cushioning. This trend creates opportunity for manufacturers that can document differential performance across use cases and communicate clearly how a given design fits a particular clinical scenario. It also raises the importance of clinical support materials, fit guidance, and application-specific product information in procurement decisions.
Trend Two: Increased Weight on Durability, Hygiene, and Lifecycle Economics
Institutional buyers and home-care users are likely to place greater emphasis on replacement cycles, cleaning compatibility, and long-term performance stability. Products that maintain pressure redistribution characteristics over repeated use, support inspection requirements, and withstand laundering or maintenance routines may gain preference in environments where caregiver time and operational consistency matter. Suppliers that invest in lifecycle design and quality consistency can use these attributes to strengthen value propositions beyond initial purchase price.
Pressure Ulcer Treatment Products Market
Trend Three: Broader Integration with Seating Platforms and Procurement Pathways
The market may increasingly reward cushion designs that align with existing wheelchair and seating ecosystems, as well as with prevailing procurement and coverage logic. Compatibility, fit consistency, and documentation that supports reimbursement or institutional specification can reduce adoption barriers. For suppliers, this suggests value in building partnerships, service support, and product-range coherence that make selection and deployment easier for end users and intermediaries. At the same time, differences in regional reimbursement and standards environments may continue to shape where and how quickly new products scale.
Risks and Uncertainties to Monitor
Several factors could temper or redirect these trends. Changes in coverage interpretation, procurement tightening, or shifts in institutional budgeting could slow adoption of higher-cost designs. Material supply variability and manufacturing consistency challenges may affect product reliability if not managed carefully. In addition, the balance between standardization and specialization will remain contested; too much segmentation can limit economies of scale, while too much standardization can weaken clinical relevance. Executives should track these uncertainties as part of market planning rather than treating growth as automatically linear.
Strategic Implications for Decision Makers
For executives operating in or evaluating this market, the priority is to align product strategy and commercial positioning with the market's actual decision drivers: clinical relevance, durability, compliance support, and integration into care workflows. The following considerations may help structure near-term actions.
- For manufacturers and product developers: Focus engineering and documentation efforts on clearly defined application needs rather than broad, undifferentiated product lines. Where possible, design for inspectability, cleaning compatibility, and seat-platform fit, since these attributes increasingly influence repeat procurement and institutional acceptance. Align validation and material selection with the performance expectations that procurement teams and clinicians use when comparing options.
- For investors and strategic acquirers: Evaluate opportunities based on differentiation quality, reimbursement alignment, and channel leverage rather than headline volume alone. In a market with moderate concentration, value creation often depends on whether a company can maintain pricing power through demonstrable performance, reduce customer switching through compatibility and service, and scale without compromising quality or compliance readiness.
- For procurement leaders and care providers: Evaluate cushions against total use-case performance, including pressure redistribution effectiveness, maintenance burden, replacement expectations, and compatibility with existing equipment. A lower unit cost may be offset by shorter service life or workflow friction. Where possible, standardize selection criteria around clinical outcomes and operational feasibility to simplify sourcing and reduce inconsistent purchasing across sites or departments.
Conclusion
The anti-decubitus cushions market is moving through a period in which growth is supported by structural care needs, but competitive advantage is increasingly determined by how well suppliers translate clinical requirements into usable, durable, and compliant seating solutions. The companies that fare best over the next several years are likely to be those that treat product performance, standards alignment, and procurement reality as interconnected commercial issues rather than separate technical or regulatory matters. As segmentation deepens and end users place greater weight on lifecycle value, the opportunity lies in building offerings that are not only effective in principle but also practical to specify, maintain, and sustain in real care environments.
For detailed analysis of this topic, please visit the official page: Anti-decubitus Cushions Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


