



POE Market CAGR: The 7.6% Growth Story Reshaping Automotive and Packaging Demand

Polyolefin Elastomers (POE) Market: Strategic Shifts and Profitable Pathways Through 2032
The polyolefin elastomers (POE) sector is entering a phase of accelerated transformation, driven by a convergence of material science breakthroughs, shifting end-use requirements, and deliberate capacity strategies. Market size has expanded from 1,200.0 million USD in 2020 to 1,880.0 million USD in 2025, and the trajectory extends through 2032, reaching 3,112.0 million USD. The compound annual growth rate of 7.6 percent over the 2026–2032 forecast period underscores a market that is no longer growing purely on volume expansion, but increasingly on value capture, application migration, and regional realignment.
PW Consulting
A market expanding at this pace does not simply reward incremental improvements. It rewards organizations that can anticipate how performance requirements, regulatory expectations, and supply chain architecture will evolve together. POE has moved from a niche additive and specialty modifier into a core enabler for lightweighting, flexible barrier systems, durable consumer products, and increasingly, advanced electronics and renewable energy components. The question for executives, planners, and investors is not whether the category will grow, but where margin will concentrate and where competition will intensify.
The current landscape is defined by a high degree of concentration, with the top three players accounting for 65.0 percent of market revenue and the top five reaching 80.0 percent. This concentration suggests that leadership positions are already established, but it also signals that the next wave of growth will likely emerge through application-specific differentiation, capacity timing, and strategic consolidation rather than broad-based market sharing.
Market Snapshot and the Structural Crossroads
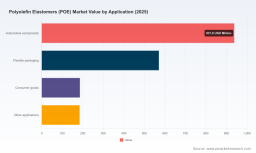
Over the 2020–2025 period, the category moved from 1,200.0 million USD to 1,880.0 million USD, reflecting a steady step-up in demand across automotive components, flexible packaging, consumer goods, and other applications. By 2025, the regional distribution indicates strong commercial presence across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, with the largest revenue pools clustered in the most industrialized and automotive-intensive markets. On a type basis, polyethylene-based POE leads with 1,412.47 million USD, while polypropylene-based POE contributes 467.53 million USD, reflecting differing property profiles and end-use preferences.
This market is now at a structural crossroads. Growth is no longer a simple function of adding capacity; it depends on aligning resin design with application economics, securing feedstock stability, and navigating an increasingly complex sustainability and compliance environment. Three challenges stand out as particularly consequential.
The first is the tension between volume expansion and differentiation. As new capacity comes online and regional supply grows, commodity pressure can compress pricing for undifferentiated grades. The organizations that protect margin will be those that translate technical properties into measurable cost-in-use advantages, not those that compete solely on price per kilogram.
The second challenge is feedstock and input volatility. POE economics remain tightly linked to ethylene, propylene, catalyst systems, and energy costs. Capacity expansions can be undermined if feedstock arrangements, energy exposure, or plant utilization assumptions do not match the operating environment. Pricing power in the category increasingly depends on integrating supply chain resilience with product design.
The third challenge is the evolving regulatory and customer sustainability agenda. Packaging, automotive, and consumer-product buyers are placing greater weight on recyclability, material efficiency, and lower-carbon production pathways. These expectations are reshaping qualification criteria, not only environmental reporting. Materials that cannot support downstream compliance or circularity goals risk losing specification positions, even if they remain technically adequate.
Key Drivers Reshaping the POE Landscape
The market’s direction is being shaped by four reinforcing forces: material innovation, policy and regulatory momentum, demand-side substitution behavior, and supply chain reconfiguration. Each driver is altering where value is created and how quickly it can be captured.
Technological innovation continues to expand the performance ceiling. POE is increasingly chosen not simply for elasticity, but for its ability to improve toughness, sealing behavior, clarity, processability, and integration with other polymer systems. This is enabling adoption in higher-value applications where conventional elastomers or softer plastomers cannot meet combined mechanical and processing requirements. The trend is especially visible where lightweighting and part consolidation reduce total system cost, or where flexible packaging demands better barrier compatibility and strength without sacrificing seal performance.
Policy and regulatory dynamics are changing the qualification bar. In several regions, decarbonization targets, extended producer responsibility frameworks, and packaging redesign expectations are altering the base assumptions for material selection. POE grades that support downgauging, multi-material compatibility, recyclability pathways, or lower embodied carbon profiles gain a practical advantage in specification decisions. In this context, the regulatory environment is not simply a compliance cost; it is becoming a filter through which certain grades become easier to specify and others become harder to defend.
Demand-side behavior is shifting from cost-first selection to performance-in-use economics. Automotive manufacturers continue to push for weight reduction and component simplification. Packaging converters and brand owners are balancing strength, appearance, and process efficiency with sustainability commitments. Consumer goods producers are looking for materials that can improve durability and aesthetic quality while maintaining manufacturability. Across these segments, the buying logic is increasingly tied to total system outcome, including processing speed, rejection rates, downstream recyclability, and end-product performance. That shift creates room for premium and semi-premium POE grades when they solve a real application problem.
Supply chain and cost structure changes are reshaping competitive positioning. New large-scale capacity additions are expanding regional availability, particularly in Asia, while established producers refine global footprints and application portfolios. The market is also seeing targeted moves around feedstock integration, plant location strategy, and consolidation. A recent example is the preliminary merger review initiated in March 2026 by South Korea’s Ministry of Trade, Industry and Resources and the Korea Fair Trade Commission regarding Lotte Chemical’s proposed merger with Yeochun NCC. The business focus of the combined entity is expected to emphasize high value-added LDPE and POE for medical use. Even at the review stage, this development illustrates a broader strategic theme: players are repositioning capacity and product direction toward higher-margin, application-specific grades rather than generic volume.
Worldwide Propylene Based POE Market
Competitive Landscape and the Logic Behind Leading Strategies
The POE market is led by firms that combine scale, application depth, and brand recognition with increasingly targeted technology and regional strategies. The leading ecosystem includes global producers and regional specialists, each pursuing a distinct route to resilience and margin protection.
The Dow Chemical Company remains a central reference point in the market, with the largest POE production footprint and well-known product families such as ENGAGE™ and AFFINITY™ across automotive, packaging, wire and cable, and specialty applications. Its strategic strength lies in breadth of application coverage and the ability to offer multiple performance tiers that fit different buyer requirements.
ExxonMobil Corporation competes through its Vistamaxx™ line, with large-scale operations including facilities such as Baytown, Texas, and a focus on elastomers for adhesives, medical, and packaging segments. Its advantage is rooted in integrated feedstock access and the ability to scale high-performance grades for demanding use cases where consistency and property control matter.
Mitsui Chemicals, Inc. is a key international producer supplying high-performance elastomers for automotive, wire and cable, and industrial applications. Its relevance in the market comes from a clear orientation toward performance-intensive segments where customers are willing to pay for optimized material behavior.
Borealis AG has built a strong position in Europe through its Queo™ platform, with offerings spanning packaging, automotive, and medical applications. Its strength lies in regional proximity to key European converters and end users, combined with a product strategy that emphasizes innovation in polyolefin elastomer design.
LG Chem Ltd. is expanding capacity and targeting automotive and specialty elastomers for high-value applications. In a rapidly growing market, capacity expansion is strategically meaningful only when paired with grade differentiation and customer qualification. LG Chem’s focus reflects that broader logic.
SABIC, through SABIC SK Nexlene Company, produces POE with special relevance in advanced materials, including FORTIFY™ encapsulant grades for solar. This highlights an important evolution in the market: POE applications are moving beyond traditional polymer uses into areas where encapsulation, protection, and high-performance processing are critical.
Wanhua Chemical Group Co., Ltd. has moved aggressively on capacity, with a new 200,000 t/yr unit operational since 2024 and plans to expand toward 600,000 t/yr. This is a signal of how regional dynamics are shifting: large-scale capacity additions can change local supply balances quickly, but sustained advantage will depend on how effectively the producer converts volume into qualified demand.
LyondellBasell Industries N.V. operates POE production across multiple regions and supplies elastomers for wire and cable and industrial uses. Its multi-region presence helps support supply continuity and market access, an increasingly important attribute as buyers prioritize resilience alongside cost and performance.
Taken together, these players reveal a market that is simultaneously concentrated and strategically divergent. The leaders are not all competing in the same way. Some emphasize application breadth and global reach, others emphasize regional proximity and specialized grade design, and a third group is scaling capacity for high-volume markets while trying to lift value through targeted applications. This divergence is one of the most important features of the current landscape.
Consolidation is emerging as a central theme in the next stage of market evolution. Capacity rationalization, feedstock strategy alignment, and the push toward higher-value applications all favor consolidation in select chains. At the same time, differentiation is intensifying at the grade level, meaning that the market is not simply becoming more uniform; it is becoming more segmented by performance need, regional requirement, and application qualification. New entrants and capacity expansions can influence local supply, but winning position will depend on downstream relationships, technical service, and grade-level competitiveness.
PolyOlefin Elastomer (POE) Synthetic Materials Market
Forward-Looking Trends and Where Value Is Likely to Concentrate
Looking ahead across the 2026–2032 horizon, three trends appear especially likely to shape commercial outcomes.
Trend one is application migration toward higher-value specifications. POE demand will increasingly come from applications where the material is selected for system-level benefits rather than simple softness or elasticity. Automotive components will continue to be a major demand pool, but the growth logic will depend on lightweighting, part integration, and improved toughness in more complex assemblies. Flexible packaging will remain significant, with additional emphasis on strength, seal performance, and compatibility with evolving packaging formats. In parallel, specialty uses such as advanced encapsulants and performance-critical industrial applications will gain relative importance, especially where material reliability affects product lifetime or safety performance.
This trend creates commercial opportunity for producers and converters who can translate resin properties into application outcomes. It also raises the stakes for qualification: as applications become more demanding, switching costs increase, but so does the need for robust technical support and consistent supply.
Trend two is the alignment of capacity growth with value capture rather than volume alone. Capacity additions are part of the market’s growth story, but the more strategic question is where new tonnage will be directed. The most attractive positions will likely be in grades tied to higher-margin applications, feedstock-advantaged production, and regions where demand growth outpaces local supply. At the same time, regions or segments with oversupply risk will pressure undifferentiated pricing. That means capacity announcements should be read carefully: scale matters, but application selection, ramp-up quality, and customer qualification determine whether scale becomes profitable.
Trend three is regulatory and sustainability-driven specification change becoming a durable competitive factor. If packaging redesign, circularity expectations, and decarbonization pressures continue to intensify, POE grades that fit into more recyclable or more efficient material systems will have a structural advantage. This is not simply a compliance issue; it influences customer willingness to adopt, brand owner preferences, and downstream converter economics. Producers that can present credible pathways for material efficiency, recyclability compatibility, and lower-carbon production may gain access to specifications that are otherwise difficult to win.
These trends also carry risk. Feedstock volatility can erode the economics of expansion plans. Regulatory frameworks may diverge by region, creating complexity for global product rollouts. Demand shifts can alter qualification priorities faster than capacity can be adapted. And concentration in the market means that competitive reactions from leading players can quickly change pricing dynamics in key grades and regions.
Strategic Implications for Decision-Makers
For manufacturers, the immediate priority is to align grade development with application economics, not merely polymer properties. The market increasingly rewards materials that solve a downstream problem: lighter components, better seals, improved durability, improved process efficiency, or better compatibility with evolving sustainability requirements. Manufacturers should also evaluate where capacity and feedstock assumptions create durable advantage versus where they merely add volume. In a market where the top five players already account for 80.0 percent of revenue, incremental growth will often come from stealing application share through superior solution fit, not from taking broad commodity share.
For investors, the key task is to separate capacity announcements from value creation potential. Large expansions can reshape regional supply, but investment merit depends on application mix, qualification status, feedstock positioning, and the ability to protect pricing in the face of competition. The most defensible opportunities are likely in grades and applications where performance requirements are rising and switching costs are meaningful. Investors should also watch consolidation signals and regulatory developments as indicators of where the supply base is heading, since those changes can reshape competitive dynamics well before financial results fully reflect them.
For procurement and sourcing leaders, the strategic imperative is to manage total cost and qualification risk rather than focusing only on resin price. POE is increasingly specified in applications where performance inconsistency or supply disruption carries a high downstream cost. Sourcing strategies should therefore account for grade suitability, supplier technical capability, regional supply resilience, and the ability of suppliers to support evolving sustainability or compliance expectations. Where possible, long-term supply partnerships should be evaluated against the backdrop of application migration and regulatory change, since today’s qualification decisions can lock in advantages or constraints for several years.
Across all of these perspectives, timing matters. The POE market is large enough, and moving fast enough, that broad narratives can obscure important differences in grade-level demand, regional supply balance, and application qualification momentum. Decision-makers who treat POE as a single market risk missing where margins are actually being created. Those who focus on application-driven performance, feedstock and capacity strategy, and the regulatory direction of end markets are more likely to identify durable opportunities before they become crowded.
For a fuller picture of segment-level dynamics, regional demand patterns, capacity timing, and company-specific positioning, the complete study offers the deeper breakdown required for operational planning and investment decisions. In a market defined by concentrated leadership and simultaneous application divergence, detailed intelligence is often the difference between reacting to change and shaping it.
For detailed analysis of this topic, please visit the official page: Polyolefin Elastomers (POE) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


