



Electric Toothbrush Market: How the 6.98% CAGR and Asia Pacific Surge Redefine Growth Beyond 2032

Strategic Trends and Commercial Opportunities in the Electric Toothbrush Market
Market Overview and Core Challenges
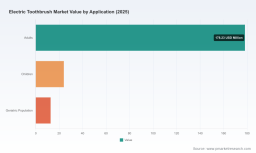
The global electric toothbrush market has demonstrated consistent expansion over the past half-decade, reaching an estimated 215.0 million USD in 2025. Historical growth from 163.15 million USD in 2020 reflects a sustained shift in consumer oral care preferences, while the projected trajectory through 2032 points toward a market approaching 344.8 million USD. This expansion is underpinned by a compound annual growth rate of approximately 6.98 percent, signaling steady but not explosive momentum. The market structure remains relatively fragmented, with the top three players capturing less than a quarter of total revenue and the top five holding just over a quarter. Such concentration levels indicate that no single entity dominates the value chain, leaving meaningful room for differentiation and strategic positioning.
Electric Dental Handpieces Market
Despite the positive trajectory, the industry faces several structural challenges that will shape competitive outcomes over the next cycle. First, the transition from basic cleaning functionality to connected, data-driven oral care is raising the bar for product differentiation. Consumers increasingly expect seamless app integration, personalized brushing feedback, and durable hardware, which compresses margins for generic manufacturers and rewards companies with robust software ecosystems. Second, regulatory complexity continues to constrain speed-to-market. In the United States, electric toothbrushes are classified as Class II medical devices, requiring 510(k) premarket notification clearance. Compliance with ISO 19452:2022 for performance testing, alongside material and chemical standards tied to FDA 21 CFR Part 177 and biocompatibility requirements, adds layers of validation that smaller entrants must navigate carefully. Third, cost structures are bifurcating. Entry-level units now carry manufacturing costs in the range of 6 to 11 USD, while ultra-premium smart devices can reach 31 to 55 USD per unit. This spread forces companies to make deliberate portfolio choices: compete on volume and accessibility, or invest in premium features and validation that justify higher price points.
Key Drivers of Market Evolution
Technological Innovation and Intelligent Oral Care
The most consequential shift in the electric toothbrush space is the migration from mechanical cleaning to intelligent, feedback-enabled hygiene. Sonic technology continues to lead share of attention, but the real value creation lies in how companies embed sensors, pressure monitoring, and app-based coaching into the user experience. Recent product launches illustrate this direction. In March 2026, Royal Philips N.V. introduced two new Philips Sonicare ranges built around next-generation sonic technology, fluid action cleaning, pressure sensors, and app connectivity, signaling a continued emphasis on clinical-style cleaning paired with digital engagement. Earlier, in February 2026, quip expanded its Ultra family with the Ultra Lite Sonic Electric Toothbrush, featuring EasyClick brush pods, a pressure sensor, and extended battery life. The move highlights how design simplicity and modular replacement systems can lower friction for users migrating from manual brushes. In January 2025, Procter & Gamble Co. launched the Oral-B iO2, an oscillating-rotation model positioned for users making the easiest switch from manual brushing, underscoring the importance of onboarding and ease of use in driving conversion.
These developments point to a broader pattern: hardware excellence is becoming table stakes, while differentiation is increasingly driven by software, data, and user journey design. Companies that can translate brushing data into actionable habits, reduce replacement friction, and maintain clinically credible cleaning claims are better positioned to command loyalty and justify premium pricing.
Regulatory and Standards Environment
Regulatory expectations are tightening around performance validation and material safety. Powered toothbrushes must comply with ISO 19452:2022 for test methods that measure performance, and manufacturers must ensure that brush heads and materials meet FDA regulations for medical devices, including biocompatibility testing and FDA 21 CFR Part 177 for food-contact and medical-grade materials. These requirements do not merely add compliance overhead; they shape product architecture, supplier selection, and time-to-market. Firms that standardize testing protocols early, invest in material qualification, and document validation trails can reduce launch risk and build trust with dental professionals and retail partners. The regulatory backdrop also creates an implicit moat: brands that can demonstrate consistent compliance and clinical-style performance claims gain credibility that generic alternatives struggle to replicate.
Consumer Behavior and Demand-Side Shifts
Demand-side dynamics are being reshaped by three interrelated forces. First, oral care is increasingly viewed through a preventive health lens, with consumers and dental professionals alike emphasizing plaque removal, gum health, and consistent technique. This framing supports repeat purchases of replacement heads and encourages adoption among users who previously relied on manual brushes. Second, subscription and refill models are expanding the commercial relationship beyond the initial hardware sale. Modular pod systems, predictable replacement cycles, and bundled accessories create recurring revenue streams and deepen brand touchpoints. Third, eligibility dynamics are evolving. There is growing industry attention around the potential expansion of FSA/HSA eligibility for oral care products, including electric toothbrushes, which would offer consumers additional tax-advantaged spending options and could lower effective purchase barriers for certain segments. Even before formal changes, the conversation signals that oral care devices are increasingly positioned alongside health-related expenditures, reinforcing premiumization and repeat usage narratives.
Cost Structures and Supply Chain Realities
Manufacturing economics are pressuring both ends of the portfolio. At the entry level, cost discipline is essential to maintain acceptable margins while competing on accessibility. At the premium end, the cost of sensors, batteries, app infrastructure, and certification can escalate quickly, requiring careful feature prioritization. The supply base reflects this tension: a mix of established consumer goods manufacturers, dental-focused innovators, and specialized OEM/ODM partners in Shenzhen and surrounding regions offers customization, ISO 13485 and FDA-aligned certifications, and volume flexibility. This ecosystem enables faster iteration and private-label options, but it also raises quality assurance and brand consistency considerations. Companies that invest in supplier qualification, standardized testing, and clear design-to-manufacturing handoffs can reduce variability and protect brand integrity as they scale.
Competitive Landscape and Leading Strategies
The competitive field combines large consumer goods portfolios, dental-adjacent specialists, and a growing cohort of Chinese OEMs and smart-device innovators. Royal Philips N.V. continues to anchor its position around Philips Sonicare, leveraging next-generation sonic technology, fluid action cleaning, pressure sensing, and app connectivity to frame the category around clinical-style cleaning and guided habits. Procter & Gamble Co. competes through Oral-B's oscillating-rotation heritage, with the iO2 launch emphasizing the easiest transition from manual brushing, a strategic focus on reducing adoption friction. Colgate-Palmolive Company positions its electric toothbrushes around oscillating-rotation technology for plaque and stain removal, aligning with its broader oral care distribution strengths. Water Pik, Inc. differentiates by combining sonic oscillation with water flossing capabilities, appealing to users seeking a more comprehensive hygiene routine in a single device.
Smaller and mid-tier players are carving out niches through design, material choice, and smart features. Foreo emphasizes sonic technology with medical-grade silicone bristles for gentle, effective cleaning, targeting users who prioritize soft-tissue comfort. quip focuses on minimalist design, EasyClick brush pods, pressure sensors, and long battery life, lowering the barriers to consistent use. Oclean Technology Co., Ltd. pursues AI coaching, app connectivity, and high-performance sonic oscillation to deliver professional-level feedback, aligning with the intelligence trend. Broxo S.A. maintains a clinical focus on plaque removal and gum health, while Panasonic Corporation offers user-friendly sonic designs that balance performance and accessibility. On the supply side, a network of Shenzhen- and Ningbo-based manufacturers, including Relish Tech, Auxbon, Shenzhen Libai Technology, and several Ningbo and Yueqing producers, provides OEM/ODM capacity with ISO 13485 and FDA-aligned certifications, enabling global brands to iterate quickly and localize offerings.
The landscape is evolving along two parallel tracks. On one hand, consolidation pressure is building as larger players seek to strengthen digital engagement, repeat-purchase models, and clinical credibility. On the other hand, fragmentation persists at the smart-device and OEM level, where rapid iteration, modular designs, and regional manufacturing flexibility allow new entrants to test differentiated value propositions. The strategic implication is clear: scale alone is insufficient. Winning positions will combine credible cleaning performance, compliant materials and testing, a compelling user journey, and a commercial model that captures recurring value after the initial sale.
Future Trends and Commercial Opportunities
Intelligent, Habit-Forming Oral Care
Over the next three to five years, the market is likely to reward products that translate brushing into measurable, coachable habits. Expect tighter integration between hardware sensors and app-based feedback, more refined pressure and coverage metrics, and design choices that reduce friction in replacement and charging. The commercial opportunity lies in pairing hardware with services: subscription refills, personalized recommendations, and dental-professional-aligned guidance that reinforce consistent use. Brands that can demonstrate credible performance while making good habits effortless will be better positioned to retain users and defend premium pricing. The risk is feature creep without corresponding value; overly complex apps or unreliable sensors can erode trust and increase support costs.
Premiumization Paired with Accessibility Tiers
The market is moving toward a dual-structure portfolio strategy. Premium smart devices will continue to target users willing to pay for connectivity, coaching, and refined materials, while entry-level and mid-tier models will compete on reliability, ease of use, and affordability. This bifurcation creates opportunities for tiered branding, modular feature sets, and channel-specific assortments. Manufacturers can use OEM/ODM partnerships to scale distinct tiers efficiently, provided they maintain quality and compliance discipline across the range. The key uncertainty is how quickly reimbursement and tax-advantaged spending dynamics evolve; if FSA/HSA eligibility broadens, it could accelerate adoption in certain segments and shift price sensitivity, while a slower trajectory would keep volume growth dependent on out-of-pocket conversion.
Compliance and Clinical Credibility as Differentiators
As the category matures, regulatory and standards compliance will increasingly function as a differentiator rather than a hurdle. Manufacturers that standardize ISO 19452:2022 testing, maintain rigorous material and biocompatibility documentation, and align brush head materials with FDA expectations will reduce launch risk and strengthen retailer and professional confidence. The opportunity is to use compliance and validated performance as narrative anchors in marketing, retail merchandising, and dental-channel engagement. The downside risk is complacency: incremental changes in material regulations or testing expectations can disrupt product lines if qualification processes are not proactive and well-documented.
Strategic Implications for Decision-Makers
For Manufacturers and Brand Owners
Build a portfolio that explicitly separates accessibility from intelligence. Use modular hardware and replaceable pod systems to reduce long-term friction, and invest in app and sensor design that delivers consistent, understandable feedback. Prioritize compliance infrastructure early, including ISO 19452:2022 testing and material qualification aligned with FDA expectations, so that performance claims and launch timelines remain credible. Evaluate OEM/ODM partners for quality systems, certification coverage, and design-to-production consistency, and use regional manufacturing flexibility to scale tiers without compromising brand standards.
For Investors
Focus on business models that capture value beyond the initial hardware sale. Recurring revenue from refills, subscription pods, and accessories can improve durability of margins and reduce reliance on cyclical replacement cycles. Assess whether a company's differentiation rests on defensible features—credible cleaning performance, compliant materials, and engaging software—rather than transient marketing claims. Pay attention to regulatory readiness and supplier qualification, as these factors increasingly influence launch speed and retail access. Monitor the reimbursement conversation as a potential catalyst that could shift effective price sensitivity in select markets.
PW Consulting
For Procurement and Channel Partners
Prioritize suppliers with documented compliance trails, standardized performance testing, and clear material specifications. Consistency across batches and regions matters as much as unit cost, particularly for premium SKUs where brand trust and professional recommendation drive repeat purchases. Evaluate replacement-system design and battery life as practical determinants of customer satisfaction and return rates. Where possible, structure contracting to ensure quality assurance, certification continuity, and transparent testing documentation, reducing the risk of downstream compliance or performance issues.
The electric toothbrush market is entering a phase where growth is increasingly defined by how well companies convert hardware capability into sustained user behavior, credible performance, and compliant, repeatable operations. For decision-makers seeking deeper segmentation data, pricing dynamics, and customized go-to-market guidance, the full PW Consulting research report provides the granular detail needed to translate these trends into specific commercial moves.
Power Toothbrush Market
For detailed analysis of this topic, please visit the official page: Electric Toothbrush Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


