



Vector Network Analyzer Market: Why 3.38% CAGR and 67% CR3 Redefine Strategic Outlook

Vector Network Analyzer Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The Vector Network Analyzer (VNA) market operates at the intersection of precision measurement and high-frequency engineering, serving as a critical enabler for telecommunications, aerospace engineering, and advanced electronics manufacturing. After a period of steady expansion, the market reached approximately 0.44 billion USD in 2025, building on a trajectory that saw moderate growth through the early 2020s. Over the forecast horizon through 2032, the market is projected to advance at a compound annual growth rate of 3.38 percent, with revenue scaling toward 0.56 billion USD by the end of the period. This growth profile reflects a mature, specialized instrumentation sector where incremental expansion is tied closely to broader technological adoption cycles rather than standalone product demand.
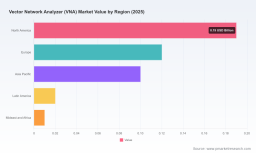
Market concentration remains notably high, with the top three participants commanding roughly two-thirds of total revenue and the top five players accounting for approximately 84 percent. This concentration underscores the technical barriers to entry, the importance of established calibration and certification ecosystems, and the long procurement cycles typical of enterprise and institutional buyers. At the same time, the distribution of revenue across technology classes and end-use sectors reveals where the market’s weight truly sits. Lower-frequency instruments in the 0-to-10 GHz range dominate share, while higher-frequency segments above 50 GHz remain relatively small in absolute terms but strategically important for next-generation applications. Communications continues to represent the largest application bucket, with automotive, electronic manufacturing, and aerospace and defense each contributing meaningful but more modest shares. Regionally, North America leads in revenue contribution, followed by Europe and Asia Pacific, with Latin America and the Middle East and Africa representing smaller but emerging pockets of activity.
Worldwide 5G Analyzer Market
Against this backdrop, three core challenges define the current inflection point. First, the cost and complexity of high-frequency development create a persistent barrier. Designing and calibrating VNAs for operation above 15 GHz demands substantial research and development investment, while premium components and high-speed data acquisition systems further increase production expenses. These cost dynamics constrain product accessibility and place pressure on vendors to justify performance premiums in customer conversations. Second, the market must navigate a shifting compliance and standardization environment. As RF testing becomes more tightly integrated into 5G, IoT, and Industry 4.0 deployment requirements, precision and traceability are no longer optional attributes; they are procurement prerequisites. Accredited calibration laboratories and standardized measurement protocols are increasingly baked into purchasing decisions, raising the stakes for both established players and new entrants. Third, the market faces a segmentation tension between broad-coverage, mid-range instruments and specialized high-frequency or portable solutions. Buyers want flexibility, but vendors must balance feature expansion against size, weight, power, and cost constraints. Solving this tension will separate growth-oriented vendors from those stuck in the middle.
Key Drivers Shaping Market Direction
Technological Innovation and Measurement Capability Expansion
Innovation in VNA architectures is expanding what practitioners can measure in the field and in the lab. Recent product moves illustrate this trajectory clearly. In September 2024, Keysight Technologies introduced the NA520xA PNA-X Vector Network Analyzer, configured with four RF sources, two internal combiners, and two low-noise receivers. This configuration reflects a broader push toward multi-dimensional characterization, where faster sweep capability, improved signal-to-noise performance, and integrated test configurations reduce the need for external mixing hardware. For engineering teams, such architectures translate into shorter test cycles and more compact bench setups, which matters as product development timelines tighten across communications and electronic manufacturing.
A complementary innovation thread is the extension of VNA functionality into field-portable instruments. In May 2025, Anritsu added Vector Network Analyzer and Vector Voltmeter measurements to its Site Master field portable instruments. This move blurs the line between bench-grade analysis and on-site troubleshooting, enabling technicians to capture vector-level data outside controlled laboratory environments. The strategic implication is significant: as deployment and maintenance activities move closer to real-world infrastructure, portable precision becomes a differentiator rather than a niche convenience.
Beyond individual product launches, two structural cost and capability dynamics continue to shape innovation incentives. High development and calibration costs for high-frequency operation above 15 GHz require substantial R&D investment, reinforcing the advantage of vendors with deep component expertise and established calibration infrastructure. At the same time, premium components and high-speed data acquisition systems increase production expenses, which keeps price-performance positioning under constant scrutiny. Vendors that can modularize performance, offer tiered configurations, or shift complexity toward software and calibration workflows are better positioned to absorb these cost pressures while preserving margin.
Policy, Regulation, and the Calibration Imperative
Regulatory and standards-driven expectations are increasingly shaping procurement behavior. Precision RF testing is now tightly coupled to compliance requirements in 5G, IoT, and Industry 4.0 applications, making VNAs essential tools for demonstrating that devices meet spectral, impedance, and linearity expectations. This is not merely a technical requirement; it is a commercial one. Buyers in regulated industries and supply chains are more likely to require evidence of traceable measurements, accredited calibration support, and documented measurement integrity.
This environment rewards vendors with recognized calibration ecosystems. For example, calibration laboratories associated with major instrumentation providers have been accredited in accordance with the ISO/IEC 17025 standard, reinforcing the value of standardized, auditable measurement workflows. For enterprise buyers, such accreditation reduces risk in qualification processes and simplifies supplier evaluation. For vendors, it creates a defensible moat: once a calibration and compliance pathway is embedded in a customer’s procurement process, switching costs rise, and relationship durability improves.
Demand-Side Shifts Across Communications, Automotive, and Advanced Manufacturing
Demand growth is being shaped less by any single application surge than by the broadening use of RF characterization across multiple sectors. Communications remains the largest application anchor, driven by continuous network evolution and the need to validate antenna systems, filters, and front-end components. Yet the more strategically interesting story is the diffusion of VNA use into adjacent domains. Automotive electrification and advanced driver-assistance systems increase the need for component and subassembly validation. Electronic manufacturing relies on VNAs for quality assurance and process control as circuit designs become more sensitive to impedance mismatches and parasitic effects. Aerospace and defense continue to represent a steady, requirements-driven demand base where high-reliability measurement and traceability are non-negotiable.
A parallel demand-side shift is the growing preference for deployable measurement solutions. Field technicians, line engineers, and distributed test teams increasingly expect instruments that are lighter, easier to power, and simpler to calibrate in non-ideal environments. This is where smaller-footprint, USB-powered, and calibration-module-supported designs gain relevance. The demand signal is not that every application requires a portable solution, but that a meaningful subset of use cases rewards reduced setup burden and faster time to measurement. Vendors that align product portfolios to this operational reality can open new customer segments without necessarily competing head-to-head in flagship laboratory instruments.
Supply Chain and Cost Structure Dynamics
The VNA market is affected by the same broader considerations that influence precision electronics: component availability, manufacturing complexity, and the cost of maintaining high performance at elevated frequencies. Premium components and high-speed data acquisition systems raise production expenses, while high-frequency calibration and validation compound the cost of bringing products to market. These factors do not necessarily cap growth, but they do shape how growth is captured. Vendors with stronger supply chain leverage, more efficient calibration workflows, and the ability to standardize subsystems across product families can better manage cost inflation and preserve competitive pricing.
At the same time, the market’s concentration pattern suggests that scale advantages matter. With the top five participants representing a substantial majority of revenue, established players can amortize R&D, calibration infrastructure, and support operations across broader installed bases. Newer or smaller vendors must therefore find defensible positions through specialization, portability, ease of use, or targeted application support rather than attempting to out-invest incumbents across the full performance spectrum.
Competitive Landscape and Leading Strategies
Positioning Among the Leading Participants
The market’s leadership group reflects distinct strategic emphases, each aligned to different buyer priorities. Keysight Technologies continues to emphasize high-performance bench architectures, with its NA520xA PNA-X and VectorStar/Streamline families positioning around multi-source flexibility and advanced receiver configurations. The strategic signal here is clear: Keysight is investing in measurement depth and configuration versatility for customers who prioritize characterization speed, signal integrity, and laboratory-grade performance. Its September 2024 introduction of the NA520xA PNA-X, with four RF sources, two internal combiners, and two low-noise receivers, reinforces an emphasis on reducing external hardware dependencies while expanding in-line test capability.
Rohde & Schwarz takes a different posture, focusing on broad frequency coverage and multiport scalability with offerings such as the ZNBT and ZVA families, including multiport VNAs extending up to 1.1 THz. This positions the company strongly in applications where frequency range, port density, and system integration matter more than compact portability. For buyers scaling test systems or requiring high-frequency coverage for advanced materials and component characterization, this breadth becomes a central value proposition.
Copper Mountain Technologies has carved out a pragmatic, accessibility-oriented position with 1-port and 2-port USB-powered VNAs supported by calibration modules. The strategic appeal lies in lower total cost of ownership, simpler deployment, and easier integration into distributed or resource-constrained environments. Rather than competing on extreme frequency or multi-source complexity, this approach targets customers who value fast setup, portability, and straightforward calibration workflows. It is a useful reminder that the market does not reward a single winning formula; it rewards fit-to-use-case.
Worldwide Vector Network Test Instrument Market
Anritsu combines field-portable capability with bench-class measurement expansion. Its VNA Master series and VectorStar/ShockLine families span a range of performance needs, while the May 2025 addition of Vector Network Analyzer and Vector Voltmeter measurements to Site Master field portable instruments illustrates a deliberate push to bring vector-level insight into field environments. This dual orientation gives Anritsu credibility in both installation/commissioning contexts and more detailed component characterization, allowing it to serve customer journeys that span lab and field.
How the Competitive Map Is Evolving
The landscape is not static. Several dynamics are reshaping how competition plays out. One is the continued consolidation of value among established players who can fund high-frequency R&D, sustain calibration infrastructure, and maintain global support networks. With market concentration already high, the Near-term question is less about dramatic market share rebalancing and more about how incumbents defend their positions through product refresh cycles, application-specific packaging, and service-grade differentiation.
A second dynamic is the emergence of sharper segmentation. Portable and field-deployable solutions are gaining visibility, while high-frequency laboratory systems remain essential but demanding. In between, vendors are experimenting with software-defined calibration, modular configurations, and tiered performance bundles. This suggests a market that is gradually moving away from one-size-fits-all positioning toward a portfolio logic where product families are designed around distinct workflows: bench characterization, field troubleshooting, production line verification, and specialized high-frequency research.
PW Consulting
A third dynamic is the role of compliance and certification as a competitive lever. In a market where measurement integrity is directly tied to product acceptance and regulatory alignment, vendors that can offer accredited calibration support and standardized documentation gain an advantage in enterprise and institutional sales cycles. This does not eliminate competition, but it raises the bar for entry and rewards organizations that treat calibration and traceability as strategic assets rather than back-office functions.
Outlook: Three Trends That Will Shape the Next 3 to 5 Years
Trend 1: Precision Testing Becomes Embedded in Broader Technology Deployment Cycles
VNA demand will increasingly be linked to the deployment cadence of 5G-related infrastructure, IoT scale-up, and Industry 4.0 automation. As these environments mature, the need for repeatable, traceable RF characterization will move from project-stage validation to ongoing maintenance and quality assurance. For vendors, this means opportunity lies not only in selling instruments but in enabling recurring workflows: calibration services, software-supported measurement routines, and application content that helps customers integrate VNAs into standard operating procedures. The commercial upside is sticky relationships and broader usage across the product lifecycle. The risk is that buyers may treat measurement as a commodity if differentiation is limited to hardware specifications alone.
Trend 2: Field-Portable and Accessible Form Factors Will Expand the Addressable User Base
Instrumentation that reduces setup burden, power requirements, and calibration complexity will continue to open opportunities beyond traditional laboratory buyers. USB-powered architectures, portable field instruments with vector-level capability, and calibration modules that simplify on-site workflows all point toward broader adoption among technicians, field engineers, and distributed production teams. This trend creates room for growth even in a market with modest overall CAGR, because it expands who can use VNAs and where they can be used. The risk is that ease-of-use offerings must still meet enough performance expectations to be trusted in serious characterization tasks. If portability comes at the expense of measurement credibility, adoption will stall.
Trend 3: High-Frequency and Multi-Port Capabilities Will Remain Strategic, Not Mass-Market
Above-50 GHz measurement and advanced multiport configurations will continue to matter disproportionately for certain applications, even if they represent a smaller share of total market revenue. In aerospace and defense, advanced materials research, and select communications roadmap items, high-frequency performance is a gating requirement. Vendors that can sustain leadership here will protect premium positions and high-value customer relationships. At the same time, the cost and complexity of high-frequency development above 15 GHz will keep this segment concentrated among players with strong R&D capacity and calibration maturity. The strategic opportunity is to use high-frequency leadership as an anchor for credibility while competing in broader segments through more accessible product tiers. The uncertainty is that demand for extreme-frequency instrumentation can be lumpy and dependent on specific program cycles, which makes revenue timing less predictable.
Strategic Implications for Decision Makers
For Instrument Manufacturers and Technology Providers
Product strategy should be guided by a clearer separation of use cases. High-performance laboratory systems, field-portable tools, and accessible mid-range instruments are not interchangeable; they solve different problems and carry different cost structures. Rather than stretching a single platform to cover every requirement, vendors can gain advantage by designing families that align with distinct buyer workflows and then integrating them through software, calibration support, and application documentation. Equally important is treating calibration and compliance support as marketable capabilities. In a market where measurement integrity influences purchasing decisions, accredited calibration pathways and standardized documentation can be as strategically relevant as raw frequency specifications. Finally, managing cost pressures from premium components and high-speed data acquisition will require disciplined modular design, shared subsystems, and efficient calibration processes.
For Investors and Strategic Partners
The VNA market offers stability more than explosive expansion, which makes selection of exposure points especially important. Given high concentration, the most direct path to market participation often runs through established players with strong calibration infrastructure, broad application coverage, and diversified product families. However, the most interesting differentiation may come from enabling layers: portable form factors, field-ready measurement workflows, software-assisted calibration, and application-specific packages that reduce friction for non-specialist users. Investment logic should therefore weigh not only headline revenue trajectory but also how well a company is positioned to capture value from recurring workflows, service attachment, and segmentation-driven expansion. The key uncertainty is that demand in high-frequency and program-driven segments can be uneven, so momentum should be evaluated across multiple application streams rather than a single headline driver.
For Procurement Leaders and Engineering Decision Makers
Purchasing decisions should begin with workflow reality rather than maximum specification. The right VNA choice depends on whether the priority is laboratory characterization depth, field portability, production line throughput, or compliance documentation. Buyers should assess not only instrument performance but also calibration support, accreditation alignment, and the practical burden of setup and maintenance. In regulated or supply-chain-sensitive environments, measurement traceability and standardized documentation can materially affect qualification risk. It is also worth considering total cost of ownership over the instrument lifecycle, including calibration, support, and the operational time required to bring the system into productive use. A slightly less ambitious specification that is easier to deploy and maintain can often deliver better business value than a higher-specification instrument that underutilizes its capabilities.
Closing Perspective
The Vector Network Analyzer market is entering a phase where growth will be shaped less by raw specification escalation than by how effectively vendors connect measurement capability to real-world deployment, compliance, and operational simplicity. The market’s steady expansion through 2032, combined with high concentration and clear segmentation across frequency ranges and applications, suggests a sector where differentiation will come from workflow fit, calibration credibility, and the ability to serve both laboratory and field environments. For manufacturers, the opportunity lies in portfolio logic and service-grade differentiation. For investors, the opportunity lies in identifying exposure to recurring value and accessible adoption pathways. For buyers, the opportunity lies in matching instrument capability to actual use cases while reducing qualification and maintenance risk.
Detailed segmentation data, regional and application-level revenue splits, company-level market share context, and forward scenarios are available in the full PW Consulting research report. That deeper dataset can support more precise sizing, competitor positioning analysis, and customized recommendations tailored to specific product plans, investment theses, or procurement requirements.
For detailed analysis of this topic, please visit the official page: Vector Network Analyzer (VNA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


