



Bimetallic Bandsaw Blade Market: Why 6.5% CAGR Reshapes Steel Cutting Growth to $860M

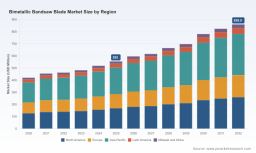
Navigating the Bimetallic Bandsaw Blade Market: Strategic Trends and Commercial Opportunities Through 2032
The global market for bimetallic bandsaw blades has entered a sustained growth trajectory, valued at approximately $555 million in 2025 and projected to expand at a compound annual growth rate of 6.5%, reaching nearly $860 million by 2032. This expansion is not merely a function of incremental industrial demand but reflects a structural shift in how manufacturers approach material processing, precision machining, and operational efficiency. Over the past half-decade, revenue climbed from $420.5 million in 2020 to $555.0 million in 2025, with consistent year-over-year gains signaling resilient underlying fundamentals. By 2028, the market is expected to surpass $664 million, and the upward momentum will continue through the end of the decade as automation, energy optimization, and advanced alloy requirements reshape procurement criteria. Understanding the forces converging on this niche but strategically vital segment is essential for executives, investors, and procurement leaders who must align positioning, capital allocation, and supply strategies with where the market is heading.
Two structural inflection points define the current landscape. First, the transition from general-purpose cutting tools to application-specific, high-performance blade architectures is accelerating, driven by tighter tolerances in metal fabrication, increased use of hardened alloys, and the need to minimize downtime in continuous production environments. Second, the industry is experiencing a concentration dynamic where a relatively small group of established manufacturers controls the majority of revenue, creating both a barrier for undifferentiated entrants and an opportunity for companies that can differentiate through tooth geometry, backing material engineering, or integrated service models. These forces do not simply shape pricing and shelf space; they redefine the competitive battlefield, where performance consistency, lifecycle value, and alignment with automated sawing systems increasingly outweigh commodity cost competition.
Key Drivers Shaping Market Trajectory
Technical Innovation and Material Science Breakthroughs
The durability and cutting performance of bimetallic bandsaw blades depend directly on the interaction between the high-speed steel cutting edge and the flexible alloy backing. Recent material developments have reinforced this value proposition. High-speed steel grades rich in molybdenum have advanced at a notable pace, strengthening wear resistance and heat tolerance in demanding metal cutting scenarios. This progression supports longer blade life, more stable cutting parameters, and reduced frequency of blade changes, which in turn lowers total cost of ownership for high-volume operations. Alongside alloy improvements, manufacturers are refining tooth geometry, set patterns, and substrate bonding processes to optimize chip evacuation, reduce vibration, and improve cut finish across varying material thicknesses. The practical implication is clear: blade selection is shifting from a transactional purchase to a performance engineering decision, with procurement teams weighing throughput, scrap rates, and machine compatibility alongside unit price.
Regulatory and Operational Pressures Toward Efficiency
Energy efficiency mandates and broader sustainability expectations in industrial operations are reshaping tooling choices. Metal cutting processes that consume less power per cut, maintain stable performance over extended runtimes, and reduce waste are increasingly favored in facilities subject to efficiency monitoring or carbon accountability frameworks. Bimetallic blades that deliver consistent cutting speeds with lower resistance and fewer remachining cycles align well with these priorities. Beyond energy, labor dynamics are influencing adoption patterns. Shortages of skilled operators in manufacturing environments have accelerated the uptake of automated bandsaw systems that rely on reliable bimetallic blades to sustain unmanned or semi-autonomous production runs. In this context, blade reliability becomes a bottleneck or an enabler of automation ROI, making performance predictability a strategic procurement criterion rather than a secondary specification.
Band Saw Blades Market
Market momentum is also reinforced by application diversity. Steel cutting remains a core demand center, supported by structural fabrication, maintenance, and heavy equipment production. Aluminum cutting continues to draw volume from automotive, aerospace, and general manufacturing workflows, where clean cuts and minimal material deformation are valued. Cast iron cutting serves niche but critical requirements in foundry and machinery remanufacturing contexts, while additional applications span specialized alloys and mixed-material processing. This breadth provides revenue resilience, as demand is not overly dependent on a single vertical, and it encourages blade suppliers to maintain differentiated product lines tailored to material-specific cutting characteristics.
Competitive Landscape and Strategic Positioning
Established Leaders and Differentiation Logic
The market features a mix of long-standing Western manufacturers and emerging Asian producers, each pursuing distinct routes to advantage. Companies such as Lenox Tools, M.K. Morse Company, and DoALL Sawing Products have built reputations around application-specific bi-metal blades for metal cutting, with product lines oriented toward high-production environments and general-purpose versatility. L.S. Starrett Company emphasizes advanced tooth geometry and geometry optimization to improve cut quality and blade stability, while Bahco positions around production-focused series designed for sustained cutting operations. German manufacturers bring specialized engineering depth: Wikus offers modified cutting materials and alloyed steel backing for alloyed steel applications, Eberle focuses on duoflex architectures for stainless steel, high-speed steel, and cast iron, and Honsberg targets a broad range of industrial applications with bimetal solutions. Simonds International LLC supports production, general-purpose, and structural steel cutting segments, rounding out a competitive field where brand trust, technical service, and consistent quality are central to customer retention.
On the supply side, Bichamp Cutting Technology Co Ltd represents the expanding presence of Chinese manufacturers focused on high-performance metal cutting, leveraging scale, cost competitiveness, and increasing technical capability to serve both domestic and export markets. This dynamic creates a bifurcated competitive environment: premium segments remain contested by manufacturers emphasizing engineering depth, application-specific performance, and service integration, while value-oriented segments face pressure from producers able to combine acceptable performance with lower procurement costs. The result is a market where differentiation is increasingly tied to measurable outcomes—blade life, cut consistency, compatibility with automated systems, and technical support—rather than brand alone.
Recent Industry Activity and Market Evolution
Company activity over the past year underscores the emphasis on application expansion, customer engagement, and technology visibility. In early 2025, Wikus hosted a targeted industry event focused on innovation for efficient steel processing, signaling a strategic interest in aligning blade performance with demanding production requirements. Later in the year, the company participated in trade shows highlighting bimetal bandsaw blades and sawing solutions for industrial sheet metal processing, and presented a bimetal blade tailored for wood industry applications, illustrating how manufacturers are exploring adjacent end-use contexts to broaden demand pools. These moves reflect a broader trend: leading players are not only refining core metal-cutting offerings but also testing cross-industry applicability, strengthening dealer and user relationships, and using live demonstrations to communicate performance advantages in concrete operating conditions.
PW Consulting
The competitive trajectory points toward modest consolidation in the premium tier, as larger manufacturers seek to broaden application coverage and strengthen regional distribution, while smaller or specialized producers may find growth by focusing on niche applications, custom geometries, or localized service networks. New entrants face a steep climb given the concentration of revenue among established names, but they can still carve positions through rapid customization, cost-efficient manufacturing, or targeted service offerings for underserved geographies and applications. The landscape is therefore evolving along two parallel paths: consolidation and brand elevation in high-value segments, and fragmentation with specialized solutions in niche or price-sensitive contexts.
Forward Outlook: Trends and Commercial Implications
Trend One: Automation-Ready Blades as a Standard Expectation
As automated and semi-autonomous bandsaw systems become more prevalent in response to labor constraints and throughput goals, blade specifications will increasingly be evaluated for compatibility with consistent feed rates, reduced variability, and extended runtime between changes. Manufacturers that design blades with automation in mind—stable cutting behavior, predictable wear patterns, and clear performance envelopes—will be better positioned to capture demand from facilities scaling automated sawing capacity. For suppliers, this creates an opportunity to bundle blades with system integration guidance, application engineering, and maintenance planning, shifting the conversation from unit price to uptime and process reliability.
Trend Two: Material-Specific Engineering as a Value Driver
Demand for differentiated performance across steel, aluminum, cast iron, and other materials will continue to reward suppliers that can deliver application-tuned tooth geometry, set design, and backing material characteristics. As more producers encounter mixed-material workflows or harder alloys, the ability to match blade architecture to material properties will become a decisive purchasing factor. This trend favors companies that invest in application testing, provide clear selection frameworks, and communicate lifecycle performance data. Commercial opportunity lies in developing documented performance benchmarks and helping customers translate material requirements into blade choices that reduce trial-and-error procurement.
Trend Three: Cost Structure Dynamics and Supply Chain Resilience
The interplay between raw material pricing, alloy availability, and manufacturing efficiency will remain central to margin management and pricing strategy. With certain high-speed steel grades trending upward in cost, producers must balance input cost pressures against the value delivered through longer service life and reduced downstream waste. Supply chain resilience—spanning specialty alloy sourcing, bonding process control, and logistics—will differentiate companies that can maintain consistent quality and delivery from those exposed to volatility. The strategic implication is straightforward: competitive advantage will accrue to firms that can stabilize input costs through forward sourcing, optimize manufacturing yield, and articulate total cost of ownership benefits that justify performance premiums where appropriate.
These trends carry both opportunity and uncertainty. On the opportunity side, the convergence of automation, efficiency mandates, and application-specific engineering expands the rationale for premium blade adoption and creates openings for service-led business models. On the risk side, macroeconomic swings in industrial production, fluctuations in alloy availability, and intensifying price competition in value segments could pressure margins and slow adoption in price-sensitive regions. Geopolitical factors affecting trade flows and raw material supply may also influence regional cost structures and availability, requiring flexible sourcing and clear communication of supply continuity plans.
Strategic Takeaways for Decision Makers
For blade manufacturers and tooling suppliers, the priority is to convert technical differentiation into commercially legible value. This means investing in application-specific validation, documenting performance outcomes in terms that procurement and operations teams can use, and aligning product roadmaps with automation compatibility and material-specific needs. Companies should also evaluate where service, technical support, and selection guidance can strengthen customer retention, particularly in markets where blade longevity and cut consistency directly affect production economics. Where cost competition is intense, clear positioning around total cost of ownership, downtime reduction, and application fit can help defend margins without resorting to undifferentiated price competition.
For investors evaluating exposure to this segment, the relevant signals are the durability of demand across multiple applications, the pace of automation-driven adoption, and the ability of leading manufacturers to sustain differentiation through engineering and service rather than volume alone. Concentration in the market suggests that scaled players with strong brand equity and application coverage may capture disproportionate share of incremental growth, while specialized or regionally focused companies can still generate attractive returns if they serve underserved applications or maintain a credible cost-to-performance ratio. Due diligence should assess supply chain exposure to specialty alloys, the credibility of performance claims, and the extent to which product portfolios are aligned with the shift toward automated and efficiency-conscious operations.
For procurement and operations leaders, the practical imperative is to treat blade selection as a process decision rather than a commodity purchase. Evaluating blades against actual material mixes, machine configurations, and throughput targets can reveal where higher-performance options reduce total cost through longer life, fewer cut defects, and better automation compatibility. Establishing clearer selection criteria, testing application-specific options in representative conditions, and engaging suppliers for technical guidance can improve procurement outcomes and reduce variability in sawing performance. In environments where energy efficiency, labor constraints, and production consistency matter, the blade choice can influence more than cutting quality; it can affect overall operating economics.
For organizations seeking a deeper dive into segment-level sizing, regional demand patterns, application split trends, and company-specific positioning, a comprehensive research report provides the granularity needed to translate these strategic themes into concrete plans. Detailed breakdowns by region, application, and type, along with company profiles and recent development tracking, enable more precise market-entry decisions, pricing strategies, and procurement frameworks. Accessing that level of detail allows decision makers to convert broad market direction into targeted actions, whether the goal is to expand product coverage, enter a new geography, refine a procurement specification, or assess investment exposure with greater confidence.
Worldwide Welded Band Saw Blades Market
For detailed analysis of this topic, please visit the official page: Bimetallic Bandsaw Blade Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


