



Leather Goods Market 2026–2032: How 7.2% CAGR and Genuine Leather Lead Demand Shifts

Leather Goods Market: Strategic Trends and Commercial Opportunities Through 2032
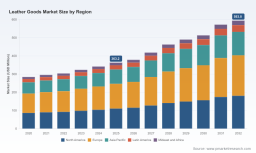
The global leather goods market is navigating a period of structural transformation, shaped by evolving consumer expectations, regulatory pressures, and shifting trade dynamics. Valued at 363.2 million USD in 2025, the sector has expanded steadily from 284.5 million USD in 2020, reflecting a compound annual growth rate of approximately 7.2 percent through 2032. This trajectory signals a market that is no longer driven solely by volume expansion but by fragmentation of demand, material innovation, and intensifying competition across regional and product boundaries. For executives and investors, the question is no longer whether the market will grow, but how value will be captured amid rising costs, compliance complexity, and changing sourcing behaviors.
PW Consulting
Three structural challenges define the current inflection point. First, raw material volatility is compressing margins while forcing reallocation of sourcing strategies. Second, regulatory divergence across major markets is altering compliance costs and product positioning, particularly around material disclosure and end-of-life responsibility. Third, trade policy uncertainty is reshaping export competitiveness for manufacturing hubs that rely on cross-border supply chains. These pressures are not isolated; they interact with consumer preferences and technological adoption, creating a landscape where agility in sourcing, positioning, and compliance will separate resilient operators from those caught in cost or reputation traps.
Within this context, the market concentration profile indicates that scale remains a meaningful advantage, yet differentiation is increasingly achieved through specialization rather than breadth alone. The leading firms are not simply expanding output; they are aligning with distinct demand segments, building provenance narratives, and adapting to material transitions while maintaining quality expectations. The following analysis examines the forces driving this reshaping, the competitive logics emerging among core players, and the strategic implications for manufacturers, investors, and procurement teams.
Market Landscape and Core Challenges
The leather goods sector has demonstrated resilient growth through a recent expansion cycle, with the 2025 base position cementing a path toward sustained double-digit cumulative value creation over the forecast window. This growth is underpinned by durable demand for footwear, bags, and accessories, though the composition of that demand is shifting in ways that matter for strategy. The market is large enough to support multiple business models, but the distribution of opportunity is uneven across regions and product categories, and the benefits of scale are increasingly contingent on operational flexibility and compliance readiness.
The first core challenge is raw material cost pressure. Leather input costs have become a recurring headwind, affecting manufacturers that depend on traditional tanning and slaughter-linked supply chains. This pressure is not merely cyclical; it reflects tightening environmental scrutiny, supply concentration in specific sourcing regions, and the broader cost of managing waste, water, and chemical inputs. For producers, the implication is that cost mitigation can no longer rely on procurement timing alone. It increasingly requires formulation alternatives, yield optimization, and selective material substitution without eroding perceived value.
The second challenge is regulatory fragmentation. Compliance requirements are diverging across jurisdictions, creating a more complex operating environment for brands and manufacturers that sell across borders. Disclosure expectations for imitation and hybrid materials are tightening, while extended producer responsibility considerations are emerging in major consumer markets. These developments raise the stakes for transparency, labeling accuracy, and lifecycle management, particularly for firms that position themselves on authenticity or premium quality. The risk is not only enforcement exposure but also brand trust erosion when material claims and product realities diverge.
The third challenge is trade and tariff uncertainty. Tariff structures affecting leather and allied products have become a persistent factor in export competitiveness, influencing where goods are manufactured, assembled, and shipped. As tariff levels and trade flows remain sensitive to policy shifts, manufacturers with concentrated export exposure face margin variability and sourcing reconfiguration pressure. This environment favors companies that can modularize production, diversify destination markets, or align manufacturing footprints with customer risk tolerance.
Key Drivers Shaping the Market
Material Innovation and Positioning Tension
One of the most consequential drivers is the ongoing tension between genuine leather and faux leather positioning. Genuine leather continues to command the largest share of market value, rooted in durability perceptions, craftsmanship narratives, and the premium associations many consumers attach to animal-derived materials. At the same time, synthetic and alternative materials are gaining ground in segments where price sensitivity, ethical positioning, or weight and maintenance considerations matter more than traditional material prestige.
This is not simply a substitution story. It is a segmentation and communication challenge. Brands that rely on leather as a value signal must manage disclosure expectations and consumer interpretation carefully, especially where products may contain blends or where visual appearance resembles leather. Regulatory guidance requiring disclosure of non-leather content for products that appear leather reinforces the need for clearer material storytelling and more disciplined product claims. For manufacturers, this creates an opportunity to offer verified material grading, traceable sourcing, and coordinated messaging that reduces ambiguity and supports premium pricing where justified.
Regulatory and Compliance Dynamics
Policy and regulatory activity is becoming a strategic variable rather than a background compliance cost. In the United States, tariff levels on leather and allied product manufacturing have averaged above 18 percent, with trade reports indicating potential further adjustments. These levels affect landed cost calculations and influence how brands evaluate make-versus-source decisions across geographies. For export-oriented manufacturers, tariff exposure can determine whether a given sourcing model remains viable for a specific customer base.
In parallel, environmental policy is moving toward lifecycle accountability. A proposed national Extended Producer Responsibility scheme for leather goods in Italy signals a broader direction in which end-of-life responsibility, material recovery, and waste management may become integrated into product economics. Even where such schemes are still in draft or early implementation stages, they shape investment decisions because manufacturers and brands must anticipate compliance costs and consumer expectations around sustainability. The direction of travel suggests that environmental compliance will increasingly interact with brand positioning, especially in premium segments where provenance and responsibility claims are part of the purchase rationale.
Bovine Leather Goods Market
Demand-Side Shifts and Consumer Behavior
Consumer demand is evolving along multiple axes at once. Lifestyle and hobby-related spending patterns are shifting, influencing how discretionary purchases are prioritized across footwear, bags, and accessories. At the same time, product launches in the premium and fashion-forward space continue to emphasize limited editions, collaborative design, and region-specific craftsmanship. Recent product activity illustrates this dynamic: limited-edition leather jackets and handbags developed through brand collaborations, and timeless bag collections designed in one market and manufactured in another to leverage specialized material and production heritage.
The strategic implication is that demand is becoming more occasion-specific and story-driven. Consumers are not simply buying a category; they are buying into a narrative of rarity, design intent, and material authenticity. This favors manufacturers and brands that can coordinate design, sourcing, and limited production runs with credible craftsmanship signals. It also creates pressure on mass-market players to justify value through durability, repairability, or transparent material claims, rather than relying on volume alone.
Supply Chain Reconfiguration and Cost Structure Evolution
Trade uncertainty is reshaping how supply chains are configured for leather goods. Export competitiveness in key manufacturing regions is affected by tariff exposure, logistics variability, and the broader cost of maintaining cross-border production networks. In this environment, some operators are shifting toward regional or near-customer manufacturing, while others are preserving offshore advantages but building more flexible routing and inventory strategies.
Cost structures are also changing through raw material dynamics and compliance expenditures. When input costs rise, manufacturers that can protect yield, reduce waste, and offer consistent quality gain relative advantage. When compliance complexity rises, firms that can standardize disclosure, manage material documentation, and anticipate regulatory change reduce the cost of market access. Together, these factors reward operators that treat supply chain design as a strategic asset rather than a fixed cost base.
Competitive Landscape and Strategic Positioning
The competitive field in leather goods is shaped by contrasting business models that reflect regional advantage, customer type, and material philosophy. Several core companies illustrate how differentiation is being constructed in practice.
TBS Group, based in Vietnam, has built a dedicated handbag division serving major international brands, producing leather handbags, wallets, and accessories for clients that include Coach, Tory Burch, and Skechers. Its positioning reflects the advantages of a manufacturing hub with scaling capacity and brand-facing execution, where the value proposition rests on reliable volume, specification adherence, and the ability to serve global brand programs.
Guangzhou Gionar Leather Co., Ltd. in China emphasizes OEM and ODM capabilities across high-end leather handbags, backpacks, briefcases, wallets, and belts. This model targets brands and buyers that need design support alongside manufacturing, making the company relevant for customers seeking a single partner for development and production. The strategic logic is integration of service depth with category breadth.
Wollsdorf, operating from Austria, focuses on premium leather steering wheel products and leather goods, an example of specialization in a niche but high-perception category. Its positioning depends on quality, fit, and the prestige associated with refined interiors and driver-focused craftsmanship. The company illustrates how narrow category focus can support premium pricing when execution and brand context align.
Keifung-intl, headquartered in Hong Kong, manufactures fashion handbags and small leather goods with private label programs for European and American brands. Its relevance lies in combining manufacturing capability with brand-service orientation, supporting label-driven businesses that need consistent output and commercial flexibility.
Leather Country, based in Italy, operates a B2B wholesale model for leather handbags, belts, wallets, and accessories. Its positioning leverages Italian material heritage and wholesale distribution, serving buyers who value material reputation and assortment breadth. In a market where origin signals matter, this model uses geographic association as part of the offering.
On the luxury and heritage side, Lotuff Leather in the United States produces handmade vegetable-tanned leather handbags and luxury goods with a lifetime guarantee. Frank Clegg Leatherworks, also U.S.-based, focuses on ultra-luxury briefcases, travel gear, and executive leather products. Horween Leather Co. supplies premium American vegetable-tanned leather for custom goods. These firms represent a different axis of competition: durability, repairability, and long-term value claims rather than speed or scale. Their advantage lies in craftsmanship reputation, material philosophy, and customer relationships built around longevity.
The market is evolving along two reinforcing trends. First, consolidation pressures are emerging where scale, compliance capacity, and supply chain resilience provide advantages in serving large brand programs and export markets. Second, fragmentation is strengthening at the premium and specialty end, where differentiation comes from material authenticity, limited production, and narrative-driven design. New entrants and expanding producers are likely to compete not by replicating the same model, but by choosing a clear position: volume and service integration for brand clients, or craftsmanship and provenance for luxury and heritage demand. Trade fair activity across the sector, from footwear and leather goods exhibitions in Europe and Asia to sourcing-focused events in the Middle East, underscores the continued importance of in-person networking, specification alignment, and regional sourcing relationships.
Future Outlook: Trends and Opportunities to 2032
The next three to five years are likely to be defined by three interconnected trends.
The first trend is the intensification of material transparency as a commercial norm. Disclosure expectations and consumer scrutiny will continue to raise the cost of ambiguity. Products that appear to be leather but contain significant non-leather content will face greater scrutiny, and brands will need more rigorous material documentation and labeling discipline. The opportunity here is for manufacturers and suppliers that can offer verified material grades, traceable sourcing, and clear communication frameworks. Transparency, when executed credibly, can become a trust asset rather than a compliance burden.
The second trend is the continuing divergence between mass-market value competition and premium durability positioning. Rising costs and trade uncertainty will pressure margins in volume segments, while premium segments will increasingly reward craftsmanship, repairability, and long-life product claims. This divergence creates distinct commercial opportunities: efficiency-driven sourcing and modular production for scale customers, and limited runs, material heritage, and lifetime service promises for high-value customers. Companies that attempt to occupy both spaces without clear operational separation may struggle to defend either position.
The third trend is supply chain adaptation to regulatory and tariff volatility. Manufacturers and brands will continue to adjust footprints, routing, and sourcing mixes in response to trade policy and compliance evolution. Regional diversification, closer coordination with buyers on landed-cost tolerance, and investment in documentation and compliance processes will become more valuable. The opportunity lies in building supply chain flexibility that can respond to policy shifts without sacrificing quality or delivery reliability.
These trends carry risk. If raw material costs remain elevated and tariff or trade disruptions intensify, margin compression could accelerate in export-dependent models. If regulatory expectations expand faster than compliance capabilities, brands and manufacturers could face both cost and reputation exposure. If consumer preferences shift more quickly toward alternative materials in core categories, traditional leather positioning may need to be recalibrated around performance, provenance, or service rather than material alone.
Actionable Guidance for Decision Makers
For manufacturers, the priority is to choose a defensible positioning and build the operating capabilities that support it. Volume-oriented producers should invest in yield efficiency, compliance documentation, and flexible sourcing to protect margins under tariff and input-cost pressure. Specialty and premium producers should reinforce material credibility, craftsmanship signals, and service commitments such as repair or guarantee structures that support long-term value perception. In both cases, the ability to provide clear material disclosure and consistent quality will increasingly determine market access and pricing power.
Leather Market
For investors, the key is to assess exposure to the structural drivers rather than rely on category-level growth alone. Evaluate whether a company's model is aligned with transparency requirements, whether its supply chain can absorb tariff and trade variability, and whether its positioning is distinct enough to resist commoditization. Businesses that combine regulatory readiness with a clear value proposition, whether in scale service or premium craftsmanship, are better placed to capture value across the forecast period.
For procurement and brand teams, sourcing strategy should account for both cost and narrative alignment. Where leather is used as a value signal, verify material claims, disclosure practices, and supplier documentation. Where price or ethical considerations drive material choices, ensure that alternative materials are positioned with consistent claims and that product appearance does not create misleading consumer expectations. Building supplier relationships that can support traceability, compliance, and design collaboration will reduce risk and improve optionality as demand patterns continue to shift.
The market trajectory through 2032 will reward operators that treat transparency, compliance, and positioning as integral to commercial strategy rather than as downstream considerations. For decision makers seeking more granular segmentation data, regional breakdowns, and tailored sourcing or investment implications, the full PW Consulting research report provides expanded detail across market segments and competitive scenarios.
For detailed analysis of this topic, please visit the official page: Leather Goods Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


