



Mercury Analyzer Market: Why 6.58% CAGR and Environmental Monitoring Reshape Growth

Navigating the Mercury Analyzer Market: Strategic Trends and Commercial Opportunities in an Era of Shifting Compliance
The global mercury analyzer market stands at a critical inflection point. As of 2025, the sector commands a total revenue base of approximately USD 353.78 million, having grown from USD 258.75 million in 2020. The market is projected to reach USD 551.95 million by 2032, reflecting a compound annual growth rate of 6.58 percent over the 2026–2032 forecast horizon. This trajectory signals more than steady demand; it reflects a structural recalibration driven by tightening environmental mandates, evolving pharmaceutical quality standards, and a growing emphasis on real-time trace-element detection across industrial and regulatory workflows.
Behind these headline figures lies a market that is moderately concentrated yet highly fragmented in terms of application needs and technological preferences. The top three players account for roughly 52.3 percent of revenue, while the top five capture 78.5 percent, indicating that scale advantages and established certification footprints matter, but niche specialization and regional compliance alignment continue to create room for focused competitors. The commercial landscape rewards organizations that can pair detection reliability with regulatory readiness, deployment flexibility, and total-cost-of-ownership clarity.
1. Market Landscape and Core Challenges
The mercury analyzer market has evolved from a compliance-driven, laboratory-centric procurement category into a broader instrumentation domain spanning continuous emissions monitoring, food safety screening, petrochemical process control, and pharmaceutical impurity testing. Revenue expansion over the 2020–2025 period was propelled by sustained investment in environmental monitoring networks, incremental replacement of aging analytical systems, and rising adoption of automated sample-handling workflows that reduce operator dependency. The forecast period extends this momentum, but the growth path is no longer uniform across regions or end-use segments.
Three core challenges define the current operating environment and will shape how companies position themselves over the next several years.
- Regulatory divergence creates a two-speed demand environment. While certain jurisdictions are reinforcing mercury emission limits and expanding monitoring requirements for waste incineration and coal-fired facilities, other markets have pulled back or deferred stricter standards. This divergence means that demand growth is increasingly conditional on local policy trajectories rather than global harmonization. Manufacturers and buyers alike must navigate uneven compliance calendars, which complicates capacity planning, product roadmaps, and aftermarket service models.
- Technology trade-offs between sensitivity, portability, and total cost of ownership. End users increasingly weigh detection limits and method robustness against deployment complexity, maintenance burden, and workforce training requirements. Laboratory-grade systems offer high precision and automation, while portable and field-deployable platforms expand reach but can introduce trade-offs in throughput, calibration stability, or consumables usage. The challenge for suppliers is to deliver demonstrable performance without inflating operating costs, and for buyers to match instrument class to actual monitoring frequency and compliance risk.
- Supply chain and consumables dependency in trace analysis. Mercury analysis at trace levels relies on specialized reagents, calibration standards, gold-based trapping components, and tightly controlled sample introduction workflows. Volatility in component availability, reagent pricing, and service-part lead times can affect uptime and operating budgets. In addition, buyers are increasingly scrutinizing vendor lock-in risks, particularly where proprietary sample preparation or consumables are tied to instrument performance claims.
These challenges are not barriers to growth so much as filters that separate reactive suppliers from strategically positioned ones. Organizations that anticipate regulatory variability, design for serviceability, and articulate clear operating economics are better placed to capture share in a market where purchasing decisions are increasingly tied to risk management rather than unit price alone.
2. Key Demand Drivers
Technological Innovation and Breakthroughs
Advances in atomic absorption and fluorescence detection architectures continue to shape purchasing decisions. Cold vapor atomic absorption systems remain the dominant product segment, favored for their combination of sensitivity, automation potential, and cost-effectiveness in routine laboratory and continuous emissions monitoring applications. At the same time, cold vapor atomic fluorescence techniques are gaining attention where ultra-trace detection and reduced interferences are prioritized, particularly in specialized environmental and research settings.
The broader technology story is less about a single breakthrough and more about convergence: improved vaporization control, better background correction, more robust software workflows, and greater integration with sample preparation and data management systems. These improvements reduce manual intervention, support audit-ready records, and make it easier for labs and field teams to standardize methods across sites. For suppliers, differentiation increasingly comes from workflow completeness, not just detector performance.
Moisture Analyzer Market
Policy and Regulatory Environment
Regulatory dynamics remain the most powerful driver of instrument demand, but they are also the most uneven. Tightening global mercury-emission limits under the revised EU Industrial Emissions Directive and China’s GB 13223-2011 standard are accelerating demand for real-time mercury detection in waste incinerators and coal plants. In parallel, Minamata Convention ratification and enforcement in Europe, China, and Japan sustain instrument replacement cycles across regulated facilities, as existing systems age and compliance expectations rise.
At the same time, the US EPA’s 2026 repeal of strengthened Mercury and Air Toxics Standards creates a two-speed growth trajectory, with slowed coal-utility upgrades in North America relative to regions where emission limits continue to tighten. This divergence does not eliminate demand in North America; it rebalances it toward other applications, including environmental monitoring programs, industrial hygiene, and non-coal emission sources. For decision makers, the implication is that regulatory exposure must be mapped at the jurisdiction and facility level rather than assumed from regional averages.
Demand-Side Shifts in Customer Behavior
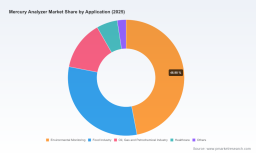
Demand is broadening beyond traditional environmental laboratories. Pharmaceutical quality-control laboratories face long-term demand signals from ICH Q3D elemental-impurity limits, which require trace mercury analysis as part of broader contamination-control programs. Food industry stakeholders continue to invest in screening and verification workflows for mercury in seafood and other high-risk matrices, driven by both regulatory scrutiny and brand-protection considerations. In the oil, gas, and petrochemical sector, mercury monitoring supports catalyst protection, process integrity, and emissions management, creating demand for both laboratory and process-adjacent measurement solutions.
A notable behavioral shift is the growing preference for solutions that reduce method variability and documentation burden. Procurement teams are increasingly evaluating vendors on certification alignment, method compatibility, and the ability to support multi-site consistency, not solely on instrument price. This shift favors suppliers that can demonstrate regulatory readiness and repeatable performance across diverse sample types.
Supply Chain and Cost Structure Evolution
Cost structures in the mercury analyzer market are being reshaped by the interplay of instrument durability, consumables intensity, and service-model design. Buyers are paying closer attention to total cost of ownership, including calibration frequency, replacement-part availability, reagent consumption, and the cost of downtime during critical compliance windows. Suppliers that offer modular service designs, longer calibration intervals, or more efficient sample-introduction pathways can gain an edge, especially in operations where labor and throughput are constrained.
Recent commercial activity reinforces this focus on practical deployment and user enablement. Lumex Instruments has continued to invest in user-facing engagement, including plans to exhibit at analytica 2026 in Munich and the delivery of a RA-915-Series mercury analyzer technical training course in Chile in late 2025. These moves reflect a broader industry pattern in which manufacturers extend their reach through demonstrations, training, and localized support rather than relying on specification sheets alone. Nippon Instruments Corporation’s September 2025 contract with the US Geological Survey for delivery of a MA-1001 Model MA-2000 Mercury Analyzer also illustrates how public-sector and specialized research procurement can validate platform credibility and create reference-value effects in adjacent markets.
3. Competitive Landscape and Leading Strategies
The competitive field combines established multinational instrument manufacturers with specialized players that have built strong positions around specific detection methods, application segments, or regulatory certifications. The market’s moderate concentration suggests that incumbency matters, but it does not guarantee dominance across all use cases. Instead, competitive advantage tends to emerge from alignment between technology choice, compliance documentation, service reach, and application expertise.
PW Consulting
Several strategic positioning patterns are visible among leading participants.
Water Quality Analyzer Market
- Method-specialized leadership. Companies that concentrate on cold vapor atomic absorption or cold vapor atomic fluorescence platforms often compete on method familiarity, certification alignment, and repeatability across routine analyses. This focus can make it easier for laboratories and monitoring programs to standardize methods and train operators, especially where regulatory methods are well established.
- Portable and field-deployable strength. Portable mercury analyzers and vapor monitors appeal to environmental field teams, industrial hygiene programs, and rapid-screening applications. In this segment, differentiation often comes from ruggedization, battery or transport logistics, ease of calibration, and the ability to deliver defensible results outside controlled laboratory conditions.
- Continuous monitoring and compliance-oriented platforms. Suppliers offering continuous mercury emissions monitoring systems and ultra-trace industrial analyzers target facilities where compliance reporting and process visibility depend on sustained measurement rather than periodic sampling. Here, value is tied to integration with plant data systems, service availability, and the ability to withstand demanding emission environments.
- Broad-platform and ecosystem positioning. Larger scientific-instrument manufacturers can leverage wider analytical portfolios, service networks, and software ecosystems to provide mercury analysis as part of integrated testing programs. This approach can be attractive to organizations that prefer consolidated vendor relationships, standardized data workflows, and cross-application support.
Specific company footprints illustrate these patterns. Lumex Instruments emphasizes Zeeman atomic absorption mercury analyzers such as the RA-915M series and portable Light 915 models, positioning around field and laboratory flexibility. Mercury Instruments GmbH focuses on portable mercury analyzers, vapor monitors, and process instruments for environmental and industrial applications, aligning with on-site monitoring needs. Teledyne Leeman Labs offers laboratory and environmental elemental analysis solutions such as Hydra II and QuickTrace systems, appealing to organizations that require trace metal analysis within broader environmental testing workflows. ENVEA GmbH provides continuous mercury CEMS monitoring and ultra-trace industrial analyzers for emissions compliance, targeting regulated facility operators. Nippon Instruments Corporation supplies direct mercury analyzers and series designed for regulatory compliance applications, including models commonly associated with standardized elemental analysis workflows. Thermo Fisher Scientific Inc. offers stack emissions monitoring solutions for coal-fired and waste incinerator applications, reinforcing a compliance-oriented industrial position. PerkinElmer Inc. integrates mercury analysis systems into atomic spectroscopy and environmental testing platforms, supporting laboratories that value broader spectroscopic ecosystems. Brooks Rand Instruments emphasizes advanced mercury analyzers and speciation systems certified to US EPA methods, an appealing differentiator for customers whose compliance requirements are closely tied to recognized regulatory methods.
How the Landscape Is Evolving
Three evolutionary themes are shaping the market’s trajectory. First, consolidation pressure is likely to persist among suppliers seeking to expand service coverage, strengthen regulatory documentation, or acquire application-specific expertise. Second, differentiation is moving toward application readiness, including method certification support, software integration, and service-level assurance, rather than detector specifications alone. Third, new entrants and niche specialists can still gain footholds by targeting underserved applications, regional compliance needs, or particular sample matrices where existing platforms create friction.
For buyers, this environment rewards structured vendor evaluation. The most attractive suppliers are not necessarily those with the broadest portfolios; they are those that can demonstrate reliable performance in the specific compliance context, sample type, and operating environment that matter most to the buyer. For suppliers, the strategic imperative is to reduce friction in procurement, installation, training, and ongoing compliance support, because these factors increasingly determine repeat business and reference value.
4. Forward Trends and the Opportunities They Create
A More Jurisdiction-Specific Demand Map
Over the next three to five years, demand is likely to become more explicitly mapped to jurisdiction-specific compliance calendars and facility-level risk profiles. In regions where emission limits continue to tighten, continuous monitoring upgrades and replacement cycles should remain robust. In markets where regulatory momentum has slowed, demand may shift toward environmental monitoring programs, pharmaceutical impurity testing, food safety verification, and non-coal industrial sources. This pattern creates an opportunity for organizations that can flex their commercial messaging and deployment models by region and application, rather than relying on a single growth narrative.
The associated risk is that policy reversals or compliance delays can compress near-term demand in specific segments, particularly where capital planning has been tied to anticipated regulatory changes. Companies that depend heavily on a narrow set of regulated end-users may experience more volatile order pipelines than those with diversified application exposure.
Workflow Integration as a Commercial Differentiator
Instrument performance will remain essential, but commercial advantage will increasingly depend on how well mercury analysis fits into broader laboratory or plant workflows. Expectations are rising around method standardization, data traceability, automated reporting, and compatibility with existing quality systems. Solutions that reduce manual steps, simplify audit preparation, and support multi-site consistency will be better positioned to win in procurement environments where total cost of ownership and operational risk are weighed alongside detection limits.
This trend favors suppliers that invest in software usability, service documentation, training, and integration support. It also creates opportunities for partnerships with organizations that can bundle analytical capability with sample handling, data management, or compliance consulting. The risk is that buyers may become more intolerant of platforms that require significant customization or ongoing specialist intervention to produce compliant results.
Expansion of Portable, Field, and Ultra-Trace Use Cases
Demand for portable and field-deployable mercury measurement is likely to continue expanding where rapid screening, incident response, site characterization, and distributed monitoring are priorities. At the same time, ultra-trace analysis will remain important in applications where low detection limits and interference management determine acceptability. The commercial opportunity lies in matching instrument class to use case with clarity, so that buyers avoid over-specifying laboratory systems for field needs or under-specifying field tools for compliance-grade monitoring.
A related opportunity is service-led growth. As installed bases age and regulatory expectations rise, aftermarket support, calibration services, training, and replacement-part availability become more strategic. Suppliers that build credible service models can create recurring revenue streams and deepen customer relationships, particularly in markets where compliance downtime carries meaningful financial or reputational consequences. The main uncertainty is that service expectations are rising faster than some organizations can scale trained personnel and parts logistics, which could create gaps that better-organized competitors are able to exploit.
5. Strategic Actions for Decision Makers
The mercury analyzer market offers genuine growth potential, but the most valuable opportunities will go to organizations that act with clarity about where compliance, technology, and operational reality intersect. The following actions can help different stakeholder groups translate market dynamics into practical decisions.
For Manufacturers and Suppliers
- Align product roadmaps with the applications most likely to see sustained demand, including environmental monitoring, pharmaceutical impurity control, food safety screening, and industrial emissions compliance, rather than betting primarily on a single regulatory storyline.
- Strengthen differentiation through workflow completeness: method documentation, training, service availability, calibration practicality, and integration with customer data systems. These factors increasingly influence repeat purchase and reference adoption.
- Plan for regional variability in compliance momentum by building flexible deployment models, localized support capabilities, and clear messaging for both laboratory and field-use scenarios.
For Investors and Corporate Development Teams
- Evaluate exposure not just by market size, but by end-use mix and regulatory sensitivity. Diversified application portfolios may provide more stable growth than heavy dependence on a narrow set of compliance-driven customers.
- Pay attention to service and consumables economics, as these often determine long-term margin durability and customer retention in trace-analysis instrumentation.
- Look for value creation in companies that combine credible method alignment with strong user enablement, because these attributes can support pricing power and installation momentum in a moderately concentrated market.
For Procurement and Operational Leaders
- Match instrument selection to the actual compliance context, sample matrix, and monitoring frequency rather than to generic performance claims. Over-specification can raise costs without improving compliance outcomes, while under-specification can create audit or operational risk.
- Evaluate total cost of ownership holistically, including calibration demands, consumables, service response times, training burden, and the operational impact of downtime during critical monitoring periods.
- Prioritize vendors that can demonstrate method compatibility, certification alignment, and consistent multi-site performance, especially where standardized reporting and audit readiness are important.
The market’s next phase will reward organizations that treat mercury analysis as part of a broader compliance and operational strategy rather than as a standalone equipment purchase. Detailed segmentation data, application-level demand patterns, and company-specific positioning can materially improve planning quality, particularly when decisions involve multi-year capital allocation, service-model design, or market-entry choices. For teams that need a deeper factual base before committing resources, a full market research report can provide the granular breakdown and structured scenario detail that high-stakes decisions warrant.
For detailed analysis of this topic, please visit the official page: Mercury Analyzer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


