



PA66 Engineering Plastics Market: Automotive Demand’s 2.4% CAGR Trajectory Beyond 2026

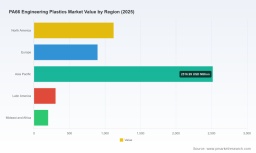
PA66 Engineering Plastics Market: Strategic Trends and Commercial Opportunities in a Maturing Landscape
The global market for PA66 engineering plastics has entered a phase of measured expansion, characterized by steady volume growth, intensifying sustainability mandates, and structural shifts in end-use demand. Valued at approximately 5.04 billion USD in 2025, the market has navigated a volatile post-pandemic recovery period, with revenues climbing from roughly 4.12 billion USD in 2020 to an estimated 5.04 billion USD by 2025. Forecasts project a compound annual growth rate of 2.4 percent through 2032, a pace that reflects both the material's entrenched role in high-performance applications and the headwinds reshaping industrial plastics markets. Rather than signaling stagnation, this moderate growth trajectory underscores a maturation cycle where value creation increasingly depends on differentiation, supply chain resilience, and alignment with regulatory and customer expectations.
Several converging forces are redefining how PA66 is produced, priced, and deployed. Feedstock dynamics continue to exert pressure on cost structures, while downstream industries are demanding materials that balance performance with lower environmental impact. Simultaneously, the competitive landscape remains highly concentrated, yet innovation cycles are accelerating among both incumbent producers and specialty compounders. For executives evaluating portfolio strategies, investment allocation, or sourcing decisions, the PA66 segment presents a nuanced picture: baseline demand remains anchored in automotive and electrical applications, yet the real strategic leverage lies in how companies navigate feedstock volatility, regulatory shifts, and the push toward circular production pathways.
Engineering Plastics (PBT, PA6 & PA66) Market
Core Challenges at an Inflection Point
The market's current trajectory is shaped by three interconnected challenges that demand strategic attention rather than passive adaptation.
Supply Chain and Feedstock Volatility. The production of PA66 relies heavily on adipic acid and hexamethylene diamine, creating inherent exposure to chemical intermediate pricing and regional supply disruptions. Price movements in key regions have already demonstrated this sensitivity, with Asian market prices declining from approximately 2,566 USD per metric ton in early 2025 to around 2,383 USD per metric ton by mid-year. While downward pressure may appear favorable for downstream users, such fluctuations often reflect broader imbalances in intermediate availability, energy costs, and regional demand cycles. The result is a planning environment where cost predictability remains elusive, forcing manufacturers and compounders to hedge against margin compression while maintaining competitive pricing for end customers.
Regulatory and Pricing Pressure Escalating. Regulatory frameworks and corporate sustainability commitments are no longer peripheral considerations; they are becoming direct cost and operational drivers. Recent pricing adjustments by major producers highlight this shift, with notable increases applied to related polyamide families and intermediates in North America. Beyond immediate cost implications, such moves signal an industry grappling with the financial realities of compliance, feedstock sourcing standards, and the capital required to transition toward lower-carbon production routes. Companies that treat regulatory pressure solely as a cost center risk falling behind competitors who are embedding sustainability into product design and supply chain architecture.
Demand-Side Transformation in Core End Markets. Automotive and electrical/electronics applications continue to anchor PA66 demand, yet the nature of that demand is evolving. Vehicle architectures are shifting toward electrification and lightweighting, altering component requirements and material specifications. In electrical applications, higher thermal stability and durability are becoming non-negotiable as power density and miniaturization increase. These shifts do not diminish the relevance of PA66; they raise the performance bar. Suppliers that rely on undifferentiated standard grades face growing pressure from both advanced polyamide variants and alternative engineering materials.
Key Drivers Shaping the Market
Beneath the surface of moderate headline growth, several structural drivers are determining where value will accrue over the next five years.
Technology Innovation and Material Performance
Innovation in additive technology and material formulation is expanding the functional envelope of PA66. Recent introductions of advanced additive packages have demonstrated measurable improvements in thermal stability and mechanical performance, directly addressing the demands of under-hood automotive components and high-load electrical systems. Such enhancements matter because they extend the viable application range of PA66, allowing it to compete in environments where end users previously considered higher-cost or alternative high-performance polymers. For market participants, the strategic implication is clear: performance differentiation is increasingly tied to formulation expertise rather than resin supply alone. Compounders and resin producers that invest in application-specific optimization can command premium positioning and deepen customer lock-in.
A parallel wave of innovation is emerging around recycling and feedstock substitution. The development of chemical recycling processes capable of complete depolymerization of nylon 66 is significant because it opens the door to closed-loop material flows, reducing reliance on virgin intermediates and addressing scope 3 emissions concerns across the value chain. When paired with the use of bio-circular feedstocks derived from waste streams, these approaches are reshaping the cost and carbon profile of PA66 production. Early movers that secure certification and scale these pathways are positioning themselves to meet procurement requirements from customers with stringent sustainability targets.
Policy and Regulatory Environment
Policy dynamics are exerting dual pressure on the PA66 market: cost-side adjustments and demand-side incentives. Regulatory-driven price adjustments across polyamide families indicate that producers are recalibrating for compliance costs, energy inputs, and the financial weight of sustainability commitments. At the same time, broader decarbonization policies and industrial efficiency mandates are influencing procurement criteria in automotive and electrical sectors. Customers are increasingly embedding carbon intensity, recyclability, and certified sustainable sourcing into supplier evaluation frameworks. This regulatory environment favors producers and compounders that can provide transparent lifecycle data and verified sustainable production credentials, while raising the barrier for operators that lack differentiated environmental attributes.
Demand-Side Evolution and End-Use Requirements
Consumer and enterprise behavior is reshaping material specifications, particularly in mobility and electrical infrastructure. The ongoing transition toward electrified vehicles is driving requirements for components that withstand higher temperatures, reduce system weight, and support longer service life. In electrical and electronics applications, the push for compact, high-reliability assemblies is elevating the importance of thermal resistance and dimensional stability. These trends reinforce the structural role of engineering plastics, but they also shift competitive dynamics toward grades that meet stricter performance thresholds. Demand is not simply expanding; it is upgrading. Companies that align product portfolios with these evolving requirements are better positioned to capture growth in high-value niches, while those offering only commoditized grades face pressure on both volume and margin.
Supply Chain and Cost Structure Dynamics
Cost structures across the PA66 value chain are being recalibrated by feedstock movements, regional pricing disparities, and strategic price actions by leading producers. Price adjustments in North America for related polyamide intermediates and polymers reflect the reality that upstream cost pressures are being passed through the chain. Concurrently, regional price declines in Asia point to localized demand and supply dynamics that can diverge significantly from global averages. The net effect is a fragmented cost environment where geographic sourcing strategies, inventory management, and long-term supply agreements carry heightened importance. For manufacturers, resilience is becoming as valuable as price competitiveness. Diversifying feedstock access, securing stable intermediate supply, and leveraging regional production footprints can mitigate exposure to volatility and protect margin stability during periods of market fluctuation.
Competitive Landscape and Strategic Positioning
The PA66 market remains concentrated, with a small group of integrated producers and specialist compounders accounting for the majority of industry revenue. This concentration reflects the scale and technical complexity required to produce engineering-grade PA66 reliably, as well as the long-term customer relationships built around performance consistency and application support. However, the landscape is not static. Strategic differentiation is increasingly defined by sustainability credentials, formulation capability, and the ability to serve specialized end markets rather than by volume alone.
Worldwide Polyimide Engineering Plastics Market
Several leading players illustrate distinct strategic postures. Fully integrated producers with large-scale PA66 operations emphasize vertical integration and feedstock control, leveraging that foundation to supply a broad range of engineering resins and compounds. Their advantage lies in production scale, consistency, and the capacity to support high-volume automotive and industrial applications. Other global leaders in PA66 polymers and intermediates focus on supplying resins that serve engineered plastics applications across multiple regions, competing on reliability, technical service, and breadth of grade offerings. European producers bring strong recognition in premium engineering polymers and compounds, often emphasizing specialized grades tailored to demanding mechanical and thermal requirements. Swiss and Dutch manufacturers contribute high-performance polyamide grades aimed at structural and thermal applications, reinforcing a market segment where application-specific performance outweighs commodity pricing considerations. Major chemical producers with broad polyamide portfolios extend their reach through both PA66 and copolymer grades, allowing them to address adjacent performance tiers and offer customers alternatives when design constraints or cost targets shift.
Recent developments highlight how these players are translating strategy into action. Initiatives to produce PA66 using bio-circular feedstocks have demonstrated measurable reductions in carbon footprint and achieved recognized sustainability certification, signaling a credible pathway toward lower-impact production. Product launches introducing enhanced additive packages and advanced heat-resistant grades show direct responses to the performance demands of electrified and high-temperature applications. Meanwhile, proprietary chemical recycling processes that enable complete depolymerization and reuse point toward a longer-term shift in how nylon 66 materials can be cycled back into production. Collectively, these moves illustrate an industry where competitive advantage will increasingly depend on the integration of performance innovation with sustainable sourcing and manufacturing.
Market Structure Evolution
Looking ahead, market structure is likely to evolve along three axes. First, consolidation pressure may continue among mid-tier producers as scale, compliance costs, and sustainability investments raise the bar for competitive viability. Second, differentiation will deepen between producers offering standard commodity-adjacent grades and those providing application-engineered solutions with verified sustainability attributes. Third, new entrants and technology-driven players may gain relevance in niche recycling, bio-feedstock conversion, and specialty compounding, even if they do not displace incumbents in bulk resin supply. The result is a market where strategic positioning matters more than ever: value will migrate toward participants that can combine reliable supply, performance optimization, and credible environmental credentials.
Future Trends and Commercial Opportunities
Several trends are likely to define the PA66 market over the next three to five years.
PW Consulting
Trend One: Sustainability as a Structural Requirement, Not a Differentiator. Bio-circular feedstocks, recycled-content pathways, and certified sustainable production are transitioning from optional credentials to baseline expectations in many procurement processes. Commercial opportunities will emerge for producers and compounders that can scale credible, certified sustainable grades and provide transparent documentation for customer reporting. The risk for laggards is exclusion from tenders and long-term supply agreements, particularly in automotive and electrical segments where corporate sustainability targets are increasingly binding.
Trend Two: Performance-Grade Shift in Core Applications. As electrification and high-density electronics continue to advance, demand will tilt toward grades with higher thermal stability, improved mechanical retention, and tailored compound formulations. This shift creates opportunity for suppliers that invest in application-specific development and close collaboration with component designers. The uncertainty lies in the pace of adoption and the extent to which alternative materials or higher-performance polyamide families capture share in the most demanding niches.
Trend Three: Regional Cost and Supply Fragmentation. Diverging regional pricing, feedstock availability, and regulatory environments will make global standardization more difficult. Companies that build flexible sourcing strategies, regional production leverage, and long-term partnership structures will be better equipped to manage volatility and secure supply. The risk is over-reliance on single-region sourcing or failure to anticipate localized price and availability shifts, which can erode competitiveness during periods of market imbalance.
Actionable Guidance for Decision-Makers
The current market environment rewards proactive strategy over reactive adjustment. For manufacturers, the priority is to align product portfolios with performance and sustainability requirements that are becoming standard in automotive and electrical applications. This means accelerating formulation expertise, investing in grades that address thermal and mechanical demands, and developing credible sustainable production pathways that can be verified through recognized certification. Where possible, expanding application-specific compound offerings can create pricing power and customer stickiness that offset commodity pressure on base resin margins.
For investors, the opportunity lies in identifying operators with clear differentiation strategies, resilient feedstock positioning, and credible sustainability roadmaps. Volume growth alone is unlikely to drive superior returns in a market growing at a moderate pace; value creation will favor companies that capture premium segments through performance innovation and sustainable sourcing. Due diligence should weigh feedstock integration, recycling and bio-feedstock capability, regulatory exposure, and the ability to serve high-specification end markets rather than focusing solely on top-line expansion.
For procurement and sourcing leaders, the strategic imperative is to move beyond price-only evaluations and incorporate supply resilience, sustainability credentials, and technical support into supplier selection. Diversification across regions and suppliers, long-term agreements that account for feedstock volatility, and preference for partners with verified sustainable production can reduce exposure to disruption while aligning with corporate decarbonization goals. As regulatory and customer expectations continue to tighten, procurement decisions will increasingly influence both cost stability and organizational compliance posture.
Navigating these dynamics requires detailed, current intelligence on volume trajectories, regional pricing behavior, end-use demand shifts, and the competitive actions of leading producers. A comprehensive research report can provide the granular segmentation, scenario-based forecasts, and supplier-level insights needed to translate these strategic themes into operational decisions. For organizations seeking a deeper view of the PA66 engineering plastics market, including detailed breakdowns by region, type, and application along with customized guidance for specific business contexts, the full study offers the depth required to move from high-level trends to execution-ready strategy.
For detailed analysis of this topic, please visit the official page: PA66 Engineering Plastics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


