



Tank Cleaning Service Market: Why 6.5% CAGR and Asia Pacific's Lead Reshape Strategy

The Tank Cleaning Service Market: Navigating Growth, Regulation, and Technological Transformation (2025–2032)
1. Market Context and Structural Challenges
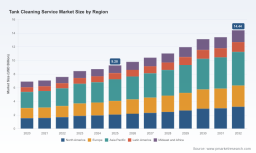
The global tank cleaning service industry has entered a phase of steady expansion, valued at approximately $9.28 billion in 2025. Over the 2020–2025 period, the market demonstrated consistent year-over-year growth, reflecting the sector's fundamental role in maintaining operational efficiency, regulatory compliance, and asset integrity across energy, chemical, and industrial sectors. Current projections indicate the market will reach $14.44 billion by 2032, reflecting a compound annual growth rate of 6.5 percent from 2026 through 2032. This trajectory signals a market that is not merely expanding in absolute terms but is also undergoing a structural shift in how cleaning operations are delivered, regulated, and integrated into broader industrial workflows.
At first glance, the growth story appears straightforward: aging storage infrastructure, rising throughput volumes, and stringent environmental mandates all demand more frequent and more thorough cleaning cycles. Yet beneath the headline numbers lie several structural bottlenecks that will determine which operators capture value and which face margin compression or operational disruption.
The first critical challenge centers on the tension between labor availability and operational safety. Tank cleaning has historically been a high-touch, entry-intensive process requiring specialized crews to navigate confined spaces, manage hazardous residues, and adhere to rigorous atmospheric testing protocols. Recent enforcement actions by occupational safety regulators underscore the reality that noncompliance carries severe financial and reputational consequences. A notable case involved a proposed penalty exceeding $800,000 against a service provider for failing to conduct required atmospheric testing before worker entry, following a prior incident that resulted in dual fatalities. This episode is not an outlier; it illustrates a broader industry reality where safety protocols, permit administration, exposure limits for hydrocarbon vapors and oxygen concentrations, and confined space entry requirements are becoming non-negotiable operational prerequisites. For service providers, the implication is clear: scaling capacity without scaling safety infrastructure and compliance expertise is no longer viable.
The second challenge involves the uneven pace of technological adoption. While automated and robotic cleaning systems have demonstrated measurable improvements in throughput, residue recovery, and worker exposure reduction, their deployment remains uneven across geographies and customer segments. Facilities with high-value throughput, complex sludge profiles, or strict environmental reporting requirements are increasingly willing to invest in or contract automated solutions. However, many mid-tier and regionally focused operators continue to rely on manual or semi-automated processes, constrained by upfront capital considerations, workforce familiarity, and the perceived complexity of integrating new equipment into existing maintenance cycles. This divergence creates a two-speed market where service quality, cost structures, and compliance postures increasingly diverge between early adopters and laggards.
The third challenge relates to margin stability in an environment of rising input costs and evolving waste-handling requirements. Cleaning operations do not end when tanks are emptied; they extend into sludge processing, residue disposal, and, in many cases, advanced contaminant management. As regulatory expectations around hazardous waste classification, transport logistics, and specialized treatment pathways tighten, operators must absorb higher downstream costs or pass them through to customers in a market where procurement teams are increasingly scrutinizing service-level agreements and total cost-of-ownership metrics. The result is a market where pricing power increasingly belongs to providers who can demonstrate integrated service capabilities rather than isolated cleaning transactions.
These challenges are not debilitating; they are shaping the market's next phase. They create differentiation opportunities for operators who can align safety compliance, technology deployment, and end-to-end waste management into coherent service offerings. They also define the boundaries of competitive advantage: scale alone is insufficient without operational discipline, and technology alone is insufficient without integration into customer workflows.
PW Consulting Information & Electronics Research Center
2. Core Drivers Reshaping the Market
The market's growth trajectory is being propelled by a set of interconnected drivers that extend beyond incremental demand increases. Understanding these drivers is essential for decision-makers evaluating capacity investments, service portfolio adjustments, or partnership strategies.
Technological Innovation and the Automation Imbalance
Automated cleaning systems, robotic entry platforms, and online desludging technologies are transitioning from niche capabilities to commercially viable differentiators. The value proposition is multifaceted: reduced worker exposure to hazardous atmospheres, higher consistency in cleaning outcomes, faster turnaround times, and improved recovery of residual hydrocarbons and 슬러드 materials. Recent commercial activity reflects this shift. In 2025, a major service provider announced a nationwide rollout of upgraded robotic crude oil tank cleaning services, integrating advanced robotic systems, online desludging technologies, and enhanced oil sludge recovery solutions. This type of deployment signals a broader industry movement where automation is no longer framed solely as a cost-reduction tool but as a compliance and risk-management enabler.
For operators and investors, the strategic implication is that technology adoption is becoming a marker of service quality and operational maturity. Facilities evaluating service partners are increasingly weighting automation capabilities alongside safety records, geographic coverage, and waste-handling integration. Providers that can demonstrate repeatable automated cleaning protocols, validated residue recovery rates, and seamless handoff to downstream treatment processes are positioning themselves for preferential contracting in high-value segments. Conversely, operators that treat automation as a peripheral upgrade rather than a core capability risk being relegated to price-competitive, lower-margin segments where differentiation is difficult to sustain.
Regulatory Pressure and Compliance as a Service Differentiator
Regulation continues to be a primary catalyst for service demand, but its influence is evolving from blanket compliance requirements to more granular, risk-based expectations. Confined space entry protocols, atmospheric testing mandates, personal protective equipment standards, and exposure limits for hydrocarbon vapors and gases are now embedded in operational guidance that supervisors and entry teams must administer and implement consistently. These requirements do not merely add procedural steps; they reshape the economics of tank cleaning by elevating the importance of trained personnel, documented procedures, and auditable compliance trails.
Regulatory dynamics also extend beyond the cleaning act itself. The broader waste management landscape is seeing heightened scrutiny around contaminant management, including emerging expectations around complex substances such as PFAS. These expectations are pushing service providers to expand their capabilities beyond cleaning into treatment, storage, disposal, and advanced contaminant handling. The market response has been visible in recent corporate activity, with major environmental services players pursuing acquisitions that substantially expand their hazardous waste footprint and treatment infrastructure. One such transaction, completed in 2026, nearly doubled a leading provider's U.S. hazardous waste footprint and strengthened capabilities across treatment, storage, disposal, and advanced contaminant management. This move illustrates how regulatory and compliance pressures are reshaping industry structure by rewarding operators that can offer integrated, end-to-end solutions rather than fragmented services.
For procurement teams and facility operators, the takeaway is that compliance risk is increasingly transmitted through service provider selection. Vendors with robust safety governance, documented permitting processes, and integrated waste-handling pathways reduce the operational and regulatory burden on the customer. In this environment, compliance capability is not a back-office function; it is a commercial attribute that directly influences contracting decisions.
Demand-Side Shifts Across Industrial and Energy value Chains
Demand for tank cleaning services is being shaped by changes in how industrial and energy operators manage storage, throughput, and product transitions. In the oil and gas sector, fluctuating throughput patterns, shifts in crude quality, and the need to maintain tank integrity across varying product slates increase the frequency and complexity of cleaning cycles. Chemical sector demand is driven by product changeovers, residue management requirements, and the need to prevent cross-contamination in multi-use storage systems. Water and wastewater treatment operations, while representing a smaller share of overall demand, are influenced by sludge removal cycles, regulatory reporting, and infrastructure maintenance schedules. Food and beverage applications, though more modest in scale, require strict hygiene and contamination-control protocols that elevate cleaning standards and documentation requirements.
What ties these segments together is a common theme: tank cleaning is no longer a reactive maintenance activity but a scheduled, compliance-linked component of operational planning. Customers are increasingly seeking providers who can align cleaning cycles with production schedules, minimize downtime, and deliver consistent outcomes that support downstream quality and environmental reporting. This shift favors service providers that can offer predictable scheduling, transparent performance metrics, and flexible engagement models tailored to specific facility constraints.
Supply Chain and Cost Structure Dynamics
Cost structures in the tank cleaning market are being reshaped by labor dynamics, equipment procurement, waste disposal pathways, and geographic variability in regulatory and logistics costs. Labor remains a central cost driver, and the safety and training requirements associated with confined space entry and hazardous residue handling mean that workforce quality directly affects both cost and risk. At the same time, the growing availability of automated and robotic systems is creating a pathway to reduce labor intensity for suitable cleaning scenarios, though the economics depend on tank configuration, residue profile, and utilization rates.
Waste handling and disposal costs add another layer of complexity. As downstream treatment requirements become more specialized, providers must either develop in-house capabilities, secure long-term partnerships with treatment facilities, or structure service offerings that clearly delineate cleaning from waste management responsibilities. The cost implications are significant: operators that can internalize or tightly coordinate waste handling gain cost predictability and service integration advantages, while those that rely on fragmented external arrangements face greater exposure to price volatility and compliance gaps.
Worldwide Industrial Cleaning Services Market
Overall, the cost structure trend favors integrated service models that combine cleaning, recovery, and waste management within a coordinated operational framework. This integration reduces handoff friction, improves cost visibility, and strengthens the value proposition for customers seeking to simplify vendor management and reduce compliance risk.
Underwater Hull Cleaning Service Market
3. Competitive Landscape and Emerging Strategic Positions
The market's competitive structure reflects a mix of established environmental services players, specialized tank cleaning providers, and regional operators with strong local footprints. Concentration metrics indicate that the top three providers account for roughly 46.8 percent of market revenue, while the top five capture approximately 58.2 percent. This level of concentration suggests that scale, brand recognition, and integrated service capabilities confer meaningful advantages, but it also leaves substantial room for specialized and regionally focused players that can compete on service quality, responsiveness, and niche technical capabilities.
Strategic Positioning Among Leading Providers
Several patterns emerge when examining how leading providers position themselves within the market. Large environmental services companies are increasingly leveraging acquisitions and capability expansion to build end-to-end portfolios that span cleaning, treatment, storage, disposal, and advanced contaminant management. This strategy is designed to capture value across the full service lifecycle, reduce customer fragmentation, and strengthen compliance-related value propositions. By broadening their hazardous waste and treatment footprint, these providers can offer customers a more unified operational relationship and greater assurance around downstream waste handling.
Specialized tank cleaning providers, by contrast, often compete on technical depth, regional coverage, and service responsiveness. Their differentiation frequently rests on demonstrable safety performance, experienced field crews, flexible scheduling, and the ability to tailor cleaning protocols to specific tank configurations and residue types. In markets where customers prioritize rapid turnaround, localized service, or specialized sludge recovery, these providers can maintain strong positions even as larger players expand their footprints.
Technology-focused entrants and expanding incumbents are also carving out positions centered on automation and robotic cleaning. Their appeal lies in reduced worker exposure, consistent cleaning outcomes, and the ability to handle complex sludge profiles with minimal manual intervention. As these capabilities mature, they are increasingly being incorporated into broader service portfolios rather than sold as standalone innovations, reflecting a market trend toward integrated, capability-rich offerings.
Market Evolution: Consolidation, Differentiation, and New Entrants
The competitive landscape is evolving along three parallel tracks. The first is consolidation, driven by the desire to expand geographic coverage, integrate waste management capabilities, and achieve economies of scale in safety infrastructure, equipment deployment, and regulatory compliance. Recent acquisition activity in the broader environmental services space illustrates this trend, with major players seeking to strengthen their U.S. hazardous waste footprint and expand treatment and contaminant management capabilities. For the tank cleaning segment, consolidation can raise the bar for integrated service quality while also increasing the resource intensity required to compete at scale.
The second track is differentiation through technology and service design. Providers that invest in robotic systems, online desludging, enhanced residue recovery, and digital scheduling or performance tracking are creating identifiable value propositions that distinguish them from more traditional manual-service models. This differentiation is particularly relevant for customers in high-throughput or high-compliance environments where cleaning consistency, safety, and downtime reduction are prioritized.
The third track involves new entrants and regional specialists that compete by addressing localized demand patterns, niche tank types, or specific industry requirements. In fragmented geographies or specialized application areas, these players can sustain competitive positions by offering tailored service levels, strong customer relationships, and agile operational responses. The long-term challenge for such players is to scale capabilities without diluting the service quality and safety standards that underpin their reputations.
Taken together, the competitive evolution suggests that the market will increasingly reward providers that can combine operational safety, technological capability, and integrated waste-handling or treatment pathways. Pure price competition in undifferentiated service segments is likely to remain intense, but value creation will increasingly concentrate in offerings that reduce customer risk, improve throughput predictability, and align cleaning with broader operational and compliance objectives.
4. Forward Outlook: Key Trends Shaping 2027–2032
Based on current growth trajectories, regulatory direction, and recent commercial activity, several trends are likely to define the market over the next three to five years.
Automation Moves from Differentiator to Baseline Expectation in Select Segments
Robotic and automated cleaning systems will become increasingly common in applications where tank geometry, residue characteristics, and throughput economics support their deployment. As equipment costs moderate, utilization models improve, and customer familiarity grows, automation is expected to transition from a premium offering to a standard consideration in many high-value service engagements. The commercial opportunity lies not only in equipment deployment but in packaging automation with validated performance metrics, recovery outcomes, and integration into customer maintenance schedules. Providers that can demonstrate repeatable results and measurable downtime reduction will be best positioned to capture preference in segments where operational efficiency and safety are jointly prioritized.
Integrated Service Models Gain Commercial Weight
The market is likely to see continued movement toward bundled or tightly coordinated service models that combine cleaning, residue recovery, waste handling, and, where relevant, advanced contaminant management. This trend is reinforced by regulatory expectations, customer desire for simplified vendor management, and the cost advantages of coordinating downstream processes. For providers, the strategic task is to build or secure the capabilities needed to offer credible end-to-end pathways without overextending into areas where operational complexity or capital requirements outweigh the returns. For customers, integrated models can reduce compliance friction and improve cost predictability, but they also require careful evaluation of provider capabilities across the full service chain.
Safety and Compliance Capability Become Procurement-Critical Attributes
Safety performance, documented permitting processes, atmospheric testing protocols, and exposure management are expected to remain central to service selection, with increasing emphasis on auditable compliance trails and consistent field execution. Recent enforcement actions and regulatory guidance reinforce the message that compliance failures carry substantial financial and operational consequences. As a result, procurement teams are likely to place greater weight on safety records, training rigor, and procedural discipline when evaluating providers. This shift creates an opportunity for operators that can institutionalize safety and compliance as visible, verifiable components of their service offering rather than treating them as internal operational concerns.
Potential Risks and Uncertainties
Several factors could alter the trajectory of these trends. Regulatory requirements may evolve unevenly across regions, creating compliance complexity for multi-geography operators and potentially raising the cost of standardized service delivery. Technology adoption may progress more slowly than anticipated in segments where tank configurations, residue variability, or capital constraints limit automation feasibility. Labor market conditions could continue to pressure cost structures and workforce availability, particularly in markets where specialized training and safety certification are required. Finally, waste handling and disposal pathways may face their own regulatory or capacity constraints, affecting the economics of integrated service models and the ability to deliver consistent downstream outcomes. Decision-makers should monitor these variables closely, as they can influence both service costs and the feasibility of specific operational strategies.
5. Strategic Considerations for Decision-Makers
For executives, planners, and investors evaluating the tank cleaning service market, the current environment offers both clear opportunities and distinct execution risks. The following considerations can help frame next steps across common stakeholder perspectives.
For Service Providers and Operators
- Align automation investments with application suitability rather than pursuing broad deployment. Prioritize tank types, residue profiles, and throughput scenarios where robotic or automated systems can deliver measurable improvements in safety, turnaround time, and residue recovery.
- Strengthen safety governance and compliance documentation as visible commercial assets. Ensure atmospheric testing, permit administration, exposure management, and confined space entry procedures are consistently executed and auditable, reducing both operational risk and customer procurement concern.
- Evaluate integration opportunities across cleaning, recovery, and waste handling. Where feasible, coordinate downstream processes to improve cost predictability, reduce handoff friction, and strengthen the value proposition for customers seeking simplified vendor relationships.
For Investors and Corporate Strategists
- Assess consolidation potential in segments where integrated hazardous waste, treatment, and contaminant management capabilities create meaningful competitive advantage. Recent transaction activity suggests that expanding end-to-end footprints can strengthen market position, particularly where regulatory expectations are rising.
- Distinguish between technology novelty and commercially scalable capability. Investment theses should account for utilization rates, equipment deployment economics, customer adoption curves, and the extent to which automation is bundled into differentiated service offerings rather than sold as a standalone feature.
- Monitor regional demand dynamics and regulatory divergence. Growth opportunities may vary significantly by geography, and multi-market strategies should account for differences in compliance requirements, waste handling pathways, and labor market conditions.
For Procurement Teams and Facility Operators
- Incorporate safety performance, compliance documentation, and waste-handling integration into vendor evaluation criteria alongside pricing and scheduling flexibility. Total cost-of-ownership considerations increasingly include risk reduction, downtime predictability, and downstream treatment coordination.
- Request clear performance metrics for cleaning consistency, residue recovery, and turnaround time. Transparent, verifiable outcomes support better contracting decisions and reduce ambiguity in service-level expectations.
- Assess provider capability across the full service chain rather than evaluating cleaning in isolation. Providers that can demonstrate coordinated processes from cleaning through recovery and disposal may offer greater operational simplicity and compliance assurance.
The tank cleaning service market is entering a period where growth is increasingly tied to how well operators manage safety, technology, and integration. The providers and customers that succeed will be those who treat these elements not as separate operational concerns but as interconnected components of a commercially valuable service model. For decision-makers seeking detailed segmentation data, regional breakdowns, and tailored scenario analysis across the 2026–2032 forecast horizon, a comprehensive research report can provide the granular context needed to translate these market-level trends into specific commercial actions.
For detailed analysis of this topic, please visit the official page: Tank Cleaning Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


